Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Renewable Energy Transformer Market Trends to 2033 | 7.1% CAGR
Renewable Energy Transformer Market
Renewable Energy Transformer Market Trends to 2033 | 7.1% CAGR
Renewable Energy Transformer Market by Type (Distribution Transformer, Power Transformer, Others), by Insulation (Dry, Liquid Immersed), by Capacity (5 MVA to 100 MVA, 100 MVA to 500 MVA, 500 and above), by Application (Hydro Energy, Wind Farm, Solar PV, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 6, 2026|Base Year : 2025|Pages : 250
Key Insights & Executive Summary: Renewable Energy Transformer Market
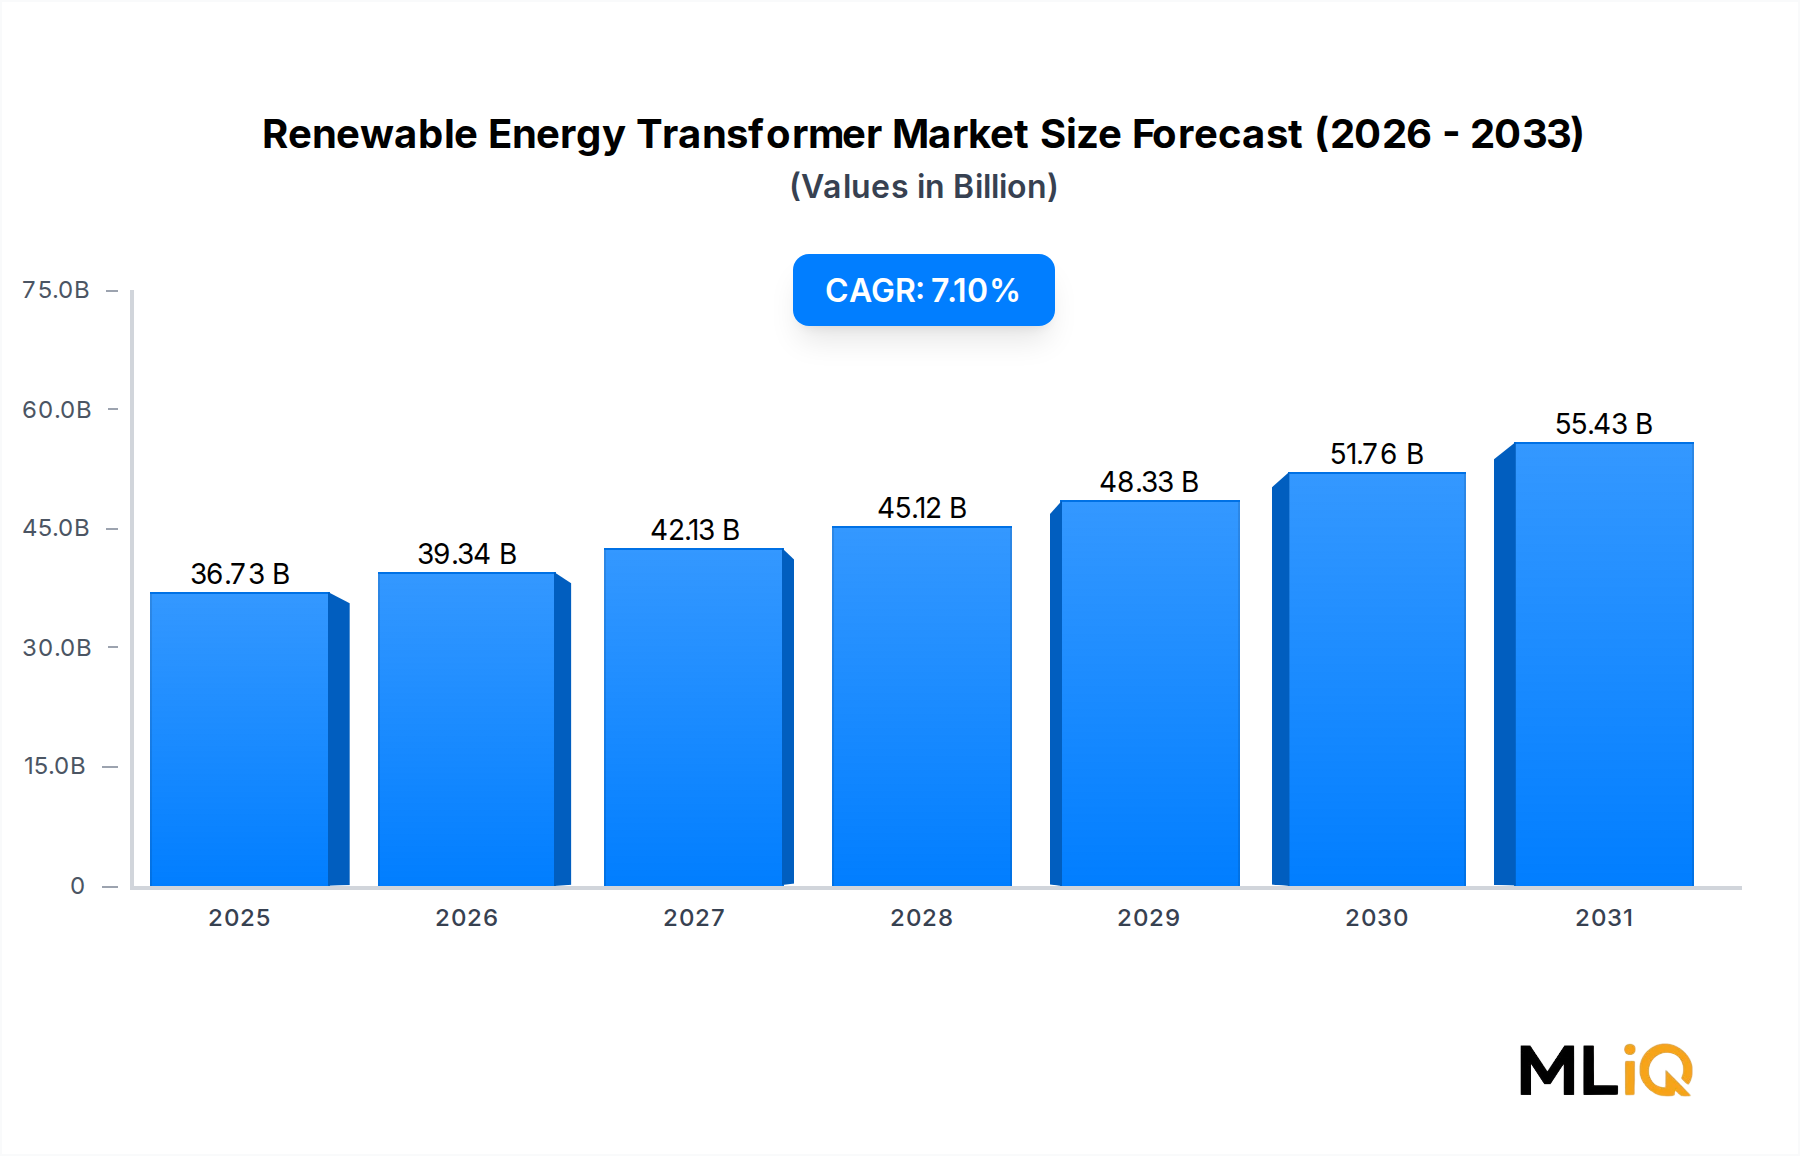
Renewable Energy Transformer Market Size (In Billion)
75.0B
60.0B
45.0B
30.0B
15.0B
0
36.73 B
2025
39.34 B
2026
42.13 B
2027
45.12 B
2028
48.33 B
2029
51.76 B
2030
55.43 B
2031
Market at a Glance
The Renewable Energy Transformer Market is being reordered by grid connection policy, interconnection queues, and the physical need to step up renewable plant voltages to transmission levels. The base-year value is USD 36.73 billion, and the 2025-2033 forecast trajectory reaches roughly USD 63.6 billion. A 7.1% CAGR shows that transformer demand is now increasing nearly as fast as global renewable capacity, making transformer procurement the new critical path for new generation.
In value terms, the Power Transformer Market accounts for the largest share of the total because utility-scale solar and wind projects require high-voltage units with higher insulation, copper, and test levels. The Distribution Transformer Market is the unit-volume engine and is more sensitive to housing, commercial rooftops, and feeder-level distributed generation. Together, these two type segments set the overall revenue base.
Technology choice is an important axis. The Liquid-immersed Transformer Market uses mineral oil or synthetic esters to cool high-power cores and remains dominant for substations above 100 MVA. The Dry-type Transformer Market is growing in markets where fire safety and indoor compactness matter, especially for solar-plus-storage and wind turbine tower applications.
By application, the Solar PV Transformer Market has the most fragmented deal flow, since projects range from small ground mounts to over 1 GW solar parks. The Wind Energy Transformer Market produces larger unit ratings on average, while the Offshore Wind Transformer Market introduces platform-specific high-voltage equipment. The Hydropower Transformer Market is driven by machine refurbishment and pumped-storage expansion. This broad application base reduces single-commodity cyclicality and keeps the Renewable Energy Transformer Market resilient even if one renewable sector pauses.
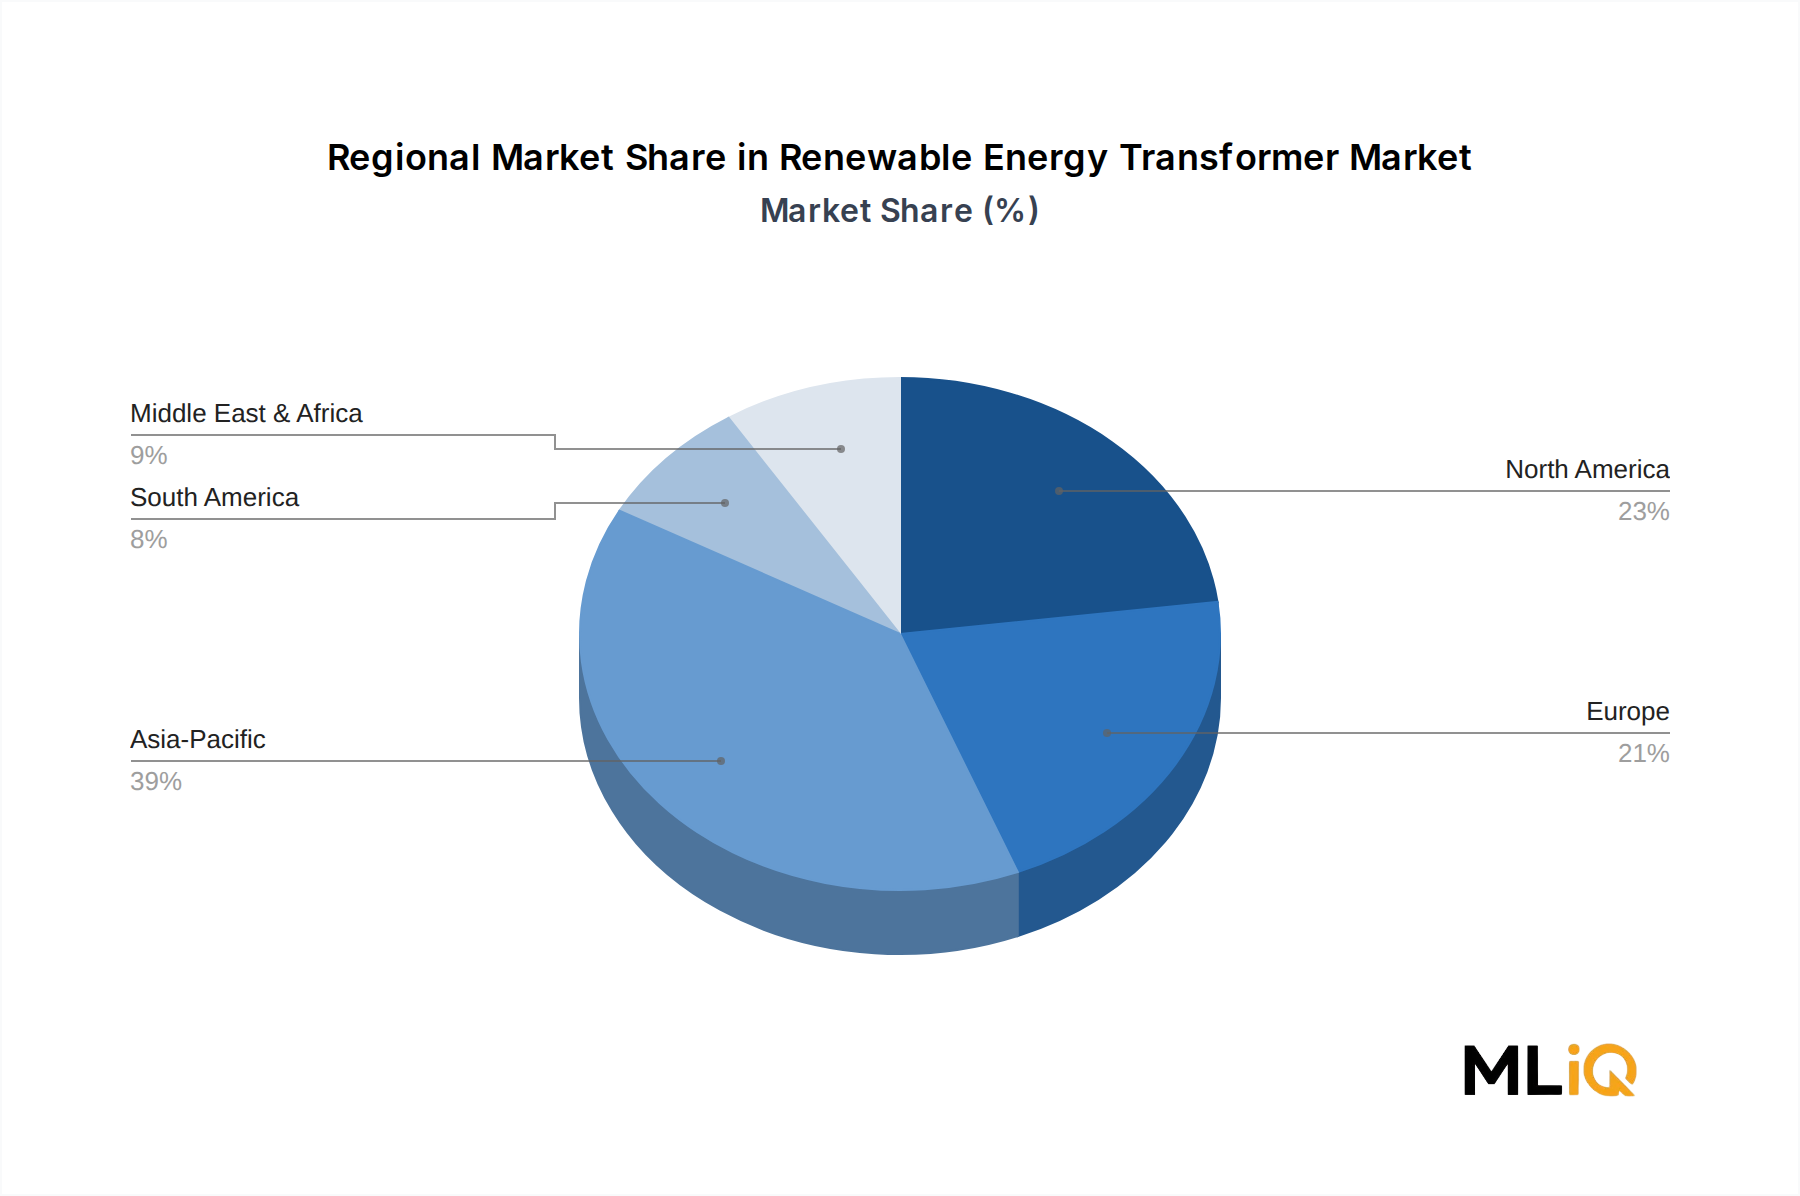
Asia-Pacific anchors the regional forecast. China, India, and Southeast Asia are expanding transmission corridors, and the regional revenue share approaches 39%. North America and Europe represent mature but committed grid-upgrade markets, while Middle East and Africa and South America create high-growth niches. The demand pattern points to a decade of capacity-constrained, specification-heavy procurement.
Segment Deep-Dive: Power Transformer Dominance in Renewable Energy Transformer Market
Value and Rating Dynamics
The Power Transformer Segment contributes an estimated 46% of Renewable Energy Transformer Market revenue in 2025. Most of that value sits in the 5 MVA to 100 MVA and 100 MVA to 500 MVA capacity bands, because those ranges cover wind farm collector substations, solar project switching stations, and regional bulk-power transformers. Units rated 500 MVA and above are lower in volume but carry the largest order value and the most demanding transient-voltage, short-circuit, and noise specifications.
Power transformers have longer lead times than distribution units because each high-voltage unit is generally engineered to a project-specific voltage ratio, vector group, cooling configuration, and altitude derating. This creates a strong concentration of orders among vendors with tested design platforms and global factory capacity.
Application Pull
Wind and solar plants around 100 MW to 500 MW now dominate interconnection queues in North America and Europe. A typical 300 MW solar farm requires station service transformers, unit auxiliary transformers, and at least one 220 kV step-up bank. Similarly, onshore wind clusters require collector substations that supply 33 kV medium-voltage wind turbines and raise power to 110 kV or 230 kV. The result is that the Power Transformer Market is aligned with the most valuable segment of renewable infrastructure: transmission-connected assets.
The Distribution Transformer Market also participates, but its per-unit price is only a fraction of a large power transformer, so revenue contribution is lower in monetary terms. The margin profile is different as well: standard distribution units face more aggressive price competition, while power transformers are procured through direct negotiation or regulated framework contracts.
Primary Market Drivers & Growth Restraints in Renewable Energy Transformer Market
Growth Catalysts
National grid decarbonization targets are converting renewable projects into long-term transformer demand. For example, the European Union has set offshore wind capacity goals that require high-voltage alternating current and high-voltage direct current platforms.
Distribution transformer demand is supported by U.S. municipal and co-op electrification grants, India's distribution metering and feeder upgrade programs, and distributed solar connection rules across Southeast Asia.
Repowering of existing wind and hydro sites often forces transformer replacement because generator output increases and older insulation systems no longer meet modern loss standards.
Operational Bottlenecks
Transformer manufacturing capacity remains concentrated in Korea, Japan, China, Mexico, and selected European plants. Global lead times for 345 kV and higher units reached 120 weeks or more in several recent procurement cycles, according to utility filings and industry groups.
Grain-oriented electrical steel, a critical raw material, is subject to export controls and limited producer capacity outside Asia. This keeps raw material availability at the center of delivery risk.
Skilled labor shortages in winding, assembly, and factory testing slow the commissioning of new plants, delaying relief even after capital investment expands.
These constraints do not suppress installed renewable capacity, but they do raise project developer risk and, in many cases, encourage earlier transformer procurement.
Competitive Ecosystem & Key Vendor Profiles: Renewable Energy Transformer Market
Eaton: Supplies distribution-class and dry-type transformers used in solar and microgrid installations; the company's breadth extends to switchgear and power quality systems.
Hammond Power Solutions: A North American dry-type transformer manufacturer active in commercial solar and industrial grid connections.
DAIHEN Corporation: Japanese transformer maker with products for large industrial plants, wind power, and utility distribution.
ABB: After divesting its power grids business, ABB still supplies dry-type distribution transformers and transformer digitalization products for renewable plants.
Bharat Heavy Electricals Limited: Indian public-sector manufacturer strong in high-voltage and extra-high-voltage transformers for hydro, thermal, and solar parks.
Hitachi, Ltd.: Parent group of Hitachi Energy, whose broad power transformer portfolio serves offshore wind, grid interconnections, and data-center substations.
Acutran: Canadian transformer specialist focused on custom liquid-immersed and dry-type units for renewable and industrial clients.
Siemens: Provides transformer systems and grid access solutions, especially in Europe, the Americas, and fast-growing Asian energy zones.
STC, Incorporated: Niche North American supplier of power and distribution transformers for electric utilities and renewable projects.
CG Power and Industrial Solutions Ltd: Indian-headquartered maker of transformers for renewable projects, rail, and utility segments; part of the Murugappa Group.
Strategic Milestones & Recent Developments in Renewable Energy Transformer Market
June 2024: Siemens Energy published an order backlog in its electricity grid product unit that reached record levels, with transformers supporting much of the volume.
October 2024: Hitachi Energy received a framework contract for grid transformers linked to European offshore wind buildout.
February 2025: Eaton expanded production of dry-type transformers for U.S. solar and data-center applications.
April 2025: Bharat Heavy Electricals Limited received an order for 765 kV transformers from an Indian inter-state transmission project, reinforcing high-voltage capacity demand.
Regional Market Analysis & Growth Corridors for Renewable Energy Transformer Market
Asia-Pacific remains the largest regional revenue pool with an estimated 39% share in 2025. China, India, Japan, ASEAN, and Oceania are building large-scale renewable zones and upgrading the transformer fleets that tie them to load centers. China's national transmission grid has made ultra-high-voltage and 220 kV-plus transformers a standard procurement category. India's renewable energy zones require high-voltage transformers in states such as Rajasthan, Gujarat, and Tamil Nadu.
North America holds about 23% of the global market, driven by U.S. Inflation Reduction Act incentives and Canadian hydro exports. The United States remains the highest-priced transformer market, partly because domestic factory capacity is insufficient. Europe accounts for roughly 21% and is led by offshore wind connections in the North Sea and the Baltic; European buyers use framework contracts for 400 kV and HVDC units.
South America has an estimated 8% share, with Brazil supplying hydro and wind projects and Chile active in solar. Middle East and Africa has a 9% share but the fastest forecast CAGR; utility-scale solar in Gulf states, South Africa's grid reforms, and new interconnections across North Africa are pulling demand earlier than historical baselines suggest.
In terms of regional momentum, Asia-Pacific has the largest absolute opportunity while Middle East and Africa has the strongest percentage trajectory. The most mature single market is Germany, where transformer replacement, not greenfield interconnection, is the dominant driver.
Investment, M&A & Funding Activity in Renewable Energy Transformer Market
The defining strategic move of the past five years is Hitachi's takeover of ABB Power Grids, now Hitachi Energy; that transaction brought power transformer supply and grid integration under a single ownership structure. More recent M&A activity has been smaller but consistent: transformer service and repair companies have been acquired by utilities and private investors because repair cycles are faster than factory deliveries.
Public money is also reallocating supply chains. The U.S. Department of Energy has supported transformer factory expansions through loan programs and the Defense Production Act. European governments are using Important Projects of Common European Interest to fund transformer R&D. Private equity has focused on dry-type and distribution transformer plants, where product standardization permits repeatable production and faster return on investment. High-growth pockets attracting capital include 100 MVA to 500 MVA liquid-immersed power transformers, offshore platform high-voltage equipment, and medium-voltage traction-class units.
Technology Innovation & R&D Trajectory in Renewable Energy Transformer Market
Three technologies could change both costs and delivery patterns. The solid-state transformer is the most radical: high-voltage power electronics manage voltage conversion without traditional magnetic coupling, enabling direct current collection and dynamic reactive power control. Pilot units are expected at medium-voltage solar and storage sites before 2027, while utility-scale adoption will likely remain limited until beyond 2032 because of reliability and semiconductor costs.
Amorphous metal transformer cores are making the strongest near-term impact on the Distribution Transformer Market. Amorphous low-loss steel cuts no-load losses by 50 to 60 percent and is becoming standard in newer efficiency requirements even though core handling and noise remain drawbacks. Liquid-immersed transformers using synthetic esters are improving fire safety and moisture tolerance, while digital sensors monitor dissolved gas, load, and remaining life. These trends reinforce the value of transformer OEMs that can integrate sensors with service contracts and reduce the need for physical spare inventory.
Renewable Energy Transformer Market Segmentation
1. Type
1.1. Distribution Transformer
1.2. Power Transformer
1.3. Others
2. Insulation
2.1. Dry
2.2. Liquid Immersed
3. Capacity
3.1. 5 MVA to 100 MVA
3.2. 100 MVA to 500 MVA
3.3. 500 and above
4. Application
4.1. Hydro Energy
4.2. Wind Farm
4.3. Solar PV
4.4. Others
Renewable Energy Transformer Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Renewable Energy Transformer Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.1% from 2020-2034
Segmentation
By Type
Distribution Transformer
Power Transformer
Others
By Insulation
Dry
Liquid Immersed
By Capacity
5 MVA to 100 MVA
100 MVA to 500 MVA
500 and above
By Application
Hydro Energy
Wind Farm
Solar PV
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Distribution Transformer
5.1.2. Power Transformer
5.1.3. Others
5.2. Market Analysis, Insights and Forecast - by Insulation
5.2.1. Dry
5.2.2. Liquid Immersed
5.3. Market Analysis, Insights and Forecast - by Capacity
5.3.1. 5 MVA to 100 MVA
5.3.2. 100 MVA to 500 MVA
5.3.3. 500 and above
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Hydro Energy
5.4.2. Wind Farm
5.4.3. Solar PV
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. South America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Distribution Transformer
6.1.2. Power Transformer
6.1.3. Others
6.2. Market Analysis, Insights and Forecast - by Insulation
6.2.1. Dry
6.2.2. Liquid Immersed
6.3. Market Analysis, Insights and Forecast - by Capacity
6.3.1. 5 MVA to 100 MVA
6.3.2. 100 MVA to 500 MVA
6.3.3. 500 and above
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Hydro Energy
6.4.2. Wind Farm
6.4.3. Solar PV
6.4.4. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Distribution Transformer
7.1.2. Power Transformer
7.1.3. Others
7.2. Market Analysis, Insights and Forecast - by Insulation
7.2.1. Dry
7.2.2. Liquid Immersed
7.3. Market Analysis, Insights and Forecast - by Capacity
7.3.1. 5 MVA to 100 MVA
7.3.2. 100 MVA to 500 MVA
7.3.3. 500 and above
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Hydro Energy
7.4.2. Wind Farm
7.4.3. Solar PV
7.4.4. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Distribution Transformer
8.1.2. Power Transformer
8.1.3. Others
8.2. Market Analysis, Insights and Forecast - by Insulation
8.2.1. Dry
8.2.2. Liquid Immersed
8.3. Market Analysis, Insights and Forecast - by Capacity
8.3.1. 5 MVA to 100 MVA
8.3.2. 100 MVA to 500 MVA
8.3.3. 500 and above
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Hydro Energy
8.4.2. Wind Farm
8.4.3. Solar PV
8.4.4. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Distribution Transformer
9.1.2. Power Transformer
9.1.3. Others
9.2. Market Analysis, Insights and Forecast - by Insulation
9.2.1. Dry
9.2.2. Liquid Immersed
9.3. Market Analysis, Insights and Forecast - by Capacity
9.3.1. 5 MVA to 100 MVA
9.3.2. 100 MVA to 500 MVA
9.3.3. 500 and above
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Hydro Energy
9.4.2. Wind Farm
9.4.3. Solar PV
9.4.4. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Distribution Transformer
10.1.2. Power Transformer
10.1.3. Others
10.2. Market Analysis, Insights and Forecast - by Insulation
10.2.1. Dry
10.2.2. Liquid Immersed
10.3. Market Analysis, Insights and Forecast - by Capacity
10.3.1. 5 MVA to 100 MVA
10.3.2. 100 MVA to 500 MVA
10.3.3. 500 and above
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Hydro Energy
10.4.2. Wind Farm
10.4.3. Solar PV
10.4.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Eaton
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Hammond Power Solutions
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. DAIHEN Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. ABB
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Bharat Heavy Electricals Limited
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Hitachi
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Ltd.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Acutran
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Siemens
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. STC
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Incorporated
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. CG Power and Industrial Solutions Ltd
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Renewable Energy Transformer Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Renewable Energy Transformer Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Renewable Energy Transformer Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Renewable Energy Transformer Market Revenue (billion), by Insulation 2026 & 2034
Figure 5: North America Renewable Energy Transformer Market Revenue Share (%), by Insulation 2026 & 2034
Figure 6: North America Renewable Energy Transformer Market Revenue (billion), by Capacity 2026 & 2034
Figure 7: North America Renewable Energy Transformer Market Revenue Share (%), by Capacity 2026 & 2034
Figure 8: North America Renewable Energy Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 9: North America Renewable Energy Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Renewable Energy Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 11: North America Renewable Energy Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 12: South America Renewable Energy Transformer Market Revenue (billion), by Type 2026 & 2034
Figure 13: South America Renewable Energy Transformer Market Revenue Share (%), by Type 2026 & 2034
Figure 14: South America Renewable Energy Transformer Market Revenue (billion), by Insulation 2026 & 2034
Figure 15: South America Renewable Energy Transformer Market Revenue Share (%), by Insulation 2026 & 2034
Figure 16: South America Renewable Energy Transformer Market Revenue (billion), by Capacity 2026 & 2034
Figure 17: South America Renewable Energy Transformer Market Revenue Share (%), by Capacity 2026 & 2034
Figure 18: South America Renewable Energy Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 19: South America Renewable Energy Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 20: South America Renewable Energy Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 21: South America Renewable Energy Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Europe Renewable Energy Transformer Market Revenue (billion), by Type 2026 & 2034
Figure 23: Europe Renewable Energy Transformer Market Revenue Share (%), by Type 2026 & 2034
Figure 24: Europe Renewable Energy Transformer Market Revenue (billion), by Insulation 2026 & 2034
Figure 25: Europe Renewable Energy Transformer Market Revenue Share (%), by Insulation 2026 & 2034
Figure 26: Europe Renewable Energy Transformer Market Revenue (billion), by Capacity 2026 & 2034
Figure 27: Europe Renewable Energy Transformer Market Revenue Share (%), by Capacity 2026 & 2034
Figure 28: Europe Renewable Energy Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 29: Europe Renewable Energy Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Europe Renewable Energy Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 31: Europe Renewable Energy Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 32: Middle East & Africa Renewable Energy Transformer Market Revenue (billion), by Type 2026 & 2034
Figure 33: Middle East & Africa Renewable Energy Transformer Market Revenue Share (%), by Type 2026 & 2034
Figure 34: Middle East & Africa Renewable Energy Transformer Market Revenue (billion), by Insulation 2026 & 2034
Figure 35: Middle East & Africa Renewable Energy Transformer Market Revenue Share (%), by Insulation 2026 & 2034
Figure 36: Middle East & Africa Renewable Energy Transformer Market Revenue (billion), by Capacity 2026 & 2034
Figure 37: Middle East & Africa Renewable Energy Transformer Market Revenue Share (%), by Capacity 2026 & 2034
Figure 38: Middle East & Africa Renewable Energy Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 39: Middle East & Africa Renewable Energy Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Middle East & Africa Renewable Energy Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 41: Middle East & Africa Renewable Energy Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Asia Pacific Renewable Energy Transformer Market Revenue (billion), by Type 2026 & 2034
Figure 43: Asia Pacific Renewable Energy Transformer Market Revenue Share (%), by Type 2026 & 2034
Figure 44: Asia Pacific Renewable Energy Transformer Market Revenue (billion), by Insulation 2026 & 2034
Figure 45: Asia Pacific Renewable Energy Transformer Market Revenue Share (%), by Insulation 2026 & 2034
Figure 46: Asia Pacific Renewable Energy Transformer Market Revenue (billion), by Capacity 2026 & 2034
Figure 47: Asia Pacific Renewable Energy Transformer Market Revenue Share (%), by Capacity 2026 & 2034
Figure 48: Asia Pacific Renewable Energy Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 49: Asia Pacific Renewable Energy Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 50: Asia Pacific Renewable Energy Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 51: Asia Pacific Renewable Energy Transformer Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Renewable Energy Transformer Market Revenue billion Forecast, by Type 2020 & 2034
Table 2: Renewable Energy Transformer Market Revenue billion Forecast, by Insulation 2020 & 2034
Table 3: Renewable Energy Transformer Market Revenue billion Forecast, by Capacity 2020 & 2034
Table 4: Renewable Energy Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 5: Renewable Energy Transformer Market Revenue billion Forecast, by Region 2020 & 2034
Table 6: North America Renewable Energy Transformer Market Revenue billion Forecast, by Type 2020 & 2034
Table 7: North America Renewable Energy Transformer Market Revenue billion Forecast, by Insulation 2020 & 2034
Table 8: North America Renewable Energy Transformer Market Revenue billion Forecast, by Capacity 2020 & 2034
Table 9: North America Renewable Energy Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 10: North America Renewable Energy Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 11: United States Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: Canada Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 14: South America Renewable Energy Transformer Market Revenue billion Forecast, by Type 2020 & 2034
Table 15: South America Renewable Energy Transformer Market Revenue billion Forecast, by Insulation 2020 & 2034
Table 16: South America Renewable Energy Transformer Market Revenue billion Forecast, by Capacity 2020 & 2034
Table 17: South America Renewable Energy Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 18: South America Renewable Energy Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 19: Brazil Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 20: Argentina Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 21: Rest of South America Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 22: Europe Renewable Energy Transformer Market Revenue billion Forecast, by Type 2020 & 2034
Table 23: Europe Renewable Energy Transformer Market Revenue billion Forecast, by Insulation 2020 & 2034
Table 24: Europe Renewable Energy Transformer Market Revenue billion Forecast, by Capacity 2020 & 2034
Table 25: Europe Renewable Energy Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 26: Europe Renewable Energy Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 27: United Kingdom Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Germany Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: France Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Italy Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Spain Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Russia Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 33: Benelux Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 34: Nordics Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: Rest of Europe Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Middle East & Africa Renewable Energy Transformer Market Revenue billion Forecast, by Type 2020 & 2034
Table 37: Middle East & Africa Renewable Energy Transformer Market Revenue billion Forecast, by Insulation 2020 & 2034
Table 38: Middle East & Africa Renewable Energy Transformer Market Revenue billion Forecast, by Capacity 2020 & 2034
Table 39: Middle East & Africa Renewable Energy Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 40: Middle East & Africa Renewable Energy Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 41: Turkey Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Israel Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 43: GCC Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 44: North Africa Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 45: South Africa Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 46: Rest of Middle East & Africa Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: Asia Pacific Renewable Energy Transformer Market Revenue billion Forecast, by Type 2020 & 2034
Table 48: Asia Pacific Renewable Energy Transformer Market Revenue billion Forecast, by Insulation 2020 & 2034
Table 49: Asia Pacific Renewable Energy Transformer Market Revenue billion Forecast, by Capacity 2020 & 2034
Table 50: Asia Pacific Renewable Energy Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 51: Asia Pacific Renewable Energy Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 52: China Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 53: India Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 54: Japan Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 55: South Korea Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 56: ASEAN Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 57: Oceania Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 58: Rest of Asia Pacific Renewable Energy Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research represented approximately 75% of total input, within the required 70/30 split between primary and secondary sources.
Interviews were conducted with transformer and component OEMs, CRGO steel producers, renewable project EPC firms, and transmission utilities. Role titles covered Director of High-Voltage Equipment Procurement, Grid Connection Manager, Product Segment Manager for Power Transformers, and Transformer Testing and Certification Lead.
Primary surveys captured order backlogs, factory utilization, product lead times, and vendor-specific capacity plans. Interviews also included buyers of grain-oriented electrical steel and high-voltage bushing suppliers, providing cross-checks on transformer production quantities.
The exact report scope covers Type, Insulation, Capacity, Application, and regional blocks including North America, South America, Europe, Middle East and Africa, and Asia-Pacific, with the forecast extended through 2034.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of High-Voltage Equipment Procurement
35%
Grid Connection Manager
30%
Product Segment Manager - Power Transformers
25%
Transformer Testing & Certification Lead
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Transformer OEMs
38%
Electrical Steel & Raw Material Suppliers
24%
Renewable Developers and EPC Firms
23%
Utilities and TSOs
15%
Secondary Research & Industry Benchmarking
Secondary research used Bloomberg, Factiva, Hoovers, PitchBook, and other financial and industry databases to verify ownership, financial performance, and transaction history.
Trade publications, conference proceedings, and government grid-development plans were used to validate transformer voltage bands, certification requirements, and regional technology preferences.
Demand Modeling & Market Estimation
A top-down model allocated global transformer revenue to renewable applications using renewable electricity generation shares, power-plant capacity additions, and utility capital expenditure data.
A bottom-up model summed shipment volumes across transformer types, insulation classes, capacities, and applications. Volumes were converted into revenue using average selling prices collected from procurement tenders and OEM quotations.
The bottom-up calculation used metrics including GW of awarded wind and solar capacity, MVA per connection request, number of EHV transformer units per interconnection, transformer replacement vintage, and share of output assigned to renewable generation.
Both views were applied simultaneously and reconciled through multi-level data triangulation to avoid overstatement of either capacity or pricing trends.
Data Accuracy & Quality Check
The resulting market estimates carry a guaranteed data accuracy range of 85 to 90 percent. This is supported by inline checks against regulatory interconnection filings, utility procurement announcements, and annual reports.
Where publicly recorded figures diverged from survey feedback by more than 15 percent, analyst judgment was replaced by a second-round interview with the relevant stakeholder group.
Every report is updated to the date of purchase, and baseline assumptions are revalidated against the latest monthly capacity and price indicators at that time.
Frequently Asked Questions
1. What are the largest supply-chain risks facing the Renewable Energy Transformer Market in the next decade?
The main risks are long lead times for high-voltage power transformers, shortages of grain-oriented electrical steel, and grid interconnection backlogs. In 2025, a typical 220–400 kV transformer can require an 18–36 month manufacturing and test cycle. Trade restrictions on steel and offshore logistics bottlenecks amplify project schedule risk.
2. What is the current value of the Renewable Energy Transformer Market and how fast is it growing?
The market is valued at USD 36.73 billion in 2025 and is projected to grow at a 7.1% CAGR to USD 63.6 billion by 2033. Growth is led by solar and wind interconnection, substation upgrades, and replacement demand for aging transformer fleets.
3. Which region dominates the Renewable Energy Transformer Market and why?
Asia-Pacific dominates with a 39% share of global revenue. China remains the largest single country for wind and solar equipment procurement, while India, Southeast Asia, and Japan are modernizing transmission networks to handle higher renewable penetration.
4. What recent deals or developments have influenced the Renewable Energy Transformer Market?
Hitachi's acquisition of ABB Power Grids created Hitachi Energy and reshaped vendor scale. More recently, capacity expansion announcements from Siemens, ABB, and Hitachi Energy have targeted high-voltage transformers for offshore wind and grid reinforcement, and U.S. policy incentives have drawn new domestic transformer plants.
5. Which region is expected to grow fastest in the Renewable Energy Transformer Market?
Middle East and Africa is projected to grow at the fastest percentage rate, although from a smaller base. Large desert solar programs, grid expansion in South Africa and North Africa, and data-center growth in the Gulf states are creating early-stage demand for renewable-dedicated transformers.
6. Who are the major end users demanding renewable energy transformers and what procurement patterns dominate?
Key end users are wind project developers, solar IPPs, hydropower operators, transmission system owners, and utilities purchasing distribution transformers. Procurement is increasingly governed by long-term framework agreements and engineering specifications for voltage level, short-circuit resilience, and low-loss operation.