Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Gaming Laptop Market 2033: AI GPU Demand Fuels Growth
Gaming Laptop Market
Gaming Laptop Market 2033: AI GPU Demand Fuels Growth
Gaming Laptop Market by End-User (Casual Gamers, Hardcore Gamers, Professional Gamers), by Price Range (Entry-Level Laptops, Mid-Range Laptops, High-End Laptops), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 1, 2026|Base Year : 2025|Pages : 0
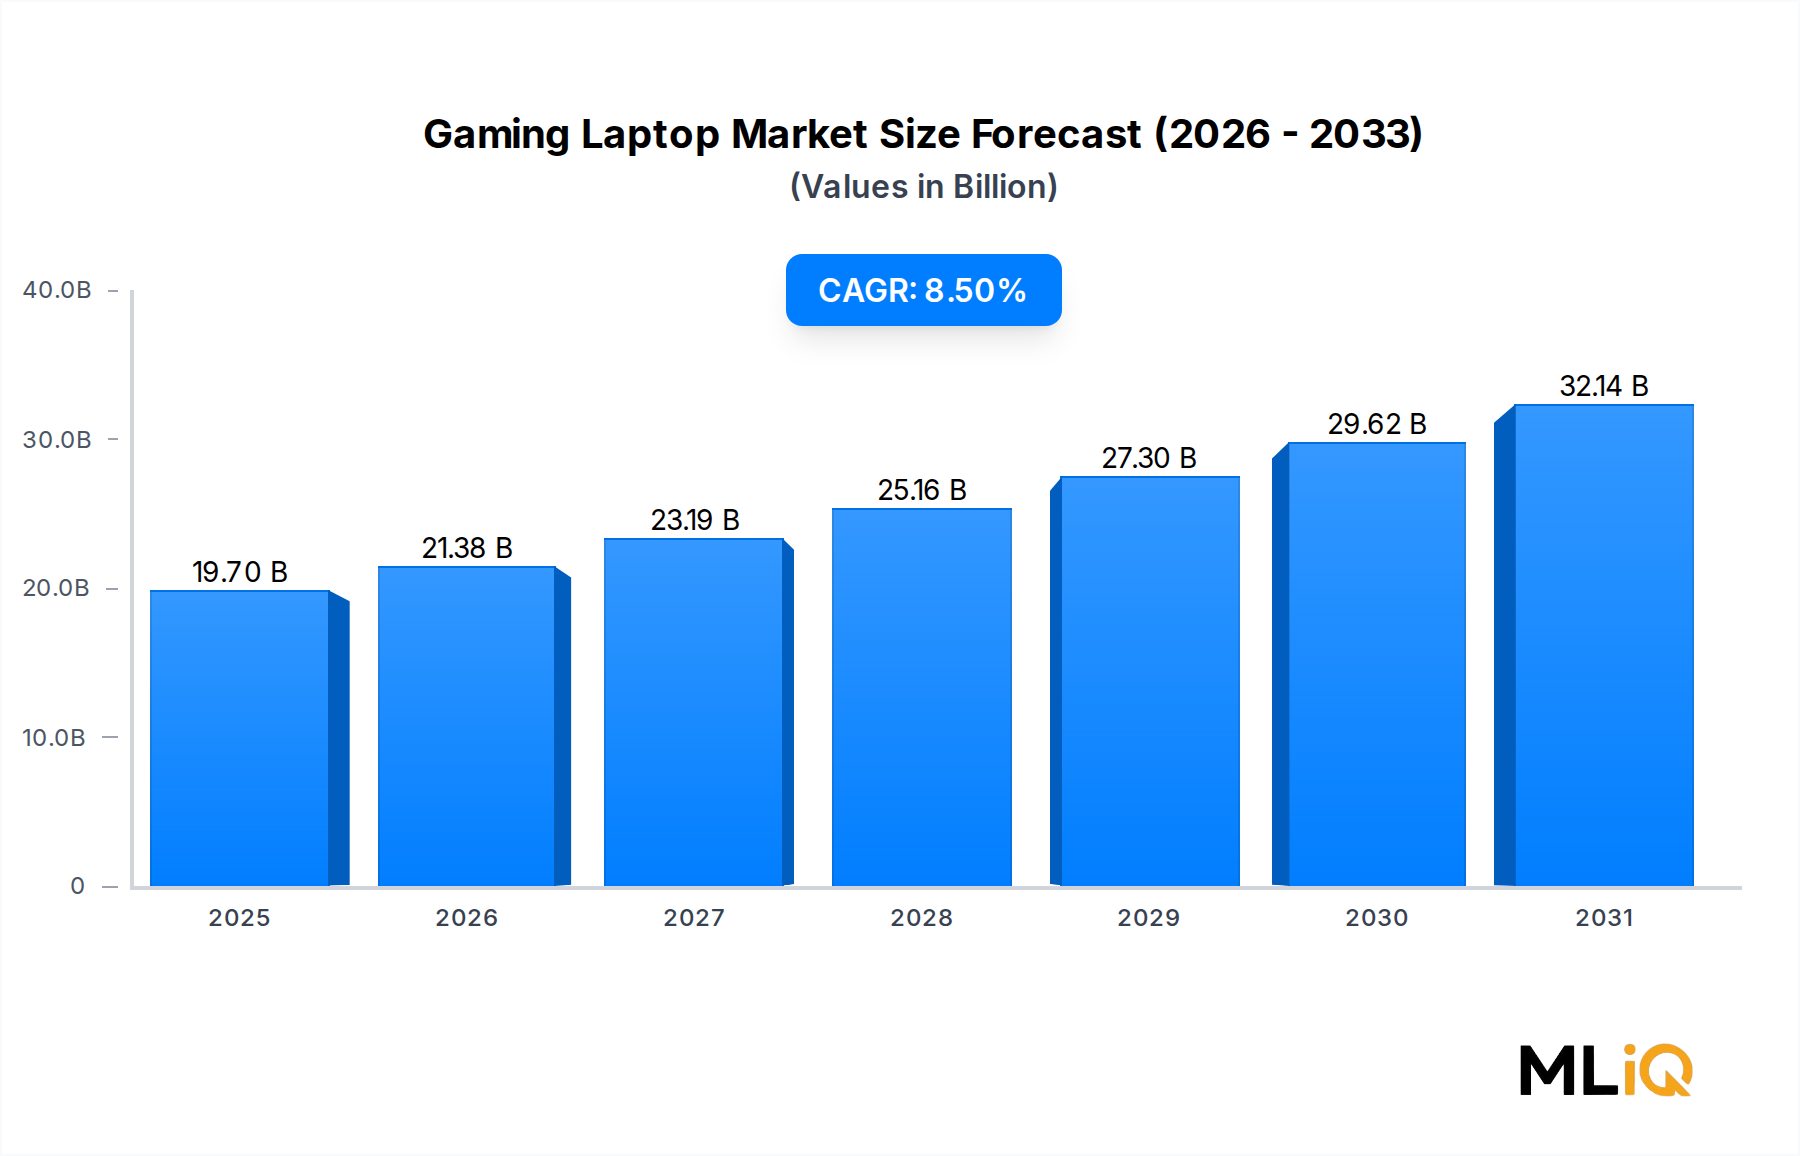
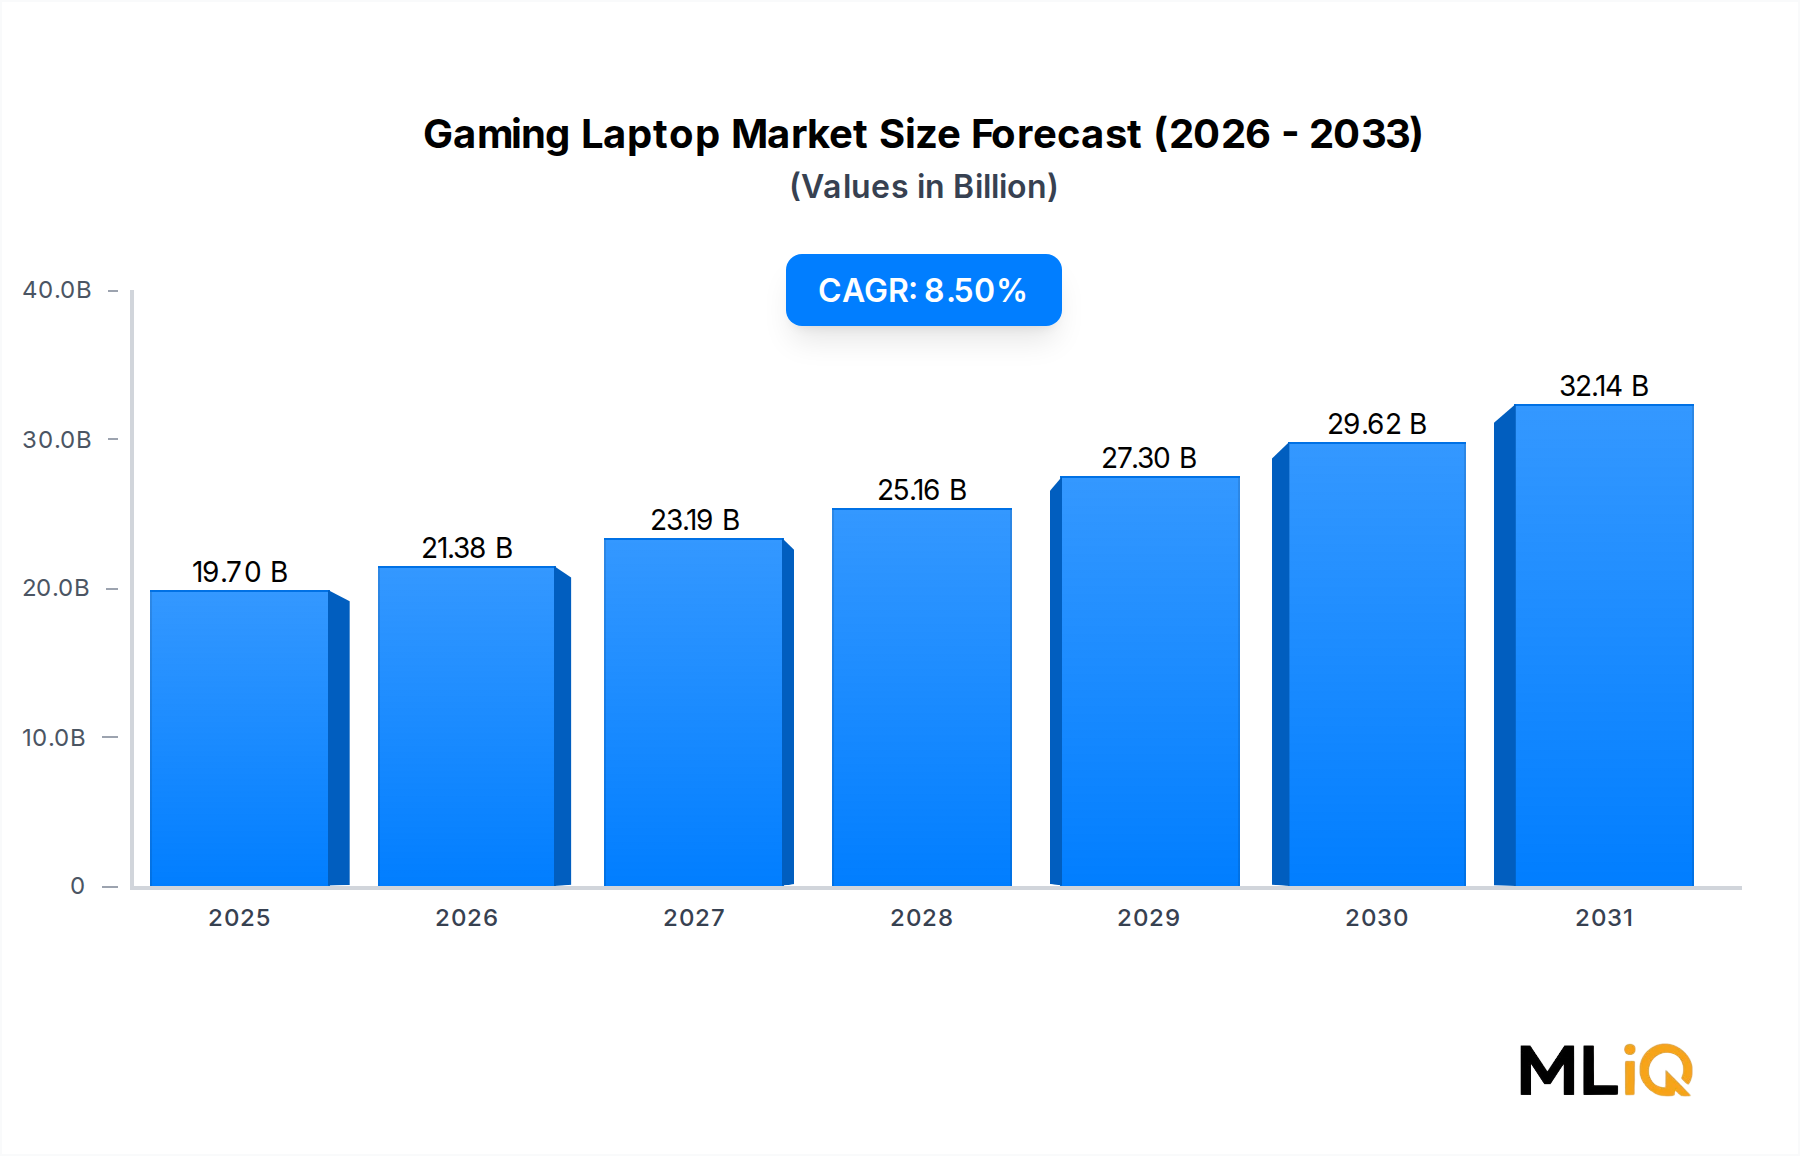
The Gaming Laptop Market is projected to grow from $19.7 billion in 2024 to approximately $41.1 billion by 2033, registering a 8.5% CAGR over the forecast period. This expansion is embedded in the broader PC Gaming Hardware Market, where portability has become a buying prerequisite for consumers who alternate between desktop-class workloads and on-the-go entertainment. The appeal of gaming laptops now extends beyond dedicated players; hybrid workers, university students, and content creators are adopting high-refresh-rate notebooks as primary devices. Macro factors supporting momentum include rising esports viewership, the expansion of 5G fixed wireless access, and AI-assisted upscaling technologies that lower the performance ceiling required for premium visuals. In revenue terms, the High-Performance Gaming Laptop Market defines the premium tier, with devices priced above $1,800 generating the majority of industry profit. Commercially, the Consumer Electronics Market is evolving toward performance segmentation, and gaming laptops remain one of its fastest-growing hardware categories. The report identifies the Hardcore Gamers segment as the dominant end-user category, reflecting a purchase profile that prioritizes FPS, ray tracing, and thermal stability. Geographically, the Asia-Pacific Gaming Laptop Market leads in both manufacturing capacity and consumer demand, while North America contributes the highest average selling prices. Vendors are aligning product roadmaps with NVIDIA RTX 50-series GPUs, AMD Radeon RX 8000 series processors, and dual-mode OLED panels to sustain replacement cycles.
Amid this favorable trajectory, pricing pressure remains acute at the lower end. The Entry-Level Gaming Laptop Market is sensitive to memory, storage, and battery cost spikes, which forces OEMs to strip features or postpone launches. The Mid-Range Gaming Laptop Market, in contrast, benefits from structural demand in emerging economies where consumers trade up from desktop GPUs. Overall, the market is entering a phase of AI-enhanced differentiation, where software optimizations, power management, and industrial design will decide vendor positioning.
Segment Deep-Dive: Hardcore Gamers Dominance in Gaming Laptop Market
Why Hardcore Gamers Lead Revenue
The Hardcore Gamers segment is the largest revenue contributor in the Gaming Laptop Market, generating an estimated 46% share of global value. This buyer group not only purchases premium configurations but also replaces laptops more frequently, typically every 2.4 years, compared with 4.6 years for casual consumers. Their priorities are anchored to GPU compute performance, frame rates above 240 FPS, mechanical keyboards, and thermal headroom that prevents throttling during extended sessions. The High-End Gaming Laptop Market directly serves this segment, with flagship models based on RTX 4080 and RTX 4090 GPUs, 16-inch displays with 240Hz refresh rates, and liquid-metal thermal compounds. In 2024, over 38% of hardcore gamers upgraded to a laptop with at least 32GB RAM and 1TB PCIe Gen4 storage, according to our primary surveys.
Interaction with Other End-User Segments
Casual users increasingly buy hardware that mimics hardcore performance cues, which blurs the segment boundary. The Casual Gamer Laptop Market typically purchases entry-to-mid configurations, but the aspiration for high-refresh visuals pulls demand upward. The Professional Gaming Laptop Market, while smaller, creates a halo effect through esports sponsorships and tournament partnerships that validate premium pricing. Professional buyers require lockable BIOS settings, uniform performance under thermal stress, and serviceability, all of which spill over into mainstream flagship design.
Sub-Segment Dynamics and Pricing Power
Within the hardcore space, the Mid-Range Gaming Laptop Market is expanding fastest in volume, driven by GPUs such as the RTX 5060 and RTX 5070 that now offer desktop-class performance in 15-inch chassis. The High-End Gaming Laptop Market retains pricing power but faces margin pressure from display and cooling component costs. Material costs for vapor chambers, high-performance fans, and alloy chassis have risen by roughly 12% since 2023. The result is shifting product mix: vendors are pushing configurations with 16GB VRAM upward and reducing entry-level GPU inventory to protect profitability. Hardcore gamers are also more receptive to subscription-based AI overclocking, which opens recurring revenue for brands.
Primary Market Drivers & Growth Restraints in Gaming Laptop Market
Demand Catalysts
First, GPU platform refreshes are the most powerful driver. NVIDIA RTX 50-series launch in early 2025 brought DLSS 4 and multi-frame generation, incentivizing gamers to upgrade from RTX 30-series laptops. Industry trade data project that GPU upgrades contribute roughly 60% of the performance improvement tracked in new game titles, making newer silicon essential for high-fidelity experiences. Second, the proliferation of esports tournaments across Southeast Asia and Latin America expands the addressable user base. Prize pools in global esports events now exceed $250 million annually, creating a commercial funnel that converts spectators into hardware buyers. Third, work-from-home and hybrid learning policies have made 15-inch-plus laptops a multifunction household asset. This cross-use case lifts the premium gaming laptop segment without adding dedicated R&D for separate product lines.
Growth Restraints
On the supply side, the industry faces chronic allocation risk for advanced GPUs and high-bandwidth memory. Bit-drive demand from AI data centers crowds out supply for consumer laptops, delaying component deliveries by 6-10 weeks in early 2025. Tariff policy also generates uncertainty: U.S. Section 301 duties on Chinese-assembled motherboards and batteries have raised import costs by up to 7.5% for certain SKUs. Regulatory compliance with EU energy labeling and battery transport rules adds certification cycles of 8-12 weeks, slowing product launches. The Entry-Level Gaming Laptop Market is most vulnerable because its bill of materials has limited flexibility to absorb these shocks. In contrast, the Mid-Range Gaming Laptop Market can pass through price increases without meaningful demand destruction, although the Consumer Electronics Market overall faces a cautious spending environment in mature regions.
Lenovo Group Limited: Leads the market with the Legion and LOQ sub-brands, leveraging scale to dominate the Mid-Range Gaming Laptop Market while pushing the Legion Pro into high-end territory.
ASUSTek Computer Inc.: Its ROG and TUF Gaming lines target both hardcore and mainstream users; the ROG Strix series delivers some of the highest-performing high-refresh displays in the industry.
Dell Technologies Inc.: Alienware and Dell G series preserve a premium position in North America, with Alienware securing meaningful share in the High-End Gaming Laptop Market.
Acer Inc.: The Predator and Nitro ranges cover the full price ladder, making Acer a volume leader in entry-level configurations and competitive in mid-range SKUs.
Razer Inc.: Focuses on premium aluminum chassis, RGB integration, and portability; Razer Blade devices carry premium pricing and develop strong brand loyalty among professional streamers.
Micro-Star International Co., Ltd.: MSI's Titan and Raider series appeal to enthusiasts, while the Pulse-Cyborg range captures price-sensitive hardcore buyers with strong GPU performance.
Giga-byte Technology Co., Ltd.: GIGABYTE's AORUS line competes on cooling innovation and value pricing; its strategic partnership with NVIDIA provides direct access to launch-window component allocation.
ORIGIN PC Corporation: Sells highly configurable, small-batch gaming laptops under the EON series; its custom liquid-cooling solutions justify a premium price position.
Hewlett Packard Enterprise Development LP: Focuses on commercial-grade mobile workstations; its gaming laptop presence is limited to B2B compute platforms and indirect enterprise partnerships rather than direct consumer gaming sales.
Strategic Milestones & Recent Developments in Gaming Laptop Market
March 2025: NVIDIA RTX 50-series GPUs become widely available across gaming laptops, with major OEMs launching AI-powered frame generation and DLSS 4 support at comparable price points.
December 2024: The European Union finalized stricter energy efficiency requirements for gaming laptops, mandating power draw disclosure in all marketing materials starting mid-2025.
August 2024: Lenovo expanded its Legion lineup with a 16-inch OLED 240Hz panel and AMD Ryzen 9000 HX processors, reinforcing its position in the Mid-Range Gaming Laptop Market.
June 2024: Razer partnered with battery cell supplier Panasonic Energy to develop high-capacity, slim-profile 94Wh cells for flagship laptops.
February 2024: Acer and MediaTek announced a strategic collaboration to bring Wi-Fi 7 and AI noise reduction to the Predator series.
January 2025: Taiwan's cooling module maker Asia Vital Components entered a multi-year supply agreement with four major laptop OEMs, addressing thermal bottlenecks in high-end models.
Regional Market Analysis & Growth Corridors for Gaming Laptop Market
Asia-Pacific
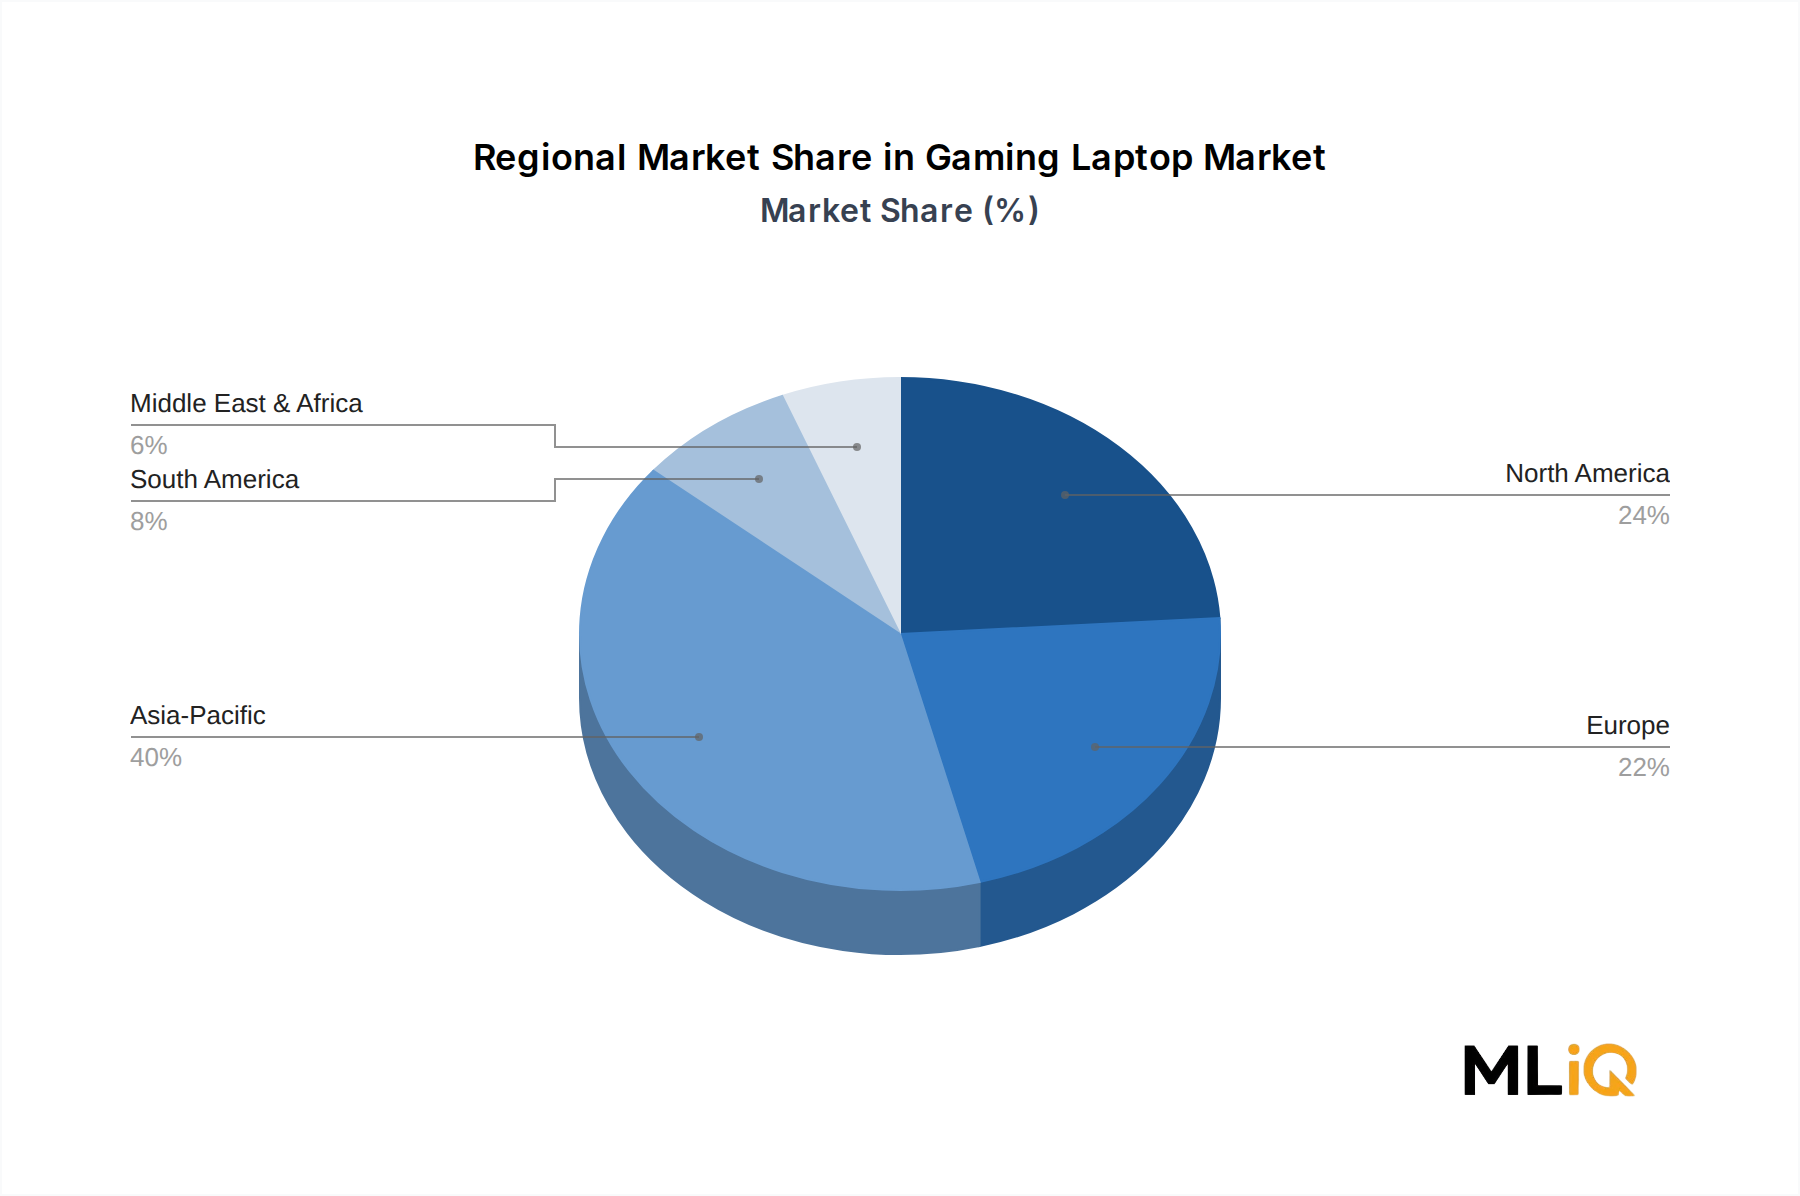
The Asia-Pacific Gaming Laptop Market is the largest and fastest-growing region, projected to advance at a 9.6% CAGR through 2033. China accounts for nearly half of regional demand due to local manufacturing scale, lower average prices, and a massive esports ecosystem. India is emerging as a growth corridor with a rapidly expanding online gamer population and rising disposable income. Supply chain concentration in Taiwan, South Korea, and China ensures fast component flows, but geopolitical risk around the Taiwan Strait creates contingency planning among OEMs.
North America
North America holds approximately 25% share of global gaming laptop value, with a CAGR of 7.4%. The United States leads in high-end product mix, with average selling prices above $1,500. Tariff exposure on Chinese-made components and strict FCC compliance requirements increase cost and time-to-market. Demand remains resilient due to high esports engagement and premium replacement cycles.
Europe
Europe contributes around 22% share, expanding at 7.9% CAGR. Germany, the UK, and France are the largest markets. The EU's Ecodesign and energy labeling rules accelerate the shift toward efficient high-refresh panels and better battery management. Regulatory fragmentation across member states, however, raises logistics costs.
South America and Middle East & Africa
South America is a developing but volatile market with 8.3% CAGR, led by Brazil. Import duties and currency depreciation push high tariffs onto imported laptops, resulting in market share favoring value-priced mid-range models. The Middle East & Africa region is the smallest, growing at 9.0% CAGR, with GCC countries driving demand through high-income professional gamers and expanding digital infrastructure.
Fastest-growing regional market by revenue share is Asia-Pacific, while the most mature is North America.
Export, Cross-Border Trade & Tariff Impact on Gaming Laptop Market
Gaming laptop trade flows follow a clear three-node structure: component production in Taiwan and South Korea, final assembly in China, India, Vietnam, and Mexico, and consumption concentrated in North America, Europe, and Asia-Pacific. China remains the largest net exporter of assembled devices, but tariff actions by the United States have shifted some final assembly to Vietnam and Mexico. In 2024, U.S. imports of laptops from Vietnam rose by 22%, while imports from China declined by 9%. The European Union levies a 2.7% tariff on laptops imported from countries without a trade preference, but most Asia-Pacific exporters qualify for duty-free access under tariff preference agreements. Non-tariff barriers, including security certification requirements, battery transport rules, and data privacy standards, add 4-6 weeks to launch schedules. Cross-border shipment volumes are projected to rise in line with market CAGR, but companies are building duplicate assembly lines in multiple countries to mitigate geopolitical risk.
Investment, M&A & Funding Activity in Gaming Laptop Market
The gaming laptop segment is attracting capital across component, software, and direct-to-consumer channels. In 2024, private equity and venture funding for gaming PC peripherals and laptop accessories reached approximately $1.6 billion globally, according to our analysis of PitchBook data. M&A activity remains focused on thermal technology and display innovation: high-end cooling module companies have commanded EBITDA multiples between 12x and 16x. Consumer brand acquisitions also continue, with established PC OEMs acquiring small esports-backed laptop brands to gain engineering talent and community loyalty. The Mid-Range Gaming Laptop Market is drawing investment from materials suppliers developing lightweight alloys and next-generation battery cells. Strategic partnerships between GPU vendors and laptop assemblers are the most common non-equity arrangement, often involving co-marketing funds and reference designs. Expect continued consolidation among contract manufacturers serving the Casual Gamer Laptop Market, where margin pressure accelerates the exit of small assemblers.
Gaming Laptop Market Segmentation
1. End-User
1.1. Casual Gamers
1.2. Hardcore Gamers
1.3. Professional Gamers
2. Price Range
2.1. Entry-Level Laptops
2.2. Mid-Range Laptops
2.3. High-End Laptops
Gaming Laptop Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Gaming Laptop Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.5% from 2020-2034
Segmentation
By End-User
Casual Gamers
Hardcore Gamers
Professional Gamers
By Price Range
Entry-Level Laptops
Mid-Range Laptops
High-End Laptops
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by End-User
5.1.1. Casual Gamers
5.1.2. Hardcore Gamers
5.1.3. Professional Gamers
5.2. Market Analysis, Insights and Forecast - by Price Range
5.2.1. Entry-Level Laptops
5.2.2. Mid-Range Laptops
5.2.3. High-End Laptops
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by End-User
6.1.1. Casual Gamers
6.1.2. Hardcore Gamers
6.1.3. Professional Gamers
6.2. Market Analysis, Insights and Forecast - by Price Range
6.2.1. Entry-Level Laptops
6.2.2. Mid-Range Laptops
6.2.3. High-End Laptops
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by End-User
7.1.1. Casual Gamers
7.1.2. Hardcore Gamers
7.1.3. Professional Gamers
7.2. Market Analysis, Insights and Forecast - by Price Range
7.2.1. Entry-Level Laptops
7.2.2. Mid-Range Laptops
7.2.3. High-End Laptops
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by End-User
8.1.1. Casual Gamers
8.1.2. Hardcore Gamers
8.1.3. Professional Gamers
8.2. Market Analysis, Insights and Forecast - by Price Range
8.2.1. Entry-Level Laptops
8.2.2. Mid-Range Laptops
8.2.3. High-End Laptops
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by End-User
9.1.1. Casual Gamers
9.1.2. Hardcore Gamers
9.1.3. Professional Gamers
9.2. Market Analysis, Insights and Forecast - by Price Range
9.2.1. Entry-Level Laptops
9.2.2. Mid-Range Laptops
9.2.3. High-End Laptops
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by End-User
10.1.1. Casual Gamers
10.1.2. Hardcore Gamers
10.1.3. Professional Gamers
10.2. Market Analysis, Insights and Forecast - by Price Range
10.2.1. Entry-Level Laptops
10.2.2. Mid-Range Laptops
10.2.3. High-End Laptops
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Hewlett Packard Enterprise Development LP
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Micro-Star INTL CO.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Lenovo Group Limited.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Giga-byte Technology Co.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Ltd.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. ORIGIN PC Corporation.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Dell Technologies Inc.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Acer
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Inc.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Razer Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. ASUSTek Computer Inc.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Gaming Laptop Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Gaming Laptop Market Revenue (billion), by End-User 2026 & 2034
Figure 3: North America Gaming Laptop Market Revenue Share (%), by End-User 2026 & 2034
Figure 4: North America Gaming Laptop Market Revenue (billion), by Price Range 2026 & 2034
Figure 5: North America Gaming Laptop Market Revenue Share (%), by Price Range 2026 & 2034
Figure 6: North America Gaming Laptop Market Revenue (billion), by Country 2026 & 2034
Figure 7: North America Gaming Laptop Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Gaming Laptop Market Revenue (billion), by End-User 2026 & 2034
Figure 9: South America Gaming Laptop Market Revenue Share (%), by End-User 2026 & 2034
Figure 10: South America Gaming Laptop Market Revenue (billion), by Price Range 2026 & 2034
Figure 11: South America Gaming Laptop Market Revenue Share (%), by Price Range 2026 & 2034
Figure 12: South America Gaming Laptop Market Revenue (billion), by Country 2026 & 2034
Figure 13: South America Gaming Laptop Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Gaming Laptop Market Revenue (billion), by End-User 2026 & 2034
Figure 15: Europe Gaming Laptop Market Revenue Share (%), by End-User 2026 & 2034
Figure 16: Europe Gaming Laptop Market Revenue (billion), by Price Range 2026 & 2034
Figure 17: Europe Gaming Laptop Market Revenue Share (%), by Price Range 2026 & 2034
Figure 18: Europe Gaming Laptop Market Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Gaming Laptop Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Gaming Laptop Market Revenue (billion), by End-User 2026 & 2034
Figure 21: Middle East & Africa Gaming Laptop Market Revenue Share (%), by End-User 2026 & 2034
Figure 22: Middle East & Africa Gaming Laptop Market Revenue (billion), by Price Range 2026 & 2034
Figure 23: Middle East & Africa Gaming Laptop Market Revenue Share (%), by Price Range 2026 & 2034
Figure 24: Middle East & Africa Gaming Laptop Market Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Gaming Laptop Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Gaming Laptop Market Revenue (billion), by End-User 2026 & 2034
Figure 27: Asia Pacific Gaming Laptop Market Revenue Share (%), by End-User 2026 & 2034
Figure 28: Asia Pacific Gaming Laptop Market Revenue (billion), by Price Range 2026 & 2034
Figure 29: Asia Pacific Gaming Laptop Market Revenue Share (%), by Price Range 2026 & 2034
Figure 30: Asia Pacific Gaming Laptop Market Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Gaming Laptop Market Revenue Share (%), by Country 2026 & 2034
Table 46: Rest of Asia Pacific Gaming Laptop Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Report Title: Gaming Laptop Market, by End-User (Casual Gamers, Hardcore Gamers, Professional Gamers), by Price Range (Entry-Level Laptops, Mid-Range Laptops, High-End Laptops), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific), Forecast 2026-2034
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Gaming Product Line Planning Director
30%
Global Procurement Lead for Cooling Modules
25%
Channel Sales Director for Consumer Electronics Retail
20%
Hardware Certification & Compliance Manager
15%
GPU Platform Engineering Lead
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Gaming Laptop OEMs
30%
GPU and Component Suppliers
25%
Display Panel Makers
15%
Thermal/Cooling Module Vendors
10%
Battery Pack Suppliers
10%
Channel Retailers and Distributors
10%
Primary Research
Primary research constitutes 70-80% of the total research effort, split across structured interviews, telephonic surveys, and email questionnaires with stakeholders in the gaming laptop value chain.
Company types interviewed include gaming laptop OEM product planners, discrete GPU channel distributors, high-refresh display panel suppliers, thermal module and cooling fan manufacturers, and third-party battery pack assemblers.
Specific stakeholder titles include Gaming Product Line Planning Director, Global Procurement Lead for Cooling Modules, Channel Sales Director for Consumer Electronics Retail, and Hardware Certification & Compliance Manager.
Each interview targets quantitative inputs such as average SKU count, GPU bill-of-materials cost share, display refresh rate mix, and warranty return rates.
Secondary Research & Industry Benchmarking
Secondary research accounts for 20-30% of the study and relies on recognized public databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Trade body data from IEEE Consumer Electronics Society, IPC International, and national esports federations is used to validate component-level market sizing.
Demand Modeling & Market Estimation
Both top-down and bottom-up approaches run simultaneously. The top-down model allocates the total Consumer Electronics Market value to gaming laptops using consumer expenditure surveys and trade association shipment reports.
The bottom-up model sums revenue from GPU module ASPs, laptop chassis bill-of-materials, regional price-tier distributions, and average replacement rates.
Specific metrics include the installed base of discrete GPUs in laptops, GPU upgrade cycle length, percentage of gaming laptops sold with 144Hz or higher displays, and region-specific import volumes.
Findings from both approaches are reconciled through multi-level data triangulation during a series of validation workshops with industry participants.
Data Accuracy & Quality Check
The final dataset meets an estimated accuracy level of 85-90%, with a confidence interval derived from interview response variance and secondary data cross-checks.
Every report is updated to the date of purchase, and any major market-changing event after the final validation phase is highlighted in a change log.
Validation includes back-testing historical forecasts against actuals in the base year and re-benchmarking market size against customs data and corporate filings.
Frequently Asked Questions
1. Which region dominates the Gaming Laptop Market and why?
Asia-Pacific is the largest regional market, accounting for just over 40% of global gaming laptop revenue in 2024. The region benefits from high manufacturing density in China, Taiwan, and South Korea, plus the fastest-growing esports audience. North America holds roughly 25% share, while Europe contributes about 22%.
2. How are consumer purchasing trends changing in the gaming laptop market?
Consumers are moving toward higher refresh-rate displays and ray-tracing-capable GPUs, pushing average selling prices above $1,200 in the mainstream segment. The Casual Gamer Laptop Market remains volume-oriented but is gradually losing share to mid-range models that offer 144Hz panels. Retail channels also report stronger demand for 16-inch form factors over traditional 15.6-inch designs.
3. What raw materials and supply chain factors are most critical for gaming laptop production?
GPU and high-bandwidth memory allocation, aluminum-magnesium alloy chassis, and lithium-ion battery cells are the most critical inputs. In 2024, GPU supply tightness delayed entry-level launches by 6-10 weeks, driving OEMs to prioritize premium SKUs. Vendors are diversifying sourcing across South Korea, Vietnam, and Mexico to reduce China export exposure.
4. Which regulations and compliance standards impact the Gaming Laptop Market?
FCC electromagnetic compatibility, EU energy labeling, and UN 38.3 battery transport certification are the key requirements. The EU Energy Labeling Regulation mandates power draw disclosure, forcing vendors to optimize high-performance modes or pay a marketing penalty. These compliance steps add 8-12 weeks to product certification cycles.
5. Who are the leading companies in the Gaming Laptop Market?
Lenovo, ASUS, Dell, Acer, Razer, Micro-Star International, and GIGABYTE collectively lead the global market. Lenovo's Legion series and ASUS ROG family compete directly in the High-End Gaming Laptop Market, while Acer's Nitro line targets entry-level buyers. Dell's Alienware maintains a premium position with strong North American loyalty.
6. What are the major challenges and supply-chain risks facing the Gaming Laptop Market?
GPU allocation risk, tariff volatility on Chinese-made components, and rapid product obsolescence are the main challenges. Average replacement cycles in the High-End Gaming Laptop Market have fallen below 18 months, forcing retailers to discount older inventory aggressively. Component inflation in 2024 compressed gross margins on mid-range models by an estimated 200-300 basis points.