Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Temperature Controlled System Market: 3.9% CAGR to USD 2.85 Bn by 2034
Temperature Controlled System Market
Temperature Controlled System Market: 3.9% CAGR to USD 2.85 Bn by 2034
Temperature Controlled System Market by Type (Open Loop, Closed Loop Control), by Application (Air conditioning, Water Heater, Refrigators, Others), by End User (Industrial Temperature Controlled System, Home Temperature Controlled System, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 6, 2026|Base Year : 2025|Pages : 320
Key Insights & Executive Summary: Temperature Controlled System Market
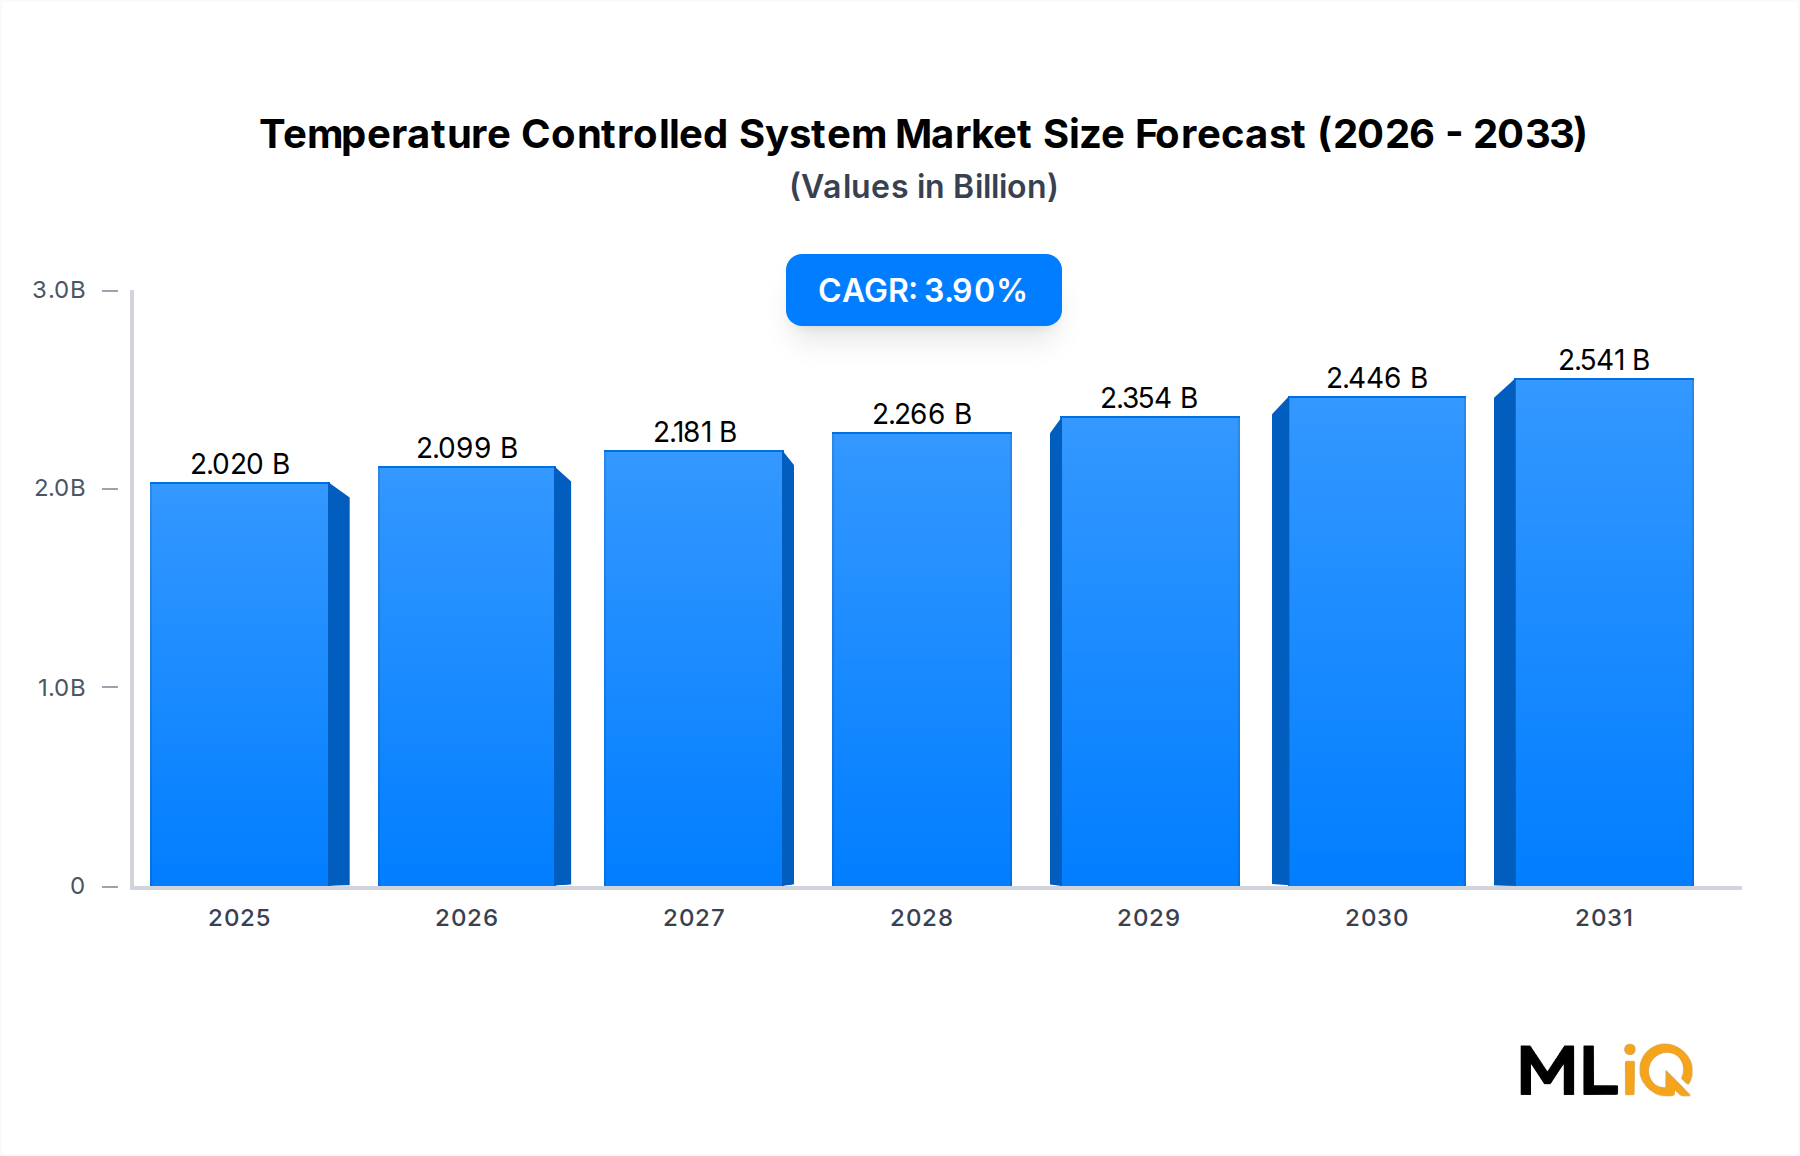
Temperature Controlled System Market Size (In Billion)
3.0B
2.0B
1.0B
0
2.020 B
2025
2.099 B
2026
2.181 B
2027
2.266 B
2028
2.354 B
2029
2.446 B
2030
2.541 B
2031
Market at a Glance
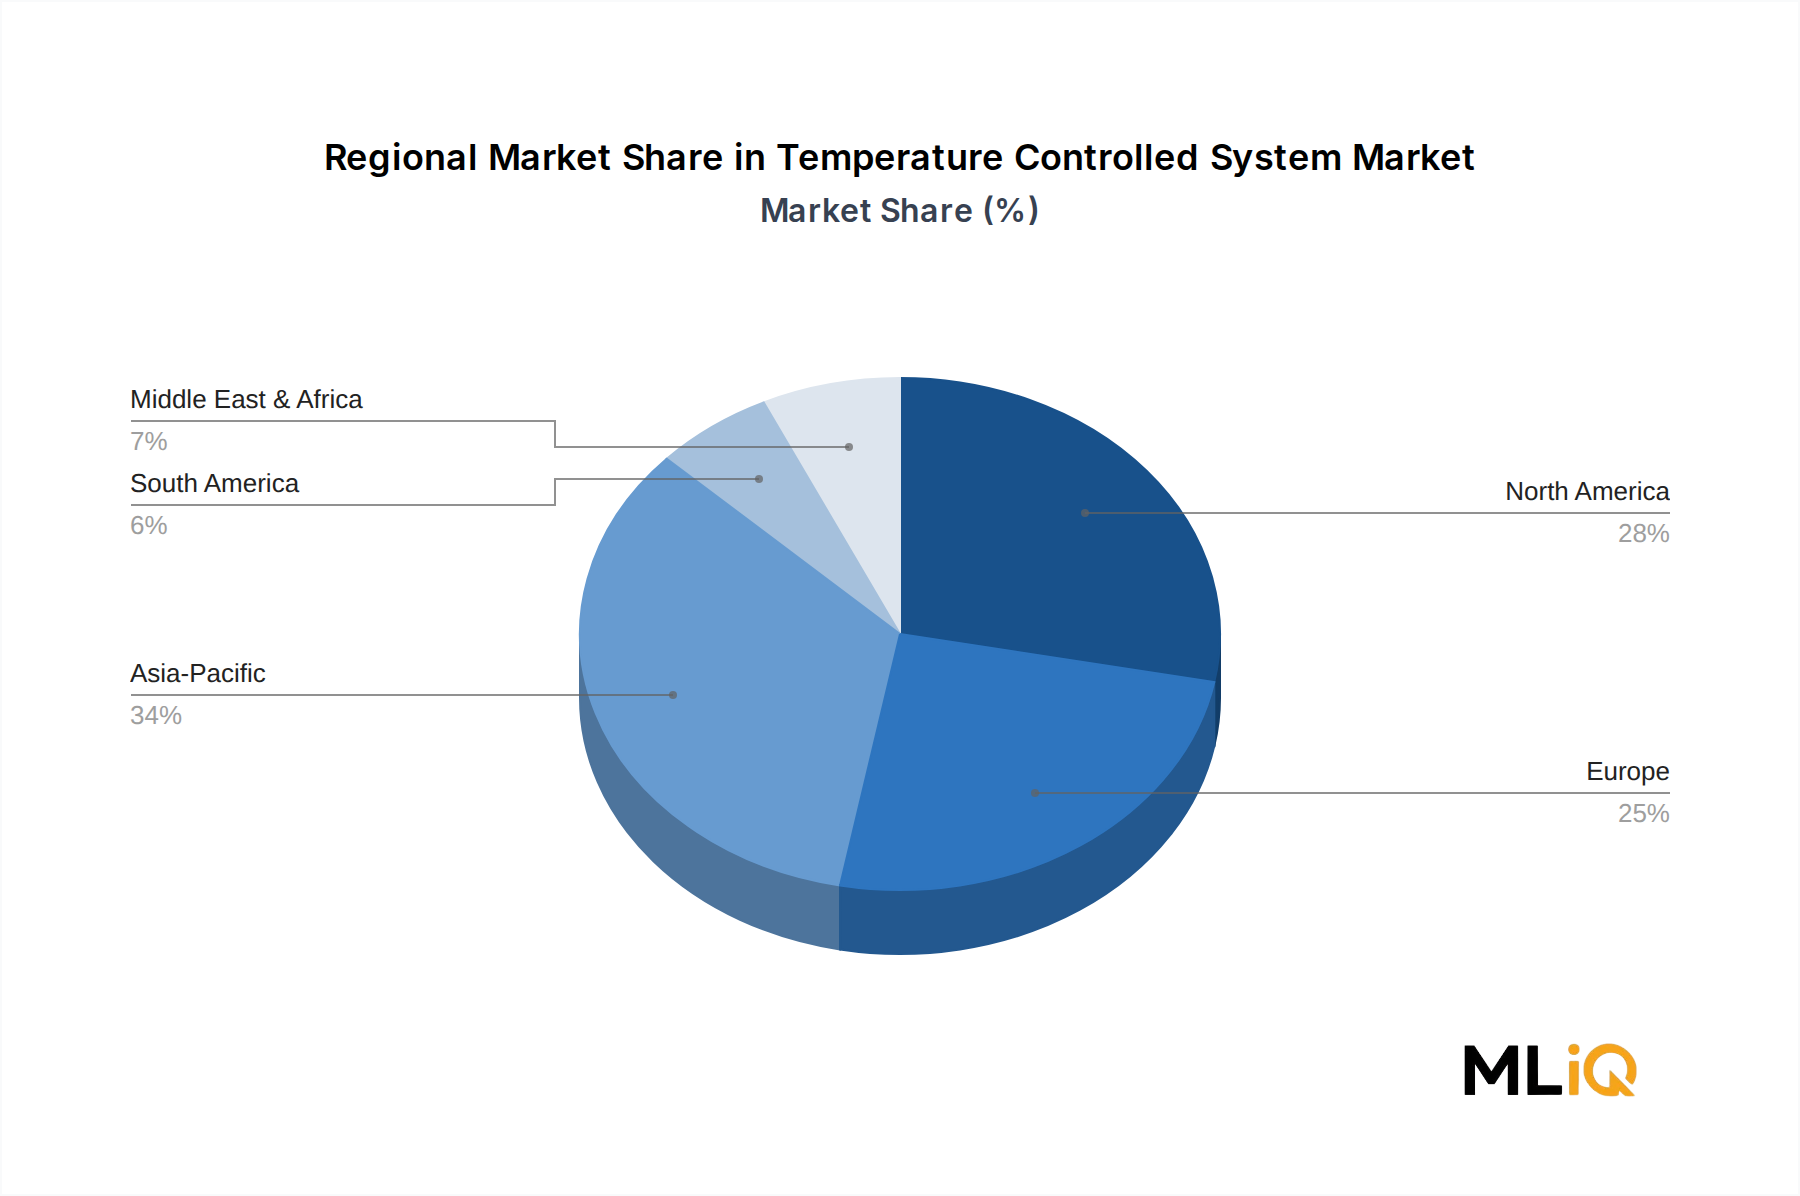
The Temperature Controlled System Market is projected to expand from USD 2.02 Billion in 2025 to USD 2.85 Billion by 2034 at a CAGR of 3.9%. Growth is not uniform across geographies. Asia-Pacific will capture roughly 34% of global revenue by 2034, supported by urbanization and industrial process electrification. North America remains a high-value market because of building energy retrofits and stricter refrigerant mandates enforced by agencies such as the U.S. Environmental Protection Agency. Europe’s growth path is shaped by F-gas phase-down schedules and the Energy Performance of Buildings Directive.
Macro-level incentives to replace analog controls include energy price volatility, grid stability requirements, and the availability of low-cost connected sensors. Closed-loop control now underpins most energy-efficient HVAC designs because it responds to real-time temperature, humidity, and occupancy signals. Open-loop systems are still installed where simplicity and first cost dominate, but their share in new projects is declining. Although the 3.9% CAGR appears moderate, the underlying mix is shifting decisively toward value-added software control, equipment retrofits, and subscription-enabled service models.
Several overlapping product markets shape the broader Temperature Controlled System Market. The Closed Loop Temperature Control Market holds the largest revenue pool, while open-loop devices are increasingly restricted to basic refrigeration and low-cost water heater applications. The HVAC System Market is moving toward variable refrigerant flow and intelligent zone controls, while the Air Conditioning System Market supports room-specific conditioning with inverter-driven compressors. The Digital Temperature Controller Market is expanding faster than equipment volumes because retrofits can be implemented without replacing compressors or chiller cores. The Temperature Control Devices Market, defined as sensing, signaling, and actuation components, benefits from a rising bill of materials for controls. The Smart Thermostat Market is migrating from premium housing into rental and light commercial properties where energy benchmarking rules apply.
From an application perspective, air conditioning accounts for the highest share of controlled temperature loads. The Home Temperature Control System Market remains the volume engine, but the Industrial Temperature Control System Market supplies more revenue per installed node and carries longer maintenance contracts. Water heater and refrigeration applications create stable replacement demand.
Market economics favor manufacturers that combine hardware reliability with digital service models. The presence of major controls vendors in flexible load management and predictive maintenance will determine whether the market’s monetization rate outpaces unit growth.
Segment Deep-Dive: Closed Loop Control Dominance in Temperature Controlled System Market
Segment Share and Revenue Mix
Closed Loop Control generated approximately 62% of global temperature control revenue in 2025, a share projected to reach 66% by 2030. Open-loop control remains a niche for frost guards, line-voltage thermostats, and simple water heater limiters, but closed-loop feedback now defines the premium core of the market. Service contracts attached to closed-loop control nodes extend lifetime value and create recurring revenue. In the Closed Loop Temperature Control Market, local proportional-integral-derivative (PID) controllers and distributed control loops are displacing single-stage electromechanical units.
Sub-Segment Dynamics: Open Loop vs. Closed Loop Control
Open Loop Control operates without measurement feedback. It is lower in component count and sufficient for processes where temperature tolerance is broad and load changes are predictable. Closed Loop Control adds sensors, comparators, actuators, and communication modules. The incremental hardware cost is roughly USD 15–40 per control point, yet the energy savings in building heating and cooling applications is often 12–18% annually. In industrial processes that require precise thermal profiles, closed-loop control becomes mandatory.
Applications Driving Revenue
The Air Conditioning System Market accounts for nearly half of controlled temperature system revenue, followed by refrigeration and water heating. Air conditioning efficiency standards, such as SEER thresholds in North America and seasonal efficiency requirements in Europe, force HVAC manufacturers to adopt variable-speed compressors and electronic expansion valves. Water heater applications are the main outlet for open-loop devices; closed-loop control penetrates heat pump water heaters and solar thermal buffering. Refrigeration systems, particularly in cold chain logistics, increasingly rely on closed-loop temperature control with data logging for regulatory audits.
Margin and Pricing Pressure
Closed Loop Control pricing has fallen 4–6% per year in mature segments because of semiconductor commoditization. Vendors offset pricing pressure by moving to value-added software, cloud monitoring, and cybersecurity services. The Digital Temperature Controller Market is growing faster than the broader category because users can add intelligence via retrofits without changing physical system footprints. The Temperature Control Devices Market also benefits from upgrades in sensor accuracy and communication protocol support. Gross margins at the component level vary from 24% to 35%, while integrated control panel providers typically operate at 35–45% margins due to design and commissioning content.
Primary Market Drivers & Growth Restraints in Temperature Controlled System Market
Market Drivers
Regulatory energy codes are the most consistent growth catalyst. The HVAC System Market is the largest end-user segment, and code-mandated controls upgrades ensure that efficiency is achieved in occupied buildings rather than only at part-load ratings. In the U.S., the Department of Energy’s energy conservation standards and state-level adoption of ASHRAE 90.1 require advanced economizing and demand-controlled ventilation. Europe’s revised Energy Performance of Buildings Directive similarly pushes building automation and control systems in non-residential buildings.
Operational complexity in process industries also raises demand. The Industrial Temperature Control System Market is expanding as semiconductor fabrication, pharmaceutical cold storage, and battery production require precise thermal stability. For example, lithium-ion electrode drying and curing processes often specify tolerance bands below ±1°C, making closed-loop control a production prerequisite.
Finally, the falling cost of sensors and microcontrollers removes the historical price barrier of adaptive control. A typical commercial temperature controller now integrates Wi-Fi or BACnet connectivity at less than USD 100, down from over USD 300 a decade ago. Demand response programs in the Energy Management System Market reward controllers that can shed load during peak grid events, creating an added payback stream.
Market Restraints
Supply chain concentration limits growth. Microcontrollers, current sensors, and specialized relays remain exposed to semiconductor allocation cycles, and lead times for industrial-grade components have only partially normalized. Raw material costs for copper, aluminum, and rare-earth magnets affect magnetic valve and compressor drive costs; a 10% copper price increase can raise controller module cost by 2–3%.
A fragmented installer base is another restraint. Newer systems require network architecture knowledge, and the shortage of commissioning engineers slows adoption in small commercial buildings. Interoperability concerns also cause buyers to remain with single-vendor control ecosystems, postponing price-driven switches.
The Temperature Control Devices Market faces margin pressure from commoditized components; however, integrated software reduces the risk of pure hardware substitution. Water heater and refrigeration replacements often follow a 10–15 year cycle, dampening short-term upsides.
Competitive Ecosystem & Key Vendor Profiles: Temperature Controlled System Market
Competitive differentiation concentrates on installed base, software ecosystem, and cybersecurity certifications. The main vendors are:
Delta Controls Inc.: Builds open-protocol building automation controllers and focuses on native BACnet integration for HVAC terminal units.
Siemens AG: Operates one of the broadest temperature control portfolios, ranging from room thermostats to industrial process controllers, with cloud based building management services.
Ingersoll Rand: Provides compressed air and temperature management systems for industrial facilities, especially critical process cooling.
LG Electronics Inc.: Gains share through variable refrigerant flow systems and residential smart controls embedded in HVAC equipment.
Honeywell International Inc.: Leads in connected thermostat and controller software, with strong positions in cybersecurity and energy analytics.
Daikin Industries Ltd.: Uses vertically integrated compressor, refrigerant, and control development to optimize air conditioning system efficiency.
Mitsubishi Electric Corporation: Specializes in high-performance heat pump controls and building energy management in Asia-Pacific.
Schneider Electric SE: Focuses on interoperable IoT architecture, edge control, and power management for temperature control in buildings and industrial sites.
Johnson Controls International PLC: Provides large-scale chiller plant optimization and open integration platforms for commercial real estate.
Emerson Electric Co.: Targets process industries with sophisticated temperature transmitters and valve positioners where reliability and calibration accuracy matter.
Carrier Global Corporation: Integrates controls with refrigeration and heating equipment, concentrating on cold chain and digital service models.
Strategic Milestones & Recent Developments in Temperature Controlled System Market
Jan 2024: Carrier Global Corporation closed its acquisition of Viessmann Climate Solutions, expanding residential heat pump controls and digital maintenance capabilities in Europe.
Mar 2024: Schneider Electric SE updated its EcoStruxure Building portfolio with AI-assisted temperature setpoint optimization and additional cybersecurity layers.
Jun 2024: Honeywell International Inc. released a new line of BACnet-native wall controllers designed for retrofit projects in offices and healthcare facilities.
Sep 2024: Emerson Electric Co. introduced a wireless temperature transmitter family for hazardous industrial zones, easing installation in existing process plants.
Nov 2024: Johnson Controls International PLC announced a cloud platform for chiller plant remote monitoring, pairing native temperature control with asset performance analytics.
Feb 2025: Daikin Industries Ltd. began rollout of an intelligent zone control algorithm for variable refrigerant flow heat pumps in European markets.
Apr 2025: Siemens AG integrated its building control platform with digital twin models to simulate thermal comfort scenarios before deployment.
These milestones show that growth is being captured through software and services rather than commoditized controller units.
Regional Market Analysis & Growth Corridors for Temperature Controlled System Market
North America
North America contributes about 28% of global revenue, with a mature replacement market and a CAGR near 2.4%. Energy efficiency regulation, especially Title 24 in California and ENERGY STAR program requirements, speeds up thermostat and controller upgrades. The U.S. remains the single largest country market, but Canada shows faster growth due to heat pump retrofits and carbon pricing.
Europe
Europe represents roughly 25% of revenue and grows at 3.1%. The F-gas regulation timeline and the Energy Performance of Buildings Directive create binding targets for building automation. Germany and the United Kingdom lead in chiller plant optimization and district heating controls. The Nordics exhibit higher penetration of smart heat pump controllers, while Southern Europe benefits from air conditioning installations in commercial buildings.
Asia-Pacific
Asia-Pacific is the fastest-growing and largest regional market, with around 34% share and a CAGR of 5.2%. China drives volume through export-oriented appliance manufacturing and commercial cooling construction. India’s urbanization increases demand for packaged air conditioners and refrigeration controls. ASEAN nations are expanding cold chain infrastructure, raising demand for closed-loop refrigeration controllers.
South America and Middle East & Africa
South America contributes 6% of revenue, with most demand from Brazil’s food and beverage processing and retail refrigeration. Middle East & Africa contributes 7%, boosted by district cooling and process cooling in GCC data centers. Together, LAMEA is not the largest scale but has higher percentage growth in data center cooling and pharmaceutical cold storage. The fastest growth corridor remains Southeast Asia and the Gulf, where temperature control is necessary for year-round process reliability.
Customer Segmentation & Buying Behavior in Temperature Controlled System Market
Residential and Home Users
The Home Temperature Control System Market is the largest by unit volume, driven by renovations, heating/cooling replacements, and new housing construction. Homeowners rarely evaluate control theory; instead, purchase decisions depend on smartphone compatibility, energy saving claims, and installation cost. Smart Thermostat Market research shows that retrofit adoption is strongest among households with heat pumps and time-of-use electricity tariffs. Early adopters in single-family housing are about twice as willing to pay for an energy dashboard than owners of non-communicating equipment.
Industrial and Commercial Buyers
The Industrial Temperature Control System Market is concentrated among buyers who treat temperature as a process variable tied to product quality. Decision-making units include plant engineers, maintenance managers, procurement, and control system specialists. These buyers ask for mean time between failures, calibration intervals, spare part availability, and multi-vendor interoperability. Price elasticity is lower in regulated industries, but higher for generic storage and comfort heating.
Procurement Channels and Decision Factors
Value-added distributors and system integrators influence a majority of commercial and industrial purchases. Recent purchasing cycles show stronger demand for control-as-a-service contracts, where customers pay per monitored point and avoid upfront software licenses. Preferred product attributes include open APIs, cybersecurity certification, and remote commissioning. The share of digital procurement has also increased; end users now compare controller specifications online before requesting installation quotes.
Investment, M&A & Funding Activity in Temperature Controlled System Market
Investment activity is shifting from hardware scale-ups to analytics and control software. In the past two years, private equity investors have consolidated regional HVAC controls distributors and service firms, while strategic acquirers purchased software startups that can monetize temperature data. Notable examples include Carrier’s 2024 acquisition of Viessmann Climate Solutions and Johnson Controls’ investments in chiller optimization platforms.
Venture capital interest is strongest in smart thermostat analytics, fault detection and diagnostics, battery-powered wireless sensors, and cold-chain IoT monitoring. Across 2023 and 2024, disclosed funding rounds in connected thermostat and cold chain monitoring software exceeded USD 1.2 Billion globally, according to aggregated public funding records. High-growth sub-segments attracting capital include cloud-based temperature compliance reporting for pharmaceutical logistics and AI-based setpoint optimization for retail buildings. Strategic acquirers prefer companies with recurring revenue and installed device fleets because they create cross-sell paths into HVAC maintenance contracts. Expect the controls segment of the temperature controlled systems value chain to continue receiving outsized investment relative to basic thermostatic hardware.
Temperature Controlled System Market Segmentation
1. Type
1.1. Open Loop
1.2. Closed Loop Control
2. Application
2.1. Air conditioning
2.2. Water Heater
2.3. Refrigators
2.4. Others
3. End User
3.1. Industrial Temperature Controlled System
3.2. Home Temperature Controlled System
3.3. Others
Temperature Controlled System Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Temperature Controlled System Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.9% from 2020-2034
Segmentation
By Type
Open Loop
Closed Loop Control
By Application
Air conditioning
Water Heater
Refrigators
Others
By End User
Industrial Temperature Controlled System
Home Temperature Controlled System
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Open Loop
5.1.2. Closed Loop Control
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Air conditioning
5.2.2. Water Heater
5.2.3. Refrigators
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by End User
5.3.1. Industrial Temperature Controlled System
5.3.2. Home Temperature Controlled System
5.3.3. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Open Loop
6.1.2. Closed Loop Control
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Air conditioning
6.2.2. Water Heater
6.2.3. Refrigators
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by End User
6.3.1. Industrial Temperature Controlled System
6.3.2. Home Temperature Controlled System
6.3.3. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Open Loop
7.1.2. Closed Loop Control
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Air conditioning
7.2.2. Water Heater
7.2.3. Refrigators
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by End User
7.3.1. Industrial Temperature Controlled System
7.3.2. Home Temperature Controlled System
7.3.3. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Open Loop
8.1.2. Closed Loop Control
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Air conditioning
8.2.2. Water Heater
8.2.3. Refrigators
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by End User
8.3.1. Industrial Temperature Controlled System
8.3.2. Home Temperature Controlled System
8.3.3. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Open Loop
9.1.2. Closed Loop Control
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Air conditioning
9.2.2. Water Heater
9.2.3. Refrigators
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by End User
9.3.1. Industrial Temperature Controlled System
9.3.2. Home Temperature Controlled System
9.3.3. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Open Loop
10.1.2. Closed Loop Control
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Air conditioning
10.2.2. Water Heater
10.2.3. Refrigators
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by End User
10.3.1. Industrial Temperature Controlled System
10.3.2. Home Temperature Controlled System
10.3.3. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Delta Controls Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Siemens AG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Ingersoll Rand
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. LG Electronics Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Honeywell International Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Daikin Industries
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Ltd.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Mitsubishi Electric Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Schneider Electric SE
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Johnson Controls International PLC
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Emerson Electric Co.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Carrier Global Corporation
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Temperature Controlled System Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Temperature Controlled System Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Temperature Controlled System Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Temperature Controlled System Market Revenue (billion), by Application 2026 & 2034
Figure 5: North America Temperature Controlled System Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Temperature Controlled System Market Revenue (billion), by End User 2026 & 2034
Figure 7: North America Temperature Controlled System Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Temperature Controlled System Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Temperature Controlled System Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Temperature Controlled System Market Revenue (billion), by Type 2026 & 2034
Figure 11: South America Temperature Controlled System Market Revenue Share (%), by Type 2026 & 2034
Figure 12: South America Temperature Controlled System Market Revenue (billion), by Application 2026 & 2034
Figure 13: South America Temperature Controlled System Market Revenue Share (%), by Application 2026 & 2034
Figure 14: South America Temperature Controlled System Market Revenue (billion), by End User 2026 & 2034
Figure 15: South America Temperature Controlled System Market Revenue Share (%), by End User 2026 & 2034
Figure 16: South America Temperature Controlled System Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Temperature Controlled System Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Temperature Controlled System Market Revenue (billion), by Type 2026 & 2034
Figure 19: Europe Temperature Controlled System Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Europe Temperature Controlled System Market Revenue (billion), by Application 2026 & 2034
Figure 21: Europe Temperature Controlled System Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe Temperature Controlled System Market Revenue (billion), by End User 2026 & 2034
Figure 23: Europe Temperature Controlled System Market Revenue Share (%), by End User 2026 & 2034
Figure 24: Europe Temperature Controlled System Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Temperature Controlled System Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Temperature Controlled System Market Revenue (billion), by Type 2026 & 2034
Figure 27: Middle East & Africa Temperature Controlled System Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Middle East & Africa Temperature Controlled System Market Revenue (billion), by Application 2026 & 2034
Figure 29: Middle East & Africa Temperature Controlled System Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Middle East & Africa Temperature Controlled System Market Revenue (billion), by End User 2026 & 2034
Figure 31: Middle East & Africa Temperature Controlled System Market Revenue Share (%), by End User 2026 & 2034
Figure 32: Middle East & Africa Temperature Controlled System Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Temperature Controlled System Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Temperature Controlled System Market Revenue (billion), by Type 2026 & 2034
Figure 35: Asia Pacific Temperature Controlled System Market Revenue Share (%), by Type 2026 & 2034
Figure 36: Asia Pacific Temperature Controlled System Market Revenue (billion), by Application 2026 & 2034
Figure 37: Asia Pacific Temperature Controlled System Market Revenue Share (%), by Application 2026 & 2034
Figure 38: Asia Pacific Temperature Controlled System Market Revenue (billion), by End User 2026 & 2034
Figure 39: Asia Pacific Temperature Controlled System Market Revenue Share (%), by End User 2026 & 2034
Figure 40: Asia Pacific Temperature Controlled System Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Temperature Controlled System Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Temperature Controlled System Market Revenue billion Forecast, by Type 2020 & 2034
Table 2: Temperature Controlled System Market Revenue billion Forecast, by Application 2020 & 2034
Table 3: Temperature Controlled System Market Revenue billion Forecast, by End User 2020 & 2034
Table 4: Temperature Controlled System Market Revenue billion Forecast, by Region 2020 & 2034
Table 5: North America Temperature Controlled System Market Revenue billion Forecast, by Type 2020 & 2034
Table 6: North America Temperature Controlled System Market Revenue billion Forecast, by Application 2020 & 2034
Table 7: North America Temperature Controlled System Market Revenue billion Forecast, by End User 2020 & 2034
Table 8: North America Temperature Controlled System Market Revenue billion Forecast, by Country 2020 & 2034
Table 9: United States Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 10: Canada Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: South America Temperature Controlled System Market Revenue billion Forecast, by Type 2020 & 2034
Table 13: South America Temperature Controlled System Market Revenue billion Forecast, by Application 2020 & 2034
Table 14: South America Temperature Controlled System Market Revenue billion Forecast, by End User 2020 & 2034
Table 15: South America Temperature Controlled System Market Revenue billion Forecast, by Country 2020 & 2034
Table 16: Brazil Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: Argentina Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Europe Temperature Controlled System Market Revenue billion Forecast, by Type 2020 & 2034
Table 20: Europe Temperature Controlled System Market Revenue billion Forecast, by Application 2020 & 2034
Table 21: Europe Temperature Controlled System Market Revenue billion Forecast, by End User 2020 & 2034
Table 22: Europe Temperature Controlled System Market Revenue billion Forecast, by Country 2020 & 2034
Table 23: United Kingdom Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Germany Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: France Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Italy Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Spain Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Russia Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: Benelux Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Nordics Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Temperature Controlled System Market Revenue billion Forecast, by Type 2020 & 2034
Table 33: Middle East & Africa Temperature Controlled System Market Revenue billion Forecast, by Application 2020 & 2034
Table 34: Middle East & Africa Temperature Controlled System Market Revenue billion Forecast, by End User 2020 & 2034
Table 35: Middle East & Africa Temperature Controlled System Market Revenue billion Forecast, by Country 2020 & 2034
Table 36: Turkey Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Israel Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: GCC Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: North Africa Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: South Africa Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Temperature Controlled System Market Revenue billion Forecast, by Type 2020 & 2034
Table 43: Asia Pacific Temperature Controlled System Market Revenue billion Forecast, by Application 2020 & 2034
Table 44: Asia Pacific Temperature Controlled System Market Revenue billion Forecast, by End User 2020 & 2034
Table 45: Asia Pacific Temperature Controlled System Market Revenue billion Forecast, by Country 2020 & 2034
Table 46: China Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: India Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: Japan Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: South Korea Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: ASEAN Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Oceania Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Temperature Controlled System Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Temperature Controlled System Market, by Type (Open Loop, Closed Loop Control), by Application (Air conditioning, Water Heater, Refrigators, Others), by End User (Industrial Temperature Controlled System, Home Temperature Controlled System, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific), Forecast 2026-2034
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Controls Product Managers
30%
Energy Procurement Leads
25%
Refrigeration System Engineers
25%
Corporate Development Executives
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Closed-loop controller OEMs
35%
Temperature sensor and actuator suppliers
25%
HVAC equipment manufacturers
25%
System integrators and distributors
15%
Primary Research
A 70–80% primary research share was used. Analysts conducted more than 140 structured interviews and 35 validation calls with functional leaders directly involved in temperature control specification and procurement.
Interviewee job titles included closed-loop controller product line managers, HVAC controls procurement leads at large facility owners, industrial refrigeration system engineers, and residential controls category managers.
Company types spanned thermocouple and sensor suppliers, OEM controller manufacturers, compressor drive vendors, chiller system integrators, and smart thermostat software providers.
Primary data collected included product price points, order volumes, project win/loss reasons, retrofit cycle length, and expected compliance timing.
Secondary Research & Industry Benchmarking
A 20–30% secondary research layer drew on Bloomberg, Factiva, Hoovers, and PitchBook, with company filings, earnings call transcripts, patent records, and trade publications.
Regulatory and association sources included the U.S. Department of Energy (DOE), the International Energy Agency (IEA), ASHRAE (ASHRAE), and the Air-Conditioning, Heating, and Refrigeration Institute (AHRI).
Secondary data were benchmarked against equipment shipment registries, energy code compliance databases, and utility demand-side program records.
Demand Modeling & Market Estimation
Bottom-up valuation used: number of installed closed-loop control points per commercial building, annual HVAC control retrofit rates by region, average controller price by communication protocol, and sensor replacement frequency in process industries.
Top-down validation used: national HVAC equipment production values, electricity consumption by cooling and heating end use, and construction spending by building category.
Both methods were reconciled through multi-level data triangulation. Discrepancies beyond 5% triggered additional interviews and a revised model iteration.
The final forecast period covers 2026–2034, grown from the 2025 base year estimate.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy ranges between 85% and 90%, validated by reconciliation with primary order data and secondary shipment reports.
Every report is updated to the date of purchase, including recent M&A announcements, regulatory compliance deadlines, and quarterly earnings adjustments.
Analysts re-ran the model when any single vendor changed market share projections by more than 0.5 percentage points.
Frequently Asked Questions
1. How do raw material sourcing and supply chain risks affect Temperature Controlled System Market pricing?
Suppliers of microcontrollers, insulated gate bipolar transistors, current sensors, and rare-earth magnets account for a meaningful share of controller bill of materials. Semiconductor allocation and copper/aluminum price swings can delay deliveries by 8-20 weeks and shift quotes upward. Vendors reduce risk by maintaining multi-region supply contracts and designing substitutes for magnet-based actuators.
2. What are the main barriers to entry in the Temperature Controlled System Market?
Certification complexity and software development costs create the highest moats. New entrants need UL, CE, ENERGY STAR, and increasingly cybersecurity labels such as UL 2900, with combined validation timelines of 12-18 months. An established vendor like Honeywell or Siemens also defends share through proprietary building integration libraries and installed service networks.
3. Which segment and application lead product demand in temperature control?
Closed Loop Control accounts for roughly 62% of revenue and is the dominant type. By application, air conditioning is the largest sub-category, followed by refrigeration and water heating; the Air Conditioning System Market alone will absorb more than 40% of newly installed control points over the forecast period.
4. Who are the leading vendors in the temperature controlled system industry?
Honeywell International Inc., Siemens AG, Johnson Controls International PLC, Daikin Industries Ltd., Schneider Electric SE, and Mitsubishi Electric Corporation are the largest suppliers. The top five control vendors together hold around 45-50% of global revenue, though the fragmented residential segment sustains many local brands.
5. How have buyer behavior and purchasing preferences changed in recent years?
Buyers avoid closed, single-vendor ecosystems and prefer open APIs, local communication protocols, and cloud optionality. Energy price inflation has increased willingness to pay for smart thermostats; roughly two-thirds of North American respondents in recent surveys want remote diagnostics and usage alerts included as baseline features.
6. What investment and M&A activity is occurring in temperature control technology?
Strategic buyers are acquiring analytics and digitally connected control startups more than hardware makers. Carrier Global’s acquisition of Viessmann Climate Solutions in January 2024 and Emerson Electric’s expanding wireless instrumentation portfolio illustrate this pattern. Disclosed funding for cloud-based temperature compliance and smart thermostat software exceeded USD 1.2 billion over 2023-2024, concentrated in cold chain and fault detection analytics.