Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Commercial Building Automation Market CAGR 9.9% to 2033
Commercial Building Automation Market
Commercial Building Automation Market CAGR 9.9% to 2033
Commercial Building Automation Market by Product Type (HVAC, Building Management Systems, Security and Access Control Systems, Energy Management Systems, Lighting Management Systems), by Enterprise Size (SMALL AND MEDIUM ENTERPRISES, LARGE ENTERPRISES), by Communication Technology (Wired Technology, Wireless Technology), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 12, 2026|Base Year : 2025|Pages : 0
Key Insights & Executive Summary: Commercial Building Automation Market
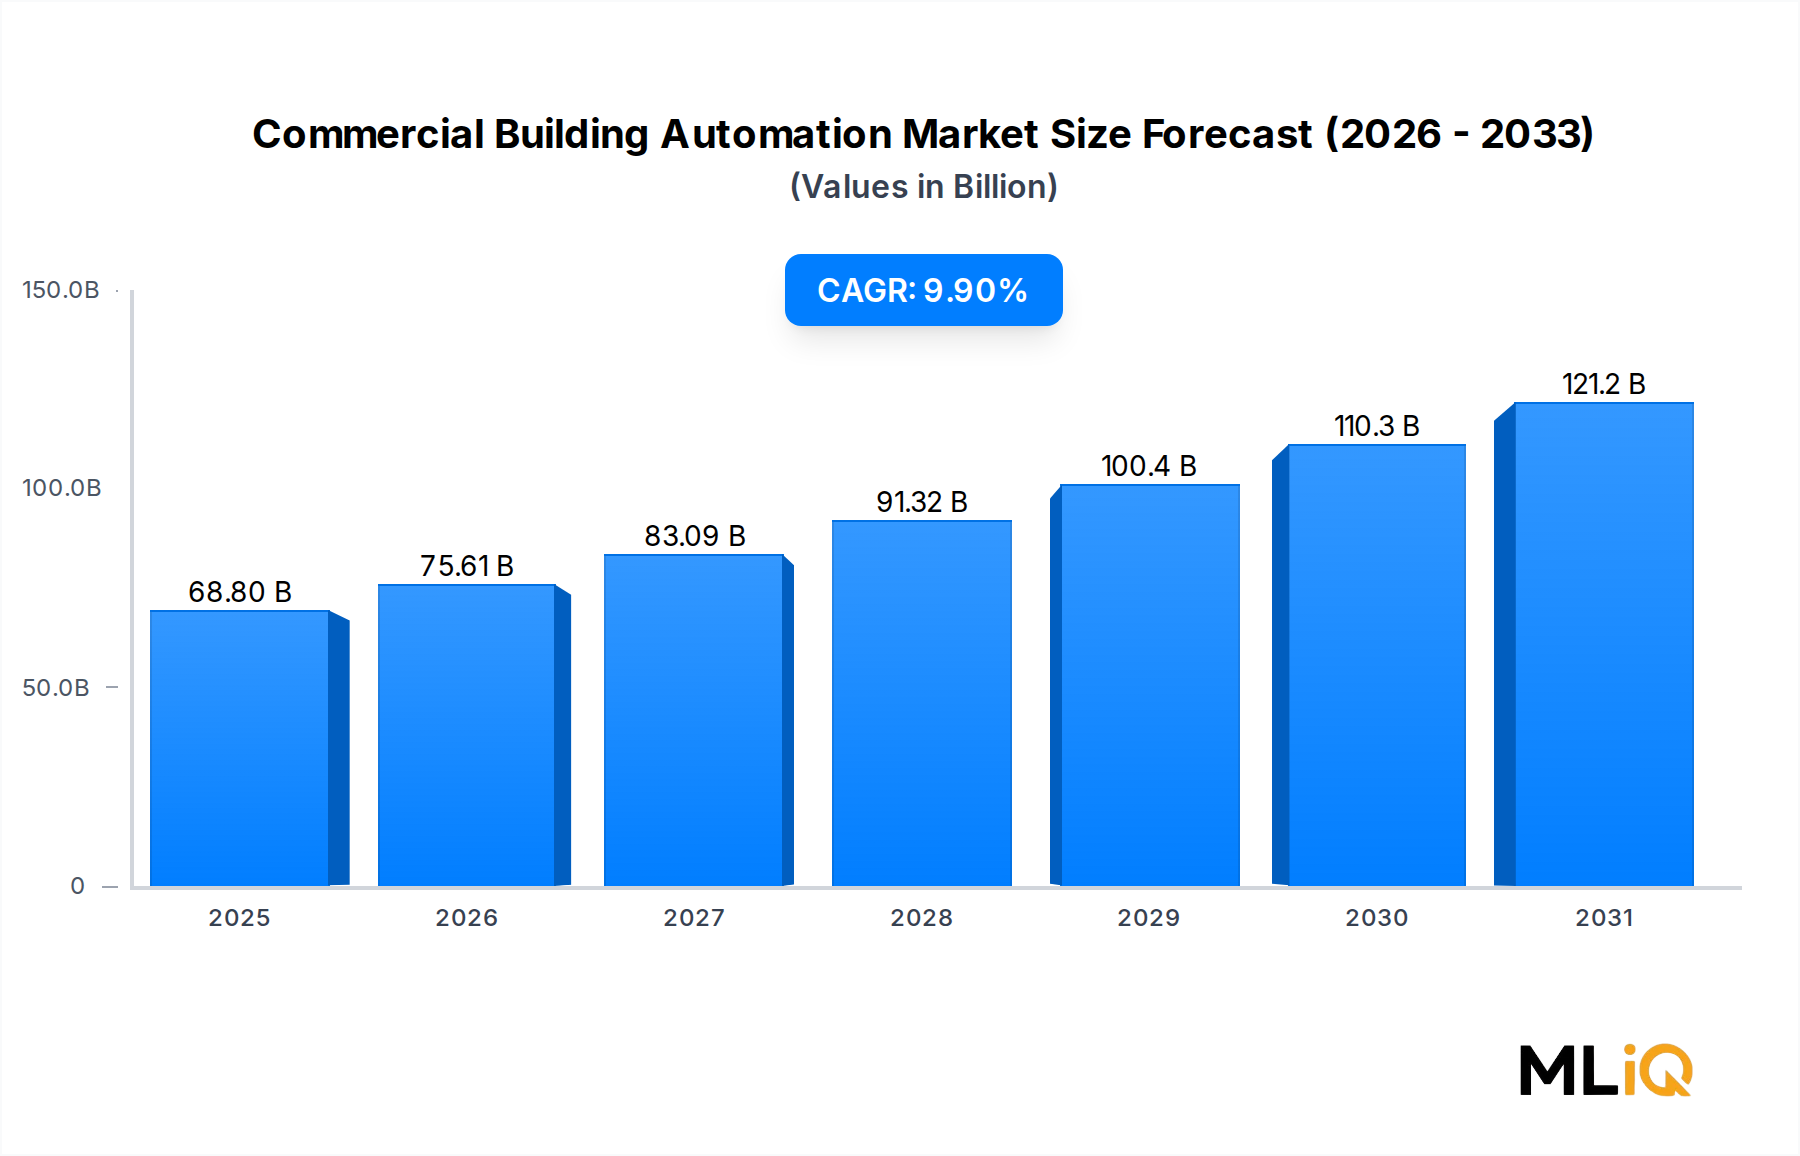
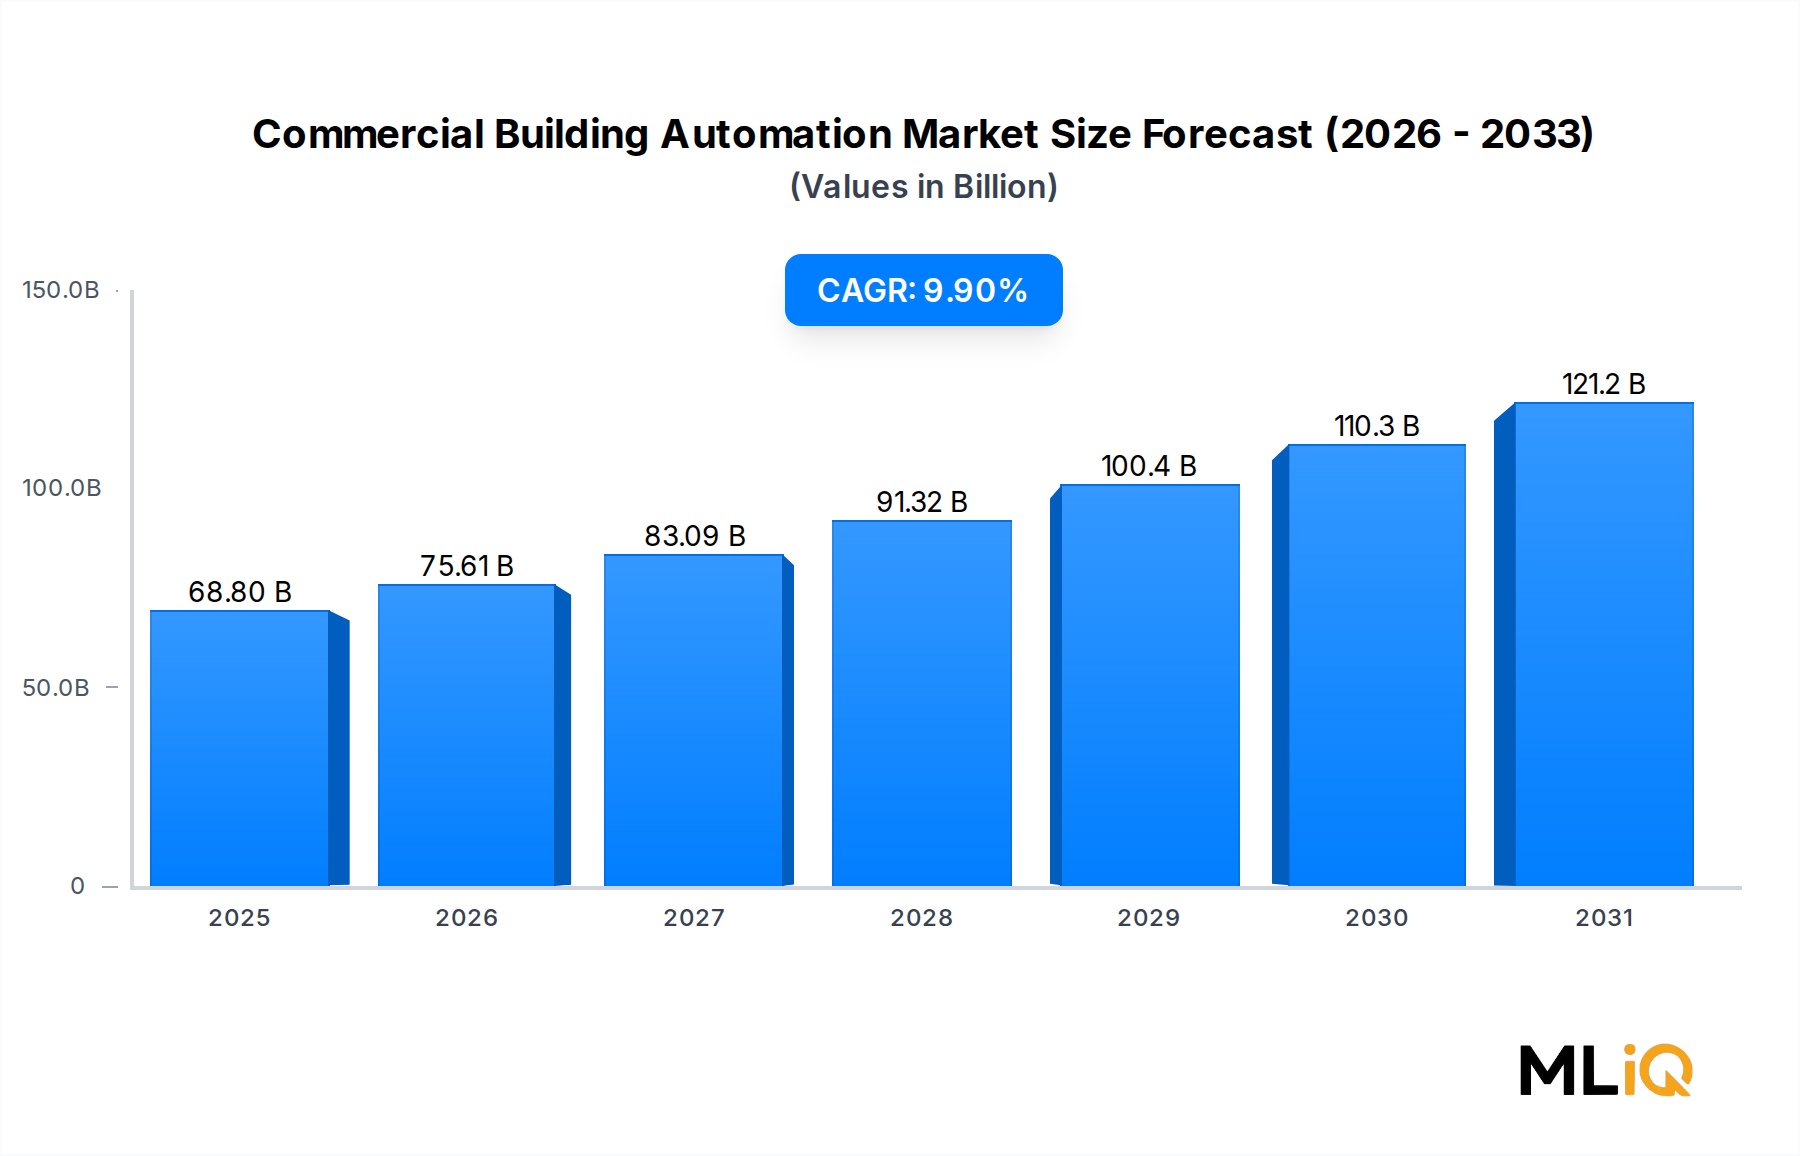
The global Commercial Building Automation Market reached USD 62.6 billion in 2024 and is forecast to hit USD 146.3 billion by 2033, a 9.9% CAGR. Growth is not evenly distributed: software, cloud analytics, and wireless retrofits expand faster than hardware controllers, while new construction in Asia-Pacific adds volume. The HVAC Controls Market remains the largest hardware category by units, driven by decarbonization mandates and refrigerant transitions.
Commercial Building Automation Market Size (In Billion)
150.0B
100.0B
50.0B
0
68.80 B
2025
75.61 B
2026
83.09 B
2027
91.32 B
2028
100.4 B
2029
110.3 B
2030
121.2 B
2031
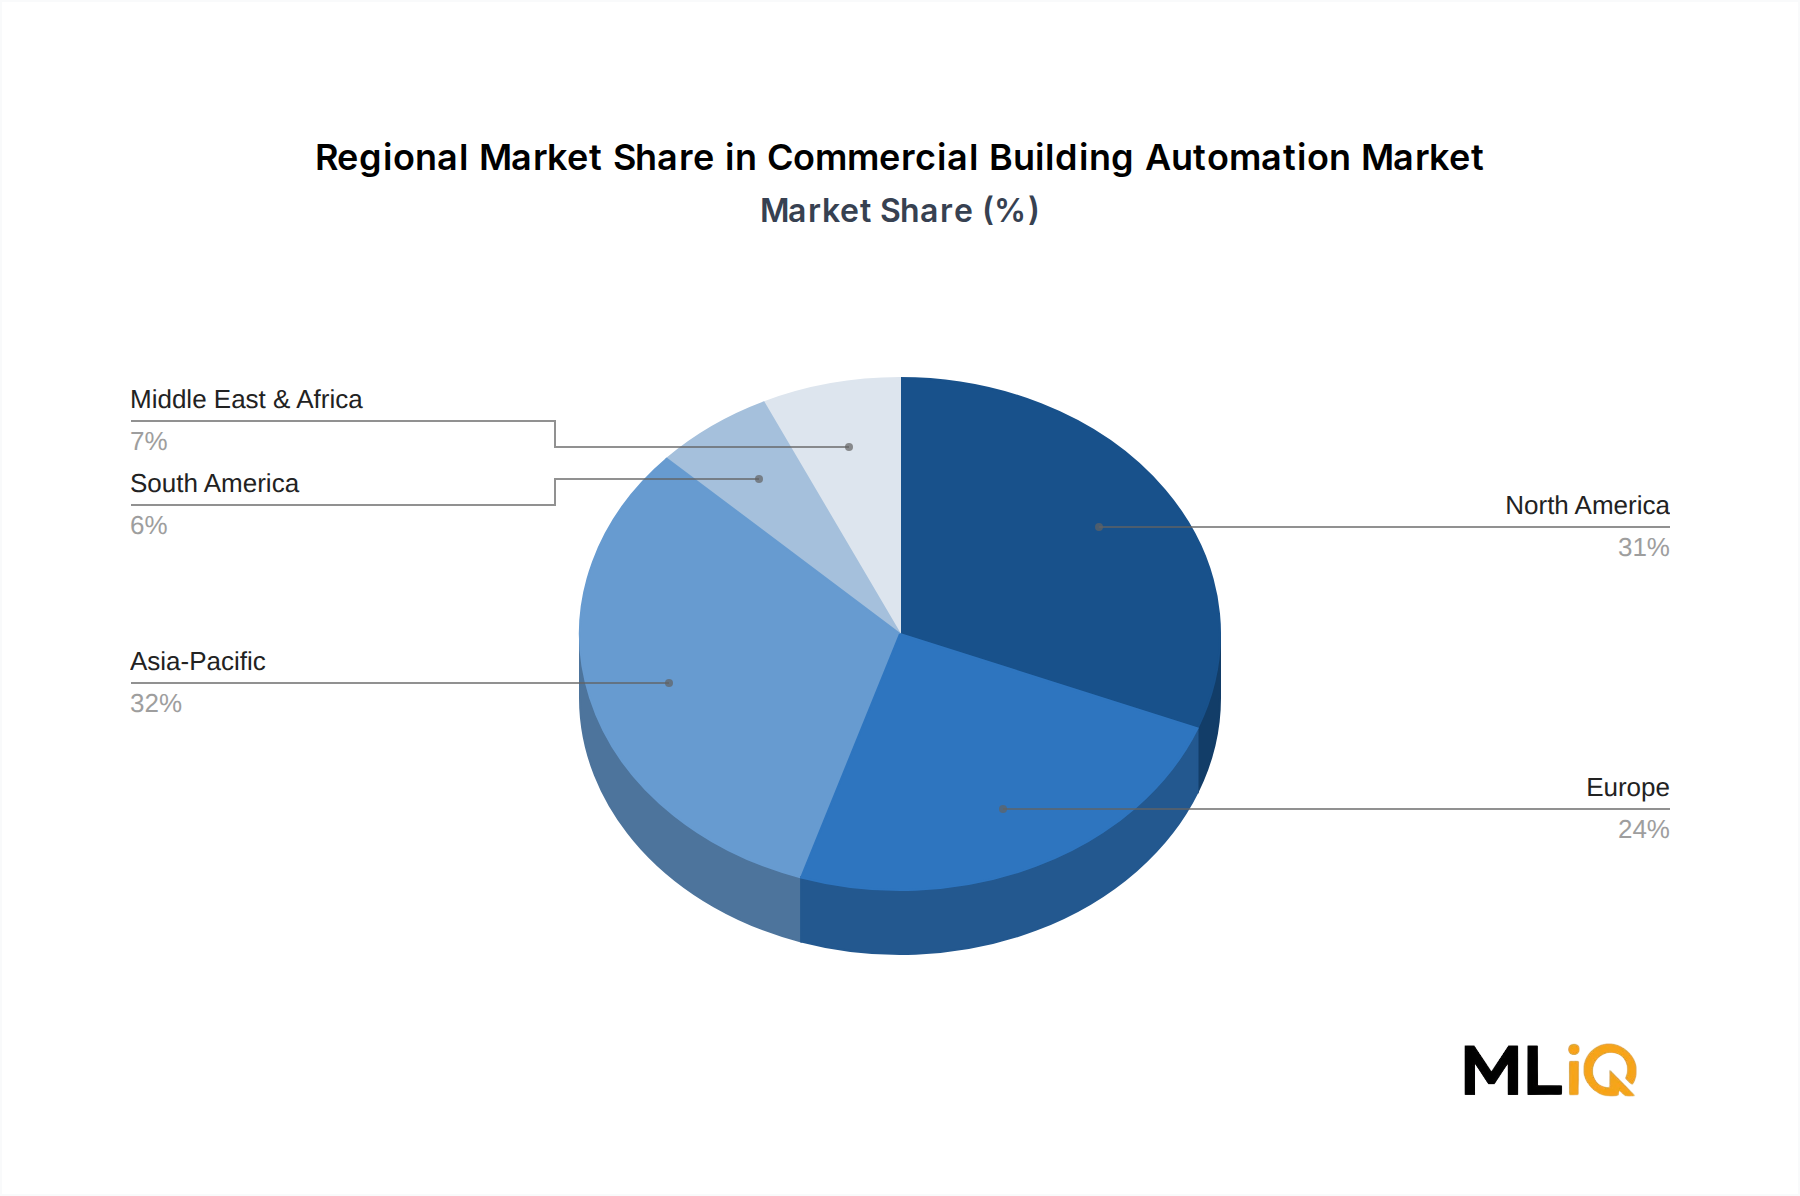
North America and Europe account for roughly 55% of installed value but face moderate growth due to mature building stock.
Asia-Pacific is the fastest-growing region at an estimated 11.2% CAGR, led by China, India, and ASEAN data center and commercial real estate pipelines.
Energy management and security integration are shifting from standalone systems to unified building operating platforms, raising average project value by 8-12%.
Retrofit activity represents about 60% of 2024 demand, as owners seek quick payback on lighting, HVAC, and submetering upgrades.
The market's mid-term trajectory depends on three factors: interest rates affecting capex cycles, cybersecurity regulations for connected devices, and the availability of skilled systems integrators. Where local codes mandate automated demand response, adoption accelerates by 1.5-2x versus voluntary markets.
Segment Deep-Dive: Building Management Systems Dominance in Commercial Building Automation Market
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Building Management Systems
10.2
34
Cloud analytics and multi-site consolidation
HVAC Controls
9.6
28
Decarbonization, refrigerant rules, IAQ
Security and Access Control Systems
9.1
17
Touchless access, IP video, cybersecurity
Energy Management Systems
10.8
12
Energy cost volatility and ESG reporting
Lighting Management Systems
9.4
9
LED retrofit, occupancy sensing, code compliance
The Building Management Systems Market is the single largest revenue pool, estimated at USD 21.3 billion in 2024. Its growth is tied to cloud-hosted supervisory control, open protocols such as BACnet and Modbus, and analytics that cut energy use by 10-20%. The Security and Access Control Systems Market is the third-largest segment, benefiting from IP camera migration and mobile credential adoption. Within HVAC, the HVAC Controls Market is boosted by variable refrigerant flow, heat pump controls, and indoor air quality monitoring.
Sub-Segment Dynamics
Wired Building Automation Market still holds about 78% of installed communication value because of reliability in hospitals, labs, and data centers.
Smart Lighting Controls Market is the fastest-growing product sub-segment at 10.9% CAGR, as wireless mesh and PoE lighting reduce retrofit labor.
Energy Management Systems Market is converging with BMS, and standalone EMS share is shrinking as analytics move into building operating systems.
Small and medium enterprises adopt packaged controls with lower engineering content, while large enterprises buy multi-site platforms with API integration.
Margin Pressures
Hardware commoditization in thermostats, sensors, and relays compresses gross margins to 25-35% for basic devices.
Software and recurring service margins remain 60-75%, pushing vendors toward subscriptions and outcome-based contracts.
Integration labor shortages inflate project costs, but remote commissioning tools reduce site visits by 20-30%.
Primary Market Drivers & Growth Restraints in Commercial Building Automation Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Energy price volatility and net-zero building targets
High
Long term
Driver
Government efficiency mandates and codes (Title 24, EPBD)
High
Long term
Driver
Commercial IoT for Buildings Market expansion and analytics
High retrofit capex and long payback in older assets
High
Medium term
Restraint
Cybersecurity exposure in connected BAS
High
Long term
Restraint
Fragmented protocols and legacy interoperability
Medium
Long term
Restraint
Semiconductor and controller component lead times
Medium
Short term
Quantitative evaluation shows demand elasticity to energy prices: every 10% rise in commercial electricity tariffs historically correlates with a 4-6% increase in energy management and lighting controls spending. The Wireless Building Automation Market is expanding at 11.5% CAGR because wireless sensors cut wiring costs by 30-50% in existing buildings. The Commercial IoT for Buildings Market links wireless sensors, cloud analytics, and remote diagnostics into a single demand pool, while the Energy Management Systems Market faces margin pressure from bundled BMS software, though ESG disclosure rules keep enterprise demand firm.
Drivers: Decarbonization mandates, indoor air quality standards, utility demand-response programs, and insurance discounts for monitored buildings.
Restraints: Skilled integrator scarcity, owner capex hesitation under high interest rates, and cybersecurity compliance costs that can add 7-12% to project budgets.
Net impact: Drivers outweigh restraints through 2033, but growth will be lumpy in rate-sensitive North American and European retrofit markets.
Competitive Ecosystem & Key Vendor Profiles: Commercial Building Automation Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
Honeywell International
Forge analytics, integrated controls
Large enterprises, campuses
Leader
Siemens AG
Xcelerator, Desigo CC, digital twins
Industrial and commercial portfolios
Leader
Schneider Electric
EcoStruxure Building, energy management
Global REITs, data centers
Leader
Johnson Controls
OpenBlue, HVAC and fire integration
Multi-site corporates, healthcare
Leader
ABB
Electrical distribution, KNX, building controls
Utilities, smart buildings
Challenger
Carrier
Connected HVAC, i-Vu controls
HVAC contractors, retail
Challenger
Trane Technologies
Symbio, rental and service model
Education, healthcare, offices
Challenger
Robert Bosch
Building security, IoT sensors
Security integrators, retail
Challenger
Hubbell
Lighting controls, electrical products
Electrical contractors
Niche
Legrand
Wattstopper, lighting and AV controls
Office and hospitality
Niche
Honeywell International: Combines Forge software with controls and cybersecurity services, targeting Fortune 500 real estate portfolios.
Siemens AG: Uses Xcelerator and Desigo to link building data with grid interaction and enterprise digital twins.
Schneider Electric: EcoStruxure Building integrates power, energy, and sustainability reporting for global clients.
Johnson Controls: OpenBlue connects HVAC, fire, security, and space utilization in a single cloud environment.
ABB: Leverages electrical distribution and KNX expertise to bundle building automation with EV charging.
Carrier: Focuses on HVAC-centric automation and aftermarket service, especially in retail and light commercial.
Trane Technologies: Uses Symbio controls and service contracts to capture energy-as-a-service opportunities.
Robert Bosch: Combines security, access, and sensor hardware with building IoT gateways.
Hubbell: Provides lighting controls and electrical wiring devices for code-driven retrofit projects.
Legrand: Targets lighting, shading, and AV control niches in premium office and hospitality buildings.
Strategic Milestones & Recent Developments in Commercial Building Automation Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2024
Johnson Controls
Partnership
Expanded OpenBlue integrations with IT and OT vendors
2024
Honeywell
Launch
Forge for Buildings updates added AI fault detection
2024
Schneider Electric
M&A
Acquired software assets to strengthen grid-to-building analytics
2025
Siemens
Launch
Released Xcelerator building IoT modules for edge control
2025
Carrier
Partnership
Allied with service providers for connected HVAC retrofits
2025
Trane Technologies
Launch
Symbio controls updated for heat pump and VRF systems
2024: Johnson Controls deepened alliances with IT infrastructure providers to deliver unified building operations dashboards.
2024: Honeywell rolled out AI-driven fault detection across its Forge platform, targeting 15-25% energy savings in pilot sites.
2024: Schneider Electric acquired smaller analytics firms to close gaps in submetering and carbon reporting.
2025: Siemens launched edge-ready modules that allow legacy equipment to join Xcelerator without full controller replacement.
2025: Carrier and Trane expanded service partnerships, reflecting a shift from one-time equipment sales to recurring outcome contracts.
2025: ABB and Legrand continued tuck-in acquisitions in lighting and EV charging controls, blurring lines between electrical and automation vendors.
Regional Market Analysis & Growth Corridors for Commercial Building Automation Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
8.6
USD 19.4 billion
Retrofit tax incentives, data centers
High
Europe
8.9
USD 15.0 billion
EPBD, carbon pricing, renovation wave
Very high
Asia-Pacific
11.2
USD 20.0 billion
New construction, smart cities
Medium-high
South America
8.1
USD 3.8 billion
Urbanization, energy cost
Medium
Middle East & Africa
9.4
USD 4.4 billion
Mega projects, district cooling
Medium
North America remains the most mature market for integrated BMS, but growth is slower than Asia-Pacific because building stock is older and code adoption varies by state. Europe has the most stringent regulatory environment, with the Energy Performance of Buildings Directive driving submetering, automation, and inspection requirements. Asia-Pacific is the fastest-growing corridor: China and India together account for over 60% of regional new construction, while Japan and South Korea focus on advanced building IoT and zero-energy buildings.
Fastest-growing markets: India, ASEAN, and GCC countries, where new commercial floorspace and district cooling systems require centralized controls.
Most mature markets: United States, Germany, and Nordics, where replacement cycles and software upgrades dominate over greenfield installations.
LAMEA outlook: South America faces currency and capex volatility, but Brazil's commercial retrofit activity is rising; Middle East demand is tied to giga-projects and tourism infrastructure.
Cross-regional issue: cybersecurity and data sovereignty rules increasingly require local cloud hosting, affecting vendor architecture choices.
Sustainability, ESG & Decarbonization Pressures on Commercial Building Automation Market
ESG Driver Matrix
ESG Pressure
Building Automation Response
Measurable Impact
Net-zero portfolio targets
BMS scheduling, fault detection, submetering
10-20% energy reduction
Carbon disclosure rules
Energy management systems with audit trails
Scope 1-2 reporting accuracy
Circular economy mandates
Longer firmware support, take-back programs
3-7 year hardware life extension
Indoor air quality standards
CO2 and VOC sensors with demand-controlled ventilation
15-30% ventilation energy savings
Green leasing
Tenant submetering and dashboards
Higher occupancy and rent premiums
Environmental regulations and corporate ESG criteria are reshaping procurement. Landlords with net-zero commitments now require building automation to produce verifiable energy and carbon data, not just control HVAC. This favors vendors that combine BMS, metering, and analytics with open APIs. Circular economy rules in the EU and parts of North America pressure manufacturers to offer module-level replacement, take-back, and long-term firmware support, extending device life and reducing e-waste.
Raw material selection: Vendors face scrutiny on conflict minerals, halogenated flame retardants, and rare earth content in motors and sensors.
Manufacturing processes: EMS providers increasingly report carbon intensity per controller and use recycled plastics in enclosures.
Procurement preferences: Green building certifications such as LEED and BREEAM award points for advanced automation and measurement, influencing owner specifications.
Investor criteria: ESG funds screen building automation vendors on supply chain transparency and product energy efficiency, affecting cost of capital and M&A valuations.
Supply Chain & Raw Material Dynamics: Commercial Building Automation Market
Raw Material and Component Price Trends
Input
Trend Direction
Supply Risk
Automation Impact
Semiconductors and microcontrollers
Stable after 2023 shortages
Medium
Controller lead times affect project schedules
Copper and wiring
Upward
Medium
Raises wired installation cost
Rare earth magnets
Volatile
High
Affects motors, fans, and valve actuators
PCB laminates and connectors
Moderately up
Low-medium
Influences sensor and gateway pricing
Plastic enclosures and resins
Mixed
Low
Ties to oil prices and recycled content rules
Lithium batteries for wireless sensors
Downward
Low
Improves wireless node economics
The Building Automation Sensors Market depends on semiconductor fabs, MEMS foundries, and PCB assembly clusters in Taiwan, South Korea, and mainland China. Copper price swings directly affect the Wired Building Automation Market because cabling and power distribution can represent 20-30% of retrofit material cost. Rare earth magnet volatility affects HVAC damper actuators and fan motors, creating procurement risk for Trane, Carrier, and Johnson Controls. Historical disruptions include the 2021-2023 semiconductor shortage, which stretched controller lead times beyond 40 weeks and delayed commercial projects.
Upstream dependencies: Microcontrollers, analog ICs, sensors, relays, power supplies, and communication modules.
Vendor dependencies: Many OEMs rely on a small number of contract manufacturers for controllers and gateways, increasing concentration risk.
Price volatility: Copper and rare earths remain the most volatile inputs; buyers use indexed contracts and dual sourcing to manage exposure.
Mitigation: Modular designs, wireless alternatives, and regional assembly help reduce supply chain fragility, though cybersecurity certification can slow component changes.
Commercial Building Automation Market Segmentation
1. Product Type
1.1. HVAC
1.2. Building Management Systems
1.3. Security and Access Control Systems
1.4. Energy Management Systems
1.5. Lighting Management Systems
2. Enterprise Size
2.1. SMALL AND MEDIUM ENTERPRISES
2.2. LARGE ENTERPRISES
3. Communication Technology
3.1. Wired Technology
3.2. Wireless Technology
Commercial Building Automation Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Commercial Building Automation Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.9% from 2020-2034
Segmentation
By Product Type
HVAC
Building Management Systems
Security and Access Control Systems
Energy Management Systems
Lighting Management Systems
By Enterprise Size
SMALL AND MEDIUM ENTERPRISES
LARGE ENTERPRISES
By Communication Technology
Wired Technology
Wireless Technology
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. HVAC
5.1.2. Building Management Systems
5.1.3. Security and Access Control Systems
5.1.4. Energy Management Systems
5.1.5. Lighting Management Systems
5.2. Market Analysis, Insights and Forecast - by Enterprise Size
5.2.1. SMALL AND MEDIUM ENTERPRISES
5.2.2. LARGE ENTERPRISES
5.3. Market Analysis, Insights and Forecast - by Communication Technology
5.3.1. Wired Technology
5.3.2. Wireless Technology
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. HVAC
6.1.2. Building Management Systems
6.1.3. Security and Access Control Systems
6.1.4. Energy Management Systems
6.1.5. Lighting Management Systems
6.2. Market Analysis, Insights and Forecast - by Enterprise Size
6.2.1. SMALL AND MEDIUM ENTERPRISES
6.2.2. LARGE ENTERPRISES
6.3. Market Analysis, Insights and Forecast - by Communication Technology
6.3.1. Wired Technology
6.3.2. Wireless Technology
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. HVAC
7.1.2. Building Management Systems
7.1.3. Security and Access Control Systems
7.1.4. Energy Management Systems
7.1.5. Lighting Management Systems
7.2. Market Analysis, Insights and Forecast - by Enterprise Size
7.2.1. SMALL AND MEDIUM ENTERPRISES
7.2.2. LARGE ENTERPRISES
7.3. Market Analysis, Insights and Forecast - by Communication Technology
7.3.1. Wired Technology
7.3.2. Wireless Technology
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. HVAC
8.1.2. Building Management Systems
8.1.3. Security and Access Control Systems
8.1.4. Energy Management Systems
8.1.5. Lighting Management Systems
8.2. Market Analysis, Insights and Forecast - by Enterprise Size
8.2.1. SMALL AND MEDIUM ENTERPRISES
8.2.2. LARGE ENTERPRISES
8.3. Market Analysis, Insights and Forecast - by Communication Technology
8.3.1. Wired Technology
8.3.2. Wireless Technology
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. HVAC
9.1.2. Building Management Systems
9.1.3. Security and Access Control Systems
9.1.4. Energy Management Systems
9.1.5. Lighting Management Systems
9.2. Market Analysis, Insights and Forecast - by Enterprise Size
9.2.1. SMALL AND MEDIUM ENTERPRISES
9.2.2. LARGE ENTERPRISES
9.3. Market Analysis, Insights and Forecast - by Communication Technology
9.3.1. Wired Technology
9.3.2. Wireless Technology
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. HVAC
10.1.2. Building Management Systems
10.1.3. Security and Access Control Systems
10.1.4. Energy Management Systems
10.1.5. Lighting Management Systems
10.2. Market Analysis, Insights and Forecast - by Enterprise Size
10.2.1. SMALL AND MEDIUM ENTERPRISES
10.2.2. LARGE ENTERPRISES
10.3. Market Analysis, Insights and Forecast - by Communication Technology
10.3.1. Wired Technology
10.3.2. Wireless Technology
11. Competitive Analysis
11.1. Company Profiles
11.1.1. ABB
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. TRANE TECHNOLOGIES
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. ROBERT BOSCH
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. SIEMENS AG
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. CARRIER
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. HUBBELL
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. JOHNSON CONTROLS
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. LEGRAND
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. HONEYWELL INTERNATIONAL
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. SCHNEIDER ELECTRIC
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Commercial Building Automation Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Commercial Building Automation Market Revenue (billion), by Product Type 2026 & 2034
Figure 3: North America Commercial Building Automation Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Commercial Building Automation Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 5: North America Commercial Building Automation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 6: North America Commercial Building Automation Market Revenue (billion), by Communication Technology 2026 & 2034
Figure 7: North America Commercial Building Automation Market Revenue Share (%), by Communication Technology 2026 & 2034
Figure 8: North America Commercial Building Automation Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Commercial Building Automation Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Commercial Building Automation Market Revenue (billion), by Product Type 2026 & 2034
Figure 11: South America Commercial Building Automation Market Revenue Share (%), by Product Type 2026 & 2034
Figure 12: South America Commercial Building Automation Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 13: South America Commercial Building Automation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 14: South America Commercial Building Automation Market Revenue (billion), by Communication Technology 2026 & 2034
Figure 15: South America Commercial Building Automation Market Revenue Share (%), by Communication Technology 2026 & 2034
Figure 16: South America Commercial Building Automation Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Commercial Building Automation Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Commercial Building Automation Market Revenue (billion), by Product Type 2026 & 2034
Figure 19: Europe Commercial Building Automation Market Revenue Share (%), by Product Type 2026 & 2034
Figure 20: Europe Commercial Building Automation Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 21: Europe Commercial Building Automation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 22: Europe Commercial Building Automation Market Revenue (billion), by Communication Technology 2026 & 2034
Figure 23: Europe Commercial Building Automation Market Revenue Share (%), by Communication Technology 2026 & 2034
Figure 24: Europe Commercial Building Automation Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Commercial Building Automation Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Commercial Building Automation Market Revenue (billion), by Product Type 2026 & 2034
Figure 27: Middle East & Africa Commercial Building Automation Market Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Middle East & Africa Commercial Building Automation Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 29: Middle East & Africa Commercial Building Automation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 30: Middle East & Africa Commercial Building Automation Market Revenue (billion), by Communication Technology 2026 & 2034
Figure 31: Middle East & Africa Commercial Building Automation Market Revenue Share (%), by Communication Technology 2026 & 2034
Figure 32: Middle East & Africa Commercial Building Automation Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Commercial Building Automation Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Commercial Building Automation Market Revenue (billion), by Product Type 2026 & 2034
Figure 35: Asia Pacific Commercial Building Automation Market Revenue Share (%), by Product Type 2026 & 2034
Figure 36: Asia Pacific Commercial Building Automation Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 37: Asia Pacific Commercial Building Automation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 38: Asia Pacific Commercial Building Automation Market Revenue (billion), by Communication Technology 2026 & 2034
Figure 39: Asia Pacific Commercial Building Automation Market Revenue Share (%), by Communication Technology 2026 & 2034
Figure 40: Asia Pacific Commercial Building Automation Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Commercial Building Automation Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Commercial Building Automation Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 2: Commercial Building Automation Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 3: Commercial Building Automation Market Revenue billion Forecast, by Communication Technology 2020 & 2034
Table 4: Commercial Building Automation Market Revenue billion Forecast, by Region 2020 & 2034
Table 5: North America Commercial Building Automation Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 6: North America Commercial Building Automation Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 7: North America Commercial Building Automation Market Revenue billion Forecast, by Communication Technology 2020 & 2034
Table 8: North America Commercial Building Automation Market Revenue billion Forecast, by Country 2020 & 2034
Table 9: United States Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 10: Canada Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: South America Commercial Building Automation Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 13: South America Commercial Building Automation Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 14: South America Commercial Building Automation Market Revenue billion Forecast, by Communication Technology 2020 & 2034
Table 15: South America Commercial Building Automation Market Revenue billion Forecast, by Country 2020 & 2034
Table 16: Brazil Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: Argentina Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Europe Commercial Building Automation Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 20: Europe Commercial Building Automation Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 21: Europe Commercial Building Automation Market Revenue billion Forecast, by Communication Technology 2020 & 2034
Table 22: Europe Commercial Building Automation Market Revenue billion Forecast, by Country 2020 & 2034
Table 23: United Kingdom Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Germany Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: France Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Italy Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Spain Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Russia Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: Benelux Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Nordics Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Commercial Building Automation Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 33: Middle East & Africa Commercial Building Automation Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 34: Middle East & Africa Commercial Building Automation Market Revenue billion Forecast, by Communication Technology 2020 & 2034
Table 35: Middle East & Africa Commercial Building Automation Market Revenue billion Forecast, by Country 2020 & 2034
Table 36: Turkey Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Israel Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: GCC Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: North Africa Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: South Africa Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Commercial Building Automation Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 43: Asia Pacific Commercial Building Automation Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 44: Asia Pacific Commercial Building Automation Market Revenue billion Forecast, by Communication Technology 2020 & 2034
Table 45: Asia Pacific Commercial Building Automation Market Revenue billion Forecast, by Country 2020 & 2034
Table 46: China Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: India Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: Japan Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: South Korea Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: ASEAN Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Oceania Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Commercial Building Automation Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of data inputs, with 20–30% from secondary sources.
We interview building automation controller OEM product managers, BMS software integration directors, HVAC controls distributors, commercial real estate energy managers, and smart building cybersecurity consultants.
Stakeholder interviews include Building Automation Procurement Director, Facility Energy Manager, HVAC Controls Product Manager, and Chief Building Engineer.
Primary surveys capture installed base, retrofit cycles, pricing, and satisfaction across North America, Europe, Asia-Pacific, South America, and Middle East & Africa.
Interviews are conducted quarterly and refreshed to the date of purchase.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Building Automation Procurement Director
25%
Facility Energy Manager
20%
HVAC Controls Product Manager
20%
Chief Building Engineer
15%
Smart Buildings Solutions Architect
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Building Automation Controller OEMs
25%
HVAC Equipment Manufacturers
20%
BMS Software Integrators
20%
IoT Sensor & Wireless Module Vendors
15%
System Integrators & Installers
20%
Secondary Research & Industry Benchmarking
Secondary research validates primary findings using Bloomberg, Factiva, Hoovers, and PitchBook for company financials, M&A, and market share.
Regulatory and technical benchmarking draws on .gov and .org sources including the U.S. Department of Energy (DOE), ASHRAE (ASHRAE), the European Commission (EC), and the International Energy Agency (IEA).
Trade associations and standards bodies include BACnet International, LonMark International, KNX Association, and the National Electrical Manufacturers Association (NEMA).
Secondary data is screened for methodology transparency, sample size, and publication date, with no reliance on market research websites.
Demand Modeling & Market Estimation
We use simultaneous top-down and bottom-up methodologies, then triangulate at product, enterprise size, communication technology, and country levels.
Bottom-up market size uses quantitative metrics such as commercial floorspace under management (million square meters), annual building automation retrofit rate (%), average controller and sensor content per 1,000 square meters, and building automation attach rate in new construction (%).
Demand models incorporate HVAC Controls Market, Energy Management Systems Market, Security and Access Control Systems Market, Wireless Building Automation Market, and Wired Building Automation Market revenue pools.
Forecast period 2026-2034 uses scenario weighting for energy prices, interest rates, code adoption, and semiconductor availability.
Data Accuracy & Quality Check
Estimated data accuracy is guaranteed at 85–90%, with confidence intervals reported for regional and segment forecasts.
Multi-level data triangulation cross-checks OEM revenue, distributor sell-through, installer surveys, and building permit data.
Outlier detection, currency normalization, and double-blind interview review reduce bias.
Every report is updated to the date of purchase, and revisions are tracked with version control.
Frequently Asked Questions
1. How do building codes and energy regulations affect the Commercial Building Automation Market?
Regulations such as ASHRAE 90.1, California Title 24, and the EU Energy Performance of Buildings Directive require automated lighting, HVAC, and metering in many commercial buildings. Compliance pressures push owners to adopt BMS and energy management systems; for example, Title 24 updates can raise controls content in new construction by 15-20%. Enforcement varies by jurisdiction, so vendors must localize certification and documentation.
2. What are the biggest supply chain and deployment challenges restraining market growth?
Key restraints include high upfront retrofit costs, cybersecurity vulnerabilities in IP-connected BAS, and shortages of skilled integrators. Semiconductor lead times for building controllers, which peaked above 40 weeks in 2022-2023, still create project delays. Wireless interference and legacy protocol incompatibility also raise commissioning costs by an estimated 10-15% in older buildings.
3. Which product segments and applications generate the most revenue in the Commercial Building Automation Market?
Building Management Systems and HVAC controls together account for over 60% of 2024 revenue, with BMS alone at roughly 34% share. Security and access control, energy management, and lighting management systems make up the remainder. Demand concentrates in offices, retail, healthcare, and data centers, where 24/7 operations justify automation payback under four years.
4. What recent developments, partnerships, or M&A moves have shaped the vendor landscape?
In 2024-2025, Johnson Controls expanded OpenBlue partnerships, Honeywell launched Forge for Buildings upgrades, and Schneider Electric acquired several grid-to-building software assets. Siemens invested in Xcelerator-based building IoT modules, while Carrier and Trane pushed connected HVAC service platforms. These moves intensify competition in cloud analytics and remote commissioning.
5. Why is the Commercial Building Automation Market growing at 9.9% CAGR?
Growth is driven by energy price volatility, net-zero real estate targets, and payback periods that often fall below five years for lighting and HVAC retrofits. Labor shortages in facility management also favor automated fault detection and remote operations. Emerging market construction in Asia-Pacific adds greenfield demand, with China and India accounting for a rising share of new BMS deployments.
6. How do ESG and decarbonization requirements influence building automation procurement?
ESG criteria now push landlords and REITs to disclose energy intensity, carbon emissions, and IAQ metrics, making submetering and analytics mandatory in many leases. Net-zero commitments from corporates covering over 10,000 buildings globally favor energy management systems and smart lighting controls. Circular economy requirements also affect hardware selection, with vendors pressured to offer take-back and longer firmware support.