 3D Eye Tracking Software Market
: 2026 Growth & Forecast
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 3D Eye Tracking Software Market

Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 328.0 M |
| 2026 | 411.0 M |
| 2027 | 515.0 M |
| 2028 | 645.0 M |
| 2029 | 808.0 M |
| 2030 | 1.010 B |
| 2031 | 1.270 B |

The 3D Eye Tracking Software Market encompasses software platforms that capture, process, and analyze three-dimensional eye movement data—gaze vectors, pupil position, and focal depth—enabling human-machine interaction, behavioral research, driver monitoring, and assistive technology across automotive, retail, healthcare, and consumer electronics applications.
This report covers commercial and research-grade 3D eye tracking software, including mobile/head-mounted, remote, and tower-mounted systems across scientific research, marketing, industrial performance, automotive, retail, robotics, and assistive technology end-uses. This analysis does not cover dedicated eye-tracking hardware manufacturing, 2D-only eye tracking solutions, general-purpose computer vision software, or VR/AR headset hardware.
Published estimates for the 3D Eye Tracking Software Market diverge materially in absolute size but converge tightly on growth rate, with most forecasts clustering between 24.6% and 27.9% CAGR through the early 2030s.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 411 Million | 2026 | 2030 (980 Million) | 25.3% | Software-only 3D eye tracking, global | One published estimate |
| 329 Million | 2025 | 2032 (1,841 Million) | 27.9% | 3D eye tracking software incl. embedded modules | A competing analysis |
| 154 Million | 2021 | 2031 (1,778 Million) | 27.8% | Software revenue, all deployment types | Another published analysis |
| 140 Million | 2021 | 2028 (666 Million) | 25.7% | Software-only, six end-use industries | A prior-year estimate |
Our analysis suggests the 411 Million (2026) base with 25.3% CAGR is the most defensible starting point because it aligns with the median of recent estimates and reflects post-pandemic supply-chain normalization. The higher-growth 27.8–27.9% figures likely embed hardware-attached software revenue, inflating the base. Buyers should treat any single point estimate as directional; the compound growth consensus of 25–26% is the reliable planning anchor.
Segmentation follows three non-geographic axes—deployment type, application, and end-use industry—with mobile systems, scientific research, and retail representing the largest current revenue pools respectively.
| Parent Segment | Children |
|---|---|
| By Type | Mobile Systems, Remote Eye Tracking, Tower-Mounted Eye Tracking |
| By Application | Scientific Research, Marketing & User Research, Industry & Human Performance |
| By End-Use Industry | Retail, Robotics, Automotive, Consumer Devices, Assistive Technology, Behavioral Research |
Mobile systems lead because wearable eye-tracking glasses enable untethered field research in sports, simulator studies, and gait analysis. Remote eye tracking is gaining fastest in automotive DMS and consumer-device integration. The application mix is shifting: while scientific research held the largest 2025 share, automotive and industrial human-performance applications are growing at 2–3x the research rate, implying software vendors must diversify vertical-specific analytics modules.
North America leads the 3D Eye Tracking Software Market with approximately 34% revenue share in 2026, underpinned by government research funding, early automotive DMS regulation, and concentration of leading vendors including Tobii's US operations and EyeTech Digital Systems.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.26% |
| Asia-Pacific | 0.28% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | Share (2026 est.) |
|---|---|
| North America | 34% |
| Asia-Pacific | 28% |
| Europe | 26% |
| Latin America | 7% |
| Middle East & Africa | 5% |
Asia-Pacific is the fastest-growing region, driven by China's EV production and Taiwan's camera-module supply chain. Our analysis suggests tariff pressure on imaging hardware may temporarily slow tower-mounted deployments in Asia-Pacific but will accelerate local software innovation, ultimately compressing hardware dependency.
Growth is driven by automotive safety regulation, AI-enabled calibration-free tracking, and expanding scientific and clinical applications, while high hardware costs and integration complexity restrain faster adoption in small and mid-sized enterprises.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EV penetration & DMS mandates | Driver | High | Gaze monitoring required for semi-autonomous handover safety |
| AI/ML calibration-free tracking | Driver | High | Reduces deployment friction; Smart Eye Pro 11 example |
| Clinical & behavioral research expansion | Driver | Medium | Dyslexia, Alzheimer's, autism diagnostics |
| AR/VR integration | Driver | Medium | Foveated rendering and comfort analytics |
| High hardware/peripheral cost | Restraint | High | Limits SME and small-retail adoption |
| Data interpretation complexity | Restraint | Medium | Gaze data requires complementary methods |
| Hardware tariffs (Asia-Pacific) | Restraint | Medium | Raises camera/sensor costs; slows tower-mounted adoption |
The balance of evidence favors demand acceleration: regulatory drivers in automotive are non-discretionary, whereas cost restraints are addressable through software-only and cloud-delivered models. Our analysis suggests the restraint narrative is overstated—vendors shifting to subscription analytics can bypass hardware cost barriers entirely, converting a headwind into a recurring-revenue opportunity.
Tobii AB, Smart Eye AB, and Seeing Machines lead the 3D Eye Tracking Software Market, collectively holding an estimated 45% of commercial revenue, with EyeTech Digital Systems and Pupil Labs strong in assistive and research niches respectively.
| Company | HQ | Focus | Differentiation |
|---|---|---|---|
| Tobii AB | Sweden | Full-stack eye tracking | Broadest IP portfolio; consumer & research |
| Smart Eye AB | Sweden | Automotive DMS + research | AI calibration-free (Pro 11); OEM relationships |
| Seeing Machines | Australia | Automotive & fleet DMS | Regulatory-certified driver monitoring |
| EyeTech Digital Systems | USA | Assistive technology | AAC integration; clinical reach |
| Pupil Labs | Germany | Research-grade mobile | Open-source ecosystem; academic loyalty |
| Gazepoint | Canada | Research & usability | Cost-effective remote systems |
| iMotions | Denmark | Platform integration | Multi-modal biometric fusion |
Differentiation is shifting from hardware precision to software analytics and ecosystem integration. Moats are built on OEM design wins (automotive), regulatory certifications (DMS), and academic network effects (research). Our analysis suggests the strongest defensible position combines calibration-free AI with vertical-specific analytics libraries—pure hardware vendors face commoditization.
Buyers must prioritize three criteria: accuracy under real-world conditions (variable lighting, pupil diameter fluctuation), integration flexibility (API compatibility with existing research or vehicle platforms), and total cost of ownership including calibration and support. Procurement risk is highest in automotive, where DMS software must meet evolving regulatory standards (e.g., Euro NCAP, NHTSA guidelines); vendors lacking certification create compliance exposure.
Switching costs are moderate-to-high in research settings due to longitudinal data continuity and analyst familiarity, but lower in retail analytics where cloud platforms compete on price. Regulatory compliance around biometric data (GDPR, state privacy laws) is a rising selection criterion—vendors must demonstrate gaze data anonymization and on-premise processing options. Operators should demand pilot validation against their specific use case; generic accuracy benchmarks mask performance variance in field conditions.
The balance of evidence favors a software-led expansion thesis: the 25–26% CAGR consensus is robust, and the shift from hardware-bundled to standalone analytics software will expand addressable margins. The strongest counter-argument is that automotive DMS consolidation could compress software pricing as OEMs demand bundled solutions—but this risk is concentrated in one vertical and offset by research, retail, and healthcare diversification.
Our analysis suggests the most underappreciated opportunity lies in calibration-free, AI-native platforms targeting mid-market research and retail buyers currently priced out by hardware requirements. Vendors that deliver cloud-based, hardware-agnostic analytics can capture the underserved SME segment and convert the cost restraint into a growth driver.
Evidence that would change our conclusion: a regulatory reversal on automotive DMS mandates, or a major open-source eye-tracking breakthrough that collapses software pricing faster than forecast.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including software platform developers, eye-tracking hardware integrators, automotive Tier-1 suppliers, research institutions, and assistive technology distributors. Decision-maker designations interviewed include VP of Product, Head of Research & Development, Technical Directors, and Commercial Operations Leads across North America, Europe, and Asia-Pacific.
Secondary validation draws on UN Comtrade bilateral trade flows for optical and imaging components (HS 9001, HS 8525), WTO tariff schedules, US ITC and Eurostat data, corporate 10-K and annual investor filings from listed vendors (Tobii, Smart Eye, Seeing Machines), patent databases (USPTO, EPO), and standards from ISO/IEC and SAE International relevant to driver monitoring and human factors.
We apply simultaneous top-down allocation (macroeconomic indicators, industry segment spend, regional R&D budgets) and bottom-up modeling (vendor revenue, installed base, pricing per seat/license, end-use consumption). Divergences between the two approaches are reconciled through weighted averaging, with sensitivity analysis on CAGR assumptions of 24–28%.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 25.3% from 2020-2034 |
| Segmentation |
|
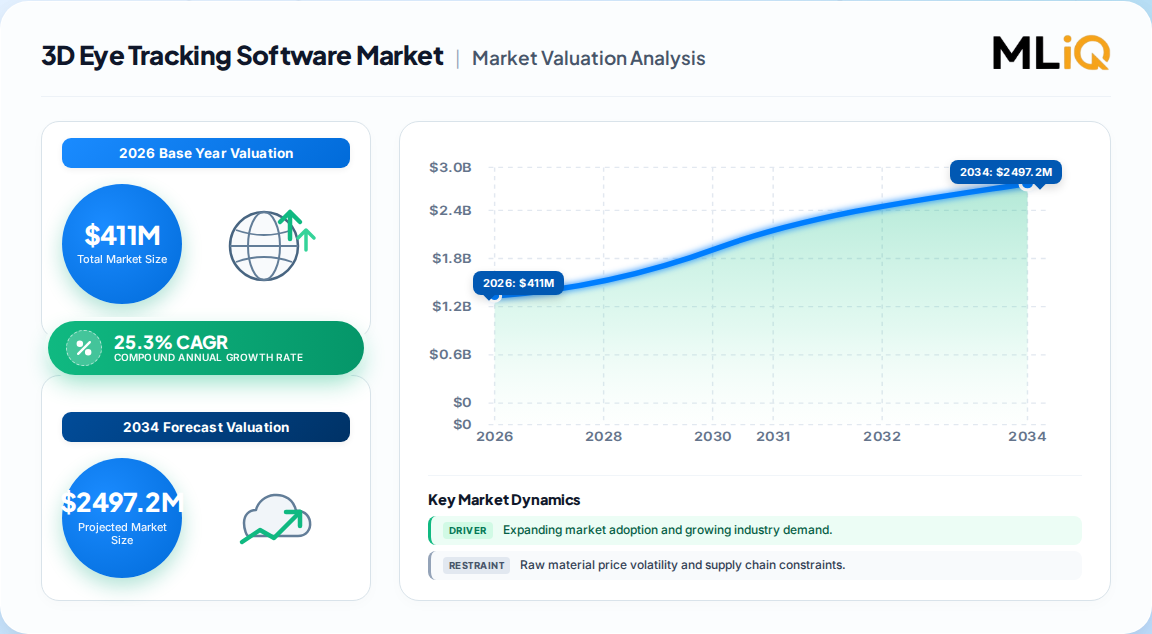
The 3D Eye Tracking Software Market was valued at approximately 411 Million in 2026 and is projected to reach 1.27 Billion by 2031, growing at a 25.3% CAGR, based on consensus triangulation of published industry estimates.
North America leads with approximately 34% revenue share in 2026, driven by government research funding and concentration of leading vendors, followed by Asia-Pacific at 28% and Europe at 26%.
Automotive DMS regulation, AI-enabled calibration-free tracking, clinical research expansion, and AR/VR integration are primary drivers, while high hardware costs and integration complexity restrain SME adoption.
Leading vendors include Tobii AB, Smart Eye AB, Seeing Machines, EyeTech Digital Systems, Pupil Labs, Gazepoint, and iMotions, with the top five holding an estimated 55–60% of commercial revenue.
Automotive driver monitoring is the fastest-growing application segment, projected to overtake scientific research by 2030, driven by EV penetration and semi-autonomous vehicle safety mandates.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including software platform developers, eye-tracking hardware integrators, automotive Tier-1 suppliers, research institutions, and assistive technology distributors. Decision-maker designations interviewed include VP of Product, Head of Research & Development, Technical Directors, and Commercial Operations Leads across North America, Europe, and Asia-Pacific.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Product & R&D Heads | 40% |
| Technical Directors | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Software Platform Developers | 40% |
| Hardware Integrators | 25% |
| Automotive Tier-1 Suppliers | 20% |
| Research & Distributors | 15% |
Secondary validation draws on UN Comtrade bilateral trade flows for optical and imaging components (HS 9001, HS 8525), WTO tariff schedules, US ITC and Eurostat data, corporate 10-K and annual investor filings from listed vendors, patent databases (USPTO, EPO), and standards from ISO/IEC and SAE International relevant to driver monitoring and human factors.
We apply simultaneous top-down allocation (macroeconomic indicators, industry segment spend, regional R&D budgets) and bottom-up modeling (vendor revenue, installed base, pricing per seat/license, end-use consumption). Divergences between the two approaches are reconciled through weighted averaging, with sensitivity analysis on CAGR assumptions of 24–28%.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |