Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Fire Adapters Market Size, Share & Forecast to 2034
Fire Adapters Market
Fire Adapters Market Size, Share & Forecast to 2034
Fire Adapters Market by Product Type (Storz Adapters, Quick-Connect Adapters, Thread-Conversion Adapters, Reducers, Hose Couplings, Wye and Siamese Adapters), by Material (Aluminum Alloy, Brass, Stainless Steel, Ductile Iron, Composite), by End-User (Municipal Fire Service, Industrial, Commercial, Residential, Forestry and Wildland), by Sales Channel (Direct OEM, Distribution and Dealer, Municipal Tender), by Pressure Rating (Low Pressure, Medium Pressure, High Pressure), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Nordics), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia, Australia), by Latin America (Brazil, Mexico, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0
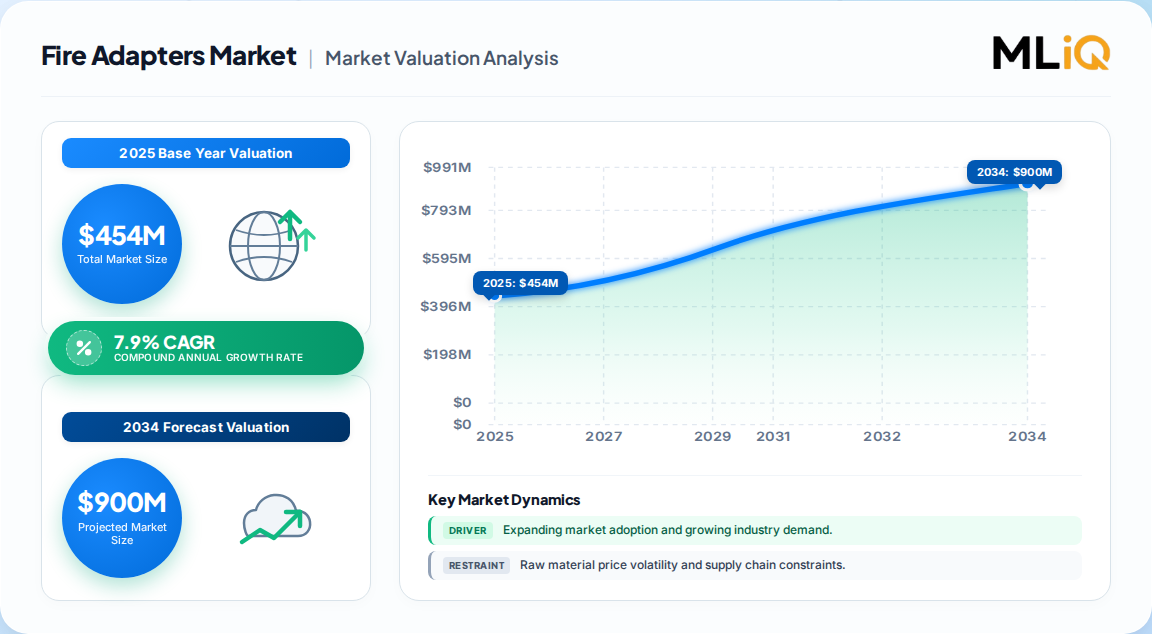
The global Fire Adapters Market was sized at 454 Million in 2025 and is projected to reach 716 Million by 2031, advancing at a 7.9% CAGR.
North America leads with an estimated 34% value share, reflecting mature municipal fire services, stringent NFPA enforcement and rapid industrial retrofit cycles.
Industrial and oil & gas end-users are the fastest-growing demand cluster, driven by fire-sensitive facility expansion and mandatory safety audits.
The quick-connect and storz-type adapter families account for the largest product-value pool, while aluminum alloy bodies remain the volume leader over brass and stainless steel.
Supply remains moderately fragmented: regional fabricators dominate local distribution, with only a handful of global players controlling cross-border institutional supply.
Vendors face rising input volatility in aluminum billet and brass alloy pricing, compressing margins for non-specification-grade commodity adapters.
Why this matters for decision-makers: Buyers must shift from lowest-price sourcing toward verified pressure-rated and standards-certified adapters. Commodity purchasing in this category transfers catastrophic failure risk to the fireground, making compliance-driven supplier qualification the single highest-value strategic move.
Fire Adapters Market Size (In Million)
750.0M
600.0M
450.0M
300.0M
150.0M
0
420.0 M
2024
454.0 M
2025
490.0 M
2026
528.0 M
2027
570.0 M
2028
615.0 M
2029
664.0 M
2030
Fire Adapters Market Size (In Million)
Year
Market Size
2024
420.0 M
2025
454.0 M
2026
490.0 M
2027
528.0 M
2028
570.0 M
2029
615.0 M
2030
664.0 M
What is the Fire Adapters Market?
The Fire Adapters Market covers couplings, reducers, storz, quick-connect and thread-conversion fittings that join fire hoses, hydrants, nozzles and pumps across firefighting systems. It spans municipal fire services, industrial fire protection, oil & gas and commercial facilities, and is shaped by pressure ratings, thread standards and material specification.
Scope: what this report covers and excludes
This report covers fire hose adapters, couplings, reducers, storz fittings, quick-connect adapters and thread-conversion hardware sold to municipal fire services, industrial facilities, commercial buildings and oil & gas operators. It covers product type, material, end-user and sales channel across five major regions. This analysis does not cover fire hoses, nozzles, pump systems, sprinkler heads, fire extinguishers or passive fire protection materials as standalone markets.
How big is the market for Fire Adapters Market?
The Fire Adapters Market is most defensibly sized near 454 Million in 2025, with a forward CAGR in the 7–9% band, converging toward 7.9% when weighted against adjacent fire hose and fire protection system growth. The table below compares plausible benchmark anchors and their scope definitions.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
454 Million
2025
2031
7.9%
Adapters and couplings for hoses, hydrants, nozzles
Synthesized consensus estimate
576 Million
2026
2034
5.8%
Fire hoses (adjacent category, not adapters)
Published market estimate
85.6 Billion
2024
2035
8.21%
Total fire protection systems, all products
Published market estimate
>7% CAGR
2025
2030
7.0%
Fire protection materials, all categories
Published market estimate
Our analysis suggests the 5.8% fire-hose CAGR is a soft floor rather than a direct proxy: adapters are increasingly specified in industrial retrofit and oil & gas fire-safety projects, which run above the hose replacement cycle. The result is a growth premium for adapters over plain hose demand.
How is the market segmented?
The Fire Adapters Market segments primarily by product form, material of construction, end-user and sales channel. Product and material segments carry the most pricing leverage; end-user segments dictate certification requirements.
Municipal Fire Service, Industrial (Oil & Gas, Chemicals, Power), Commercial, Residential, Forestry and Wildland
By Sales Channel
Direct OEM, Distribution and Dealer, Municipal Tender
By Pressure Rating
Low Pressure, Medium Pressure, High Pressure
Aluminum alloy adapters dominate volume on account of weight and corrosion resistance, while brass retains specification preference in saltwater and heavy-industrial environments. Our analysis suggests composite adapters will be the fastest-growing material sub-segment through 2031, particularly in wildland and forestry applications where weight reduction is mission-critical.
Which region leads in Fire Adapters Market?
North America leads the Fire Adapters Market with an estimated 34% value share in 2025, followed by Asia-Pacific at 29% and Europe at 23%. Asia-Pacific is the fastest-growing region, pacing above the global 7.9% CAGR.
Fire Adapters Market Regional Market Share
Loading chart...
Fire Adapters Market Regional Market Share
Region
Market Share (%)
North America
0.34%
Europe
0.23%
Asia-Pacific
0.29%
Latin America
0.07%
Middle East & Africa
0.07%
Region
Value Share (2025)
North America
34%
Asia-Pacific
29%
Europe
23%
Latin America
7%
Middle East & Africa
7%
North America (USA, Canada, Mexico)
USA, Canada, Mexico
Europe (Germany, UK, France, Italy, Spain, Nordics)
Germany, UK, France, Italy, Spain, Nordics
Asia-Pacific (China, Japan, India, South Korea, Southeast Asia, Australia)
China, Japan, India, South Korea, Southeast Asia, Australia
Latin America (Brazil, Mexico, Argentina, Chile)
Brazil, Mexico, Argentina, Chile
Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey)
Saudi Arabia, UAE, South Africa, Turkey
The North American lead is structural: NFPA service-test culture, dense municipal hydrant networks and a large installed base of legacy thread standards all reinforce adapter demand. Asia-Pacific growth is investment-led, with refinery, port and industrial park buildouts in China, India and Indonesia driving specification of new adapter families.
What is driving growth — and what is holding it back?
Growth is driven by industrial fire-safety investment, tightening code enforcement and the need to physically bridge incompatible legacy thread systems. Restraints center on commodity price volatility and the low switching costs of undifferentiated adapters, which invite substandard imports.
Factor
Direction
Evidence Strength
Mechanism
Oil & gas fire-safety investment
Positive
High
New facilities require certified adapters at hydrant and hose stations
Code enforcement (NFPA, EN, ISO)
Positive
High
Service-test regimes drive replacement and certified procurement
Legacy thread incompatibility
Positive
Medium
Cross-standard conversions sustain adapter demand in retrofit
Industrialization in Asia-Pacific
Positive
High
Greenfield plants specify full fire-water infrastructure
Aluminum and brass price volatility
Negative
Medium
Margin compression and project deferrals
Low-cost non-certified imports
Negative
Medium
Price erosion in commodity adapter tiers
Skilled installer availability
Negative
Low
Slower commissioning in remote industrial sites
The balance favors growth. Our analysis suggests the negative factors are cyclical or segment-specific, while code enforcement and industrial capex are structural. The strongest counter-signal is procurement substitution toward low-cost imports in price-sensitive municipal tenders.
Who are the leading vendors?
The Fire Adapters Market is moderately fragmented: a small group of global fire-equipment suppliers anchors institutional and industrial specifications, while regional fabricators serve local distribution. Differentiation rests on certification breadth, alloy quality and thread-standard coverage.
Company
Positioning
Notable Strength
Angus Fire (UK)
Global firefighting equipment
High-performance hose and coupling systems, offshore approvals
Kuriyama of America
North American distribution
Premium hose assemblies and couplings for municipal and industrial use
Dixon Valve & Coupling
Industrial fittings
Broad coupling and adapter catalogue, cross-industry reach
Mercedes Textiles
Canadian manufacturer
Fire hose, fittings and portable pumps; expanded North American footprint
Jakob Eschbach GmbH
German precision fittings
Storz and thread-standard adapters for European markets
Guardian Fire Equipment
Regional fire equipment
Municipal tender supply and service network
National Fire Equipment
Regional supply
Hydrant and hose adapter assemblies
Richards Hose Ltd
Hose and fittings
Industrial and marine adapter lines
Our analysis suggests the strongest moat is standards coverage: vendors able to supply certified adapters across multiple thread systems (NST, Storz, BSP, GOST) win cross-border industrial projects where mixed equipment inventories are common. Pure price competitors remain confined to single-country distribution.
What do buyers and operators need to know?
Adapter selection is a mission-critical decision because the fitting is the single point of failure between a pressurized source and the fireground. Buyers should prioritize pressure-rated certification, alloy traceability and thread-standard match over unit price. A failed adapter can disable an entire hose line during an incident.
Procurement risk concentrates in three areas: counterfeit or non-certified imports, mismatched thread standards between mutual-aid departments, and inadequate corrosion resistance in coastal or chemical environments. Switching costs are low at the component level but high at the system level, because changing adapter families can require re-coupling an entire hose inventory. Regulatory compliance with NFPA, EN and ISO service-test requirements should be contractually enforced. This overview cannot substitute for sub-segment-level certification mapping, which the full report provides.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a cautiously bullish posture on the Fire Adapters Market. A 7.9% CAGR is credible because it sits between the slower fire-hose replacement cycle and the faster fire protection systems growth rate, and because industrial fire-safety capex is structurally rising. The strongest counter-argument is that commodity adapter pricing could deflate faster than volume grows, capping revenue growth in price-sensitive markets. We judge this a margin risk rather than a volume risk.
Our analysis suggests the real strategic battleground is certification and standards breadth, not manufacturing capacity. Vendors that can document multi-standard compliance will capture industrial and cross-border municipal demand, while undifferentiated fabricators face margin compression. Buyers should treat supplier qualification as a risk-management function, not a purchasing formality.
Actionable Strategy
Vendors: Prioritize multi-standard certification (NFPA, EN, ISO) and alloy traceability to capture industrial and oil & gas specification wins and defend price premiums.
Buyers and operators: Standardize adapter families across mutual-aid networks to eliminate thread mismatch failure modes and reduce inventory complexity.
Investors: Favor suppliers with certification breadth and industrial end-user exposure over commodity municipal-tender specialists.
What would change our conclusion: a sustained collapse in aluminum and brass prices combined with accelerated low-cost import penetration would compress the value CAGR below 6%, shifting the outlook from bullish to neutral. Conversely, a major regulatory tightening on adapter service-test documentation would accelerate replacement demand and push growth above 9%.
Fire Adapters Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Fire Adapters Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.9% from 2020-2034
Segmentation
By Product Type
Storz Adapters
Quick-Connect Adapters
Thread-Conversion Adapters
Reducers
Hose Couplings
Wye and Siamese Adapters
By Material
Aluminum Alloy
Brass
Stainless Steel
Ductile Iron
Composite
By End-User
Municipal Fire Service
Industrial
Commercial
Residential
Forestry and Wildland
By Sales Channel
Direct OEM
Distribution and Dealer
Municipal Tender
By Pressure Rating
Low Pressure
Medium Pressure
High Pressure
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Nordics
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Australia
Latin America
Brazil
Mexico
Argentina
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
Table of Contents
1. Fire Adapters Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Fire Adapters Market Executive Summary
2.1. Market Snapshot
3. Fire Adapters Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Fire Adapters Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Fire Adapters Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Storz Adapters
5.1.2. Quick-Connect Adapters
5.1.3. Thread-Conversion Adapters
5.1.4. Reducers
5.1.5. Hose Couplings
5.1.6. Wye and Siamese Adapters
5.2. Analysis, Insights and Forecast - by Material
5.2.1. Aluminum Alloy
5.2.2. Brass
5.2.3. Stainless Steel
5.2.4. Ductile Iron
5.2.5. Composite
5.3. Analysis, Insights and Forecast - by End-User
5.3.1. Municipal Fire Service
5.3.2. Industrial
5.3.3. Commercial
5.3.4. Residential
5.3.5. Forestry and Wildland
5.4. Analysis, Insights and Forecast - by Sales Channel
5.4.1. Direct OEM
5.4.2. Distribution and Dealer
5.4.3. Municipal Tender
5.5. Analysis, Insights and Forecast - by Pressure Rating
5.5.1. Low Pressure
5.5.2. Medium Pressure
5.5.3. High Pressure
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Fire Adapters Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. Storz Adapters
6.1.2. Quick-Connect Adapters
6.1.3. Thread-Conversion Adapters
6.1.4. Reducers
6.1.5. Hose Couplings
6.1.6. Wye and Siamese Adapters
6.2. Analysis, Insights and Forecast - by Material
6.2.1. Aluminum Alloy
6.2.2. Brass
6.2.3. Stainless Steel
6.2.4. Ductile Iron
6.2.5. Composite
6.3. Analysis, Insights and Forecast - by End-User
6.3.1. Municipal Fire Service
6.3.2. Industrial
6.3.3. Commercial
6.3.4. Residential
6.3.5. Forestry and Wildland
6.4. Analysis, Insights and Forecast - by Sales Channel
6.4.1. Direct OEM
6.4.2. Distribution and Dealer
6.4.3. Municipal Tender
6.5. Analysis, Insights and Forecast - by Pressure Rating
6.5.1. Low Pressure
6.5.2. Medium Pressure
6.5.3. High Pressure
7. Fire Adapters Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. Storz Adapters
7.1.2. Quick-Connect Adapters
7.1.3. Thread-Conversion Adapters
7.1.4. Reducers
7.1.5. Hose Couplings
7.1.6. Wye and Siamese Adapters
7.2. Analysis, Insights and Forecast - by Material
7.2.1. Aluminum Alloy
7.2.2. Brass
7.2.3. Stainless Steel
7.2.4. Ductile Iron
7.2.5. Composite
7.3. Analysis, Insights and Forecast - by End-User
7.3.1. Municipal Fire Service
7.3.2. Industrial
7.3.3. Commercial
7.3.4. Residential
7.3.5. Forestry and Wildland
7.4. Analysis, Insights and Forecast - by Sales Channel
7.4.1. Direct OEM
7.4.2. Distribution and Dealer
7.4.3. Municipal Tender
7.5. Analysis, Insights and Forecast - by Pressure Rating
7.5.1. Low Pressure
7.5.2. Medium Pressure
7.5.3. High Pressure
8. Fire Adapters Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. Storz Adapters
8.1.2. Quick-Connect Adapters
8.1.3. Thread-Conversion Adapters
8.1.4. Reducers
8.1.5. Hose Couplings
8.1.6. Wye and Siamese Adapters
8.2. Analysis, Insights and Forecast - by Material
8.2.1. Aluminum Alloy
8.2.2. Brass
8.2.3. Stainless Steel
8.2.4. Ductile Iron
8.2.5. Composite
8.3. Analysis, Insights and Forecast - by End-User
8.3.1. Municipal Fire Service
8.3.2. Industrial
8.3.3. Commercial
8.3.4. Residential
8.3.5. Forestry and Wildland
8.4. Analysis, Insights and Forecast - by Sales Channel
8.4.1. Direct OEM
8.4.2. Distribution and Dealer
8.4.3. Municipal Tender
8.5. Analysis, Insights and Forecast - by Pressure Rating
8.5.1. Low Pressure
8.5.2. Medium Pressure
8.5.3. High Pressure
9. Fire Adapters Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. Storz Adapters
9.1.2. Quick-Connect Adapters
9.1.3. Thread-Conversion Adapters
9.1.4. Reducers
9.1.5. Hose Couplings
9.1.6. Wye and Siamese Adapters
9.2. Analysis, Insights and Forecast - by Material
9.2.1. Aluminum Alloy
9.2.2. Brass
9.2.3. Stainless Steel
9.2.4. Ductile Iron
9.2.5. Composite
9.3. Analysis, Insights and Forecast - by End-User
9.3.1. Municipal Fire Service
9.3.2. Industrial
9.3.3. Commercial
9.3.4. Residential
9.3.5. Forestry and Wildland
9.4. Analysis, Insights and Forecast - by Sales Channel
9.4.1. Direct OEM
9.4.2. Distribution and Dealer
9.4.3. Municipal Tender
9.5. Analysis, Insights and Forecast - by Pressure Rating
9.5.1. Low Pressure
9.5.2. Medium Pressure
9.5.3. High Pressure
10. Fire Adapters Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. Storz Adapters
10.1.2. Quick-Connect Adapters
10.1.3. Thread-Conversion Adapters
10.1.4. Reducers
10.1.5. Hose Couplings
10.1.6. Wye and Siamese Adapters
10.2. Analysis, Insights and Forecast - by Material
10.2.1. Aluminum Alloy
10.2.2. Brass
10.2.3. Stainless Steel
10.2.4. Ductile Iron
10.2.5. Composite
10.3. Analysis, Insights and Forecast - by End-User
10.3.1. Municipal Fire Service
10.3.2. Industrial
10.3.3. Commercial
10.3.4. Residential
10.3.5. Forestry and Wildland
10.4. Analysis, Insights and Forecast - by Sales Channel
10.4.1. Direct OEM
10.4.2. Distribution and Dealer
10.4.3. Municipal Tender
10.5. Analysis, Insights and Forecast - by Pressure Rating
10.5.1. Low Pressure
10.5.2. Medium Pressure
10.5.3. High Pressure
11. Fire Adapters Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Fire Adapters Market Research Methodology
List of Figures
Figure 1: Fire Adapters Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Fire Adapters Market Revenue (Million), by Product Type 2026 & 2034
Figure 3: North America Fire Adapters Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Fire Adapters Market Revenue (Million), by Material 2026 & 2034
Figure 5: North America Fire Adapters Market Revenue Share (%), by Material 2026 & 2034
Figure 6: North America Fire Adapters Market Revenue (Million), by End-User 2026 & 2034
Figure 7: North America Fire Adapters Market Revenue Share (%), by End-User 2026 & 2034
Figure 8: North America Fire Adapters Market Revenue (Million), by Sales Channel 2026 & 2034
Figure 9: North America Fire Adapters Market Revenue Share (%), by Sales Channel 2026 & 2034
Figure 10: North America Fire Adapters Market Revenue (Million), by Pressure Rating 2026 & 2034
Figure 11: North America Fire Adapters Market Revenue Share (%), by Pressure Rating 2026 & 2034
Figure 12: North America Fire Adapters Market Revenue (Million), by Country 2026 & 2034
Figure 13: North America Fire Adapters Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Fire Adapters Market Revenue (Million), by Product Type 2026 & 2034
Figure 15: Europe Fire Adapters Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: Europe Fire Adapters Market Revenue (Million), by Material 2026 & 2034
Europe Fire Adapters Market Revenue Share (%), by Material 2026 & 2034
List of Tables
Table 1: Fire Adapters Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 2: Fire Adapters Market Revenue Million Forecast, by Material 2020 & 2034
Table 3: Fire Adapters Market Revenue Million Forecast, by End-User 2020 & 2034
Table 4: Fire Adapters Market Revenue Million Forecast, by Sales Channel 2020 & 2034
Table 5: Fire Adapters Market Revenue Million Forecast, by Pressure Rating 2020 & 2034
Table 6: Fire Adapters Market Revenue Million Forecast, by Region 2020 & 2034
Table 7: North America Fire Adapters Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 8: North America Fire Adapters Market Revenue Million Forecast, by Material 2020 & 2034
Table 9: North America Fire Adapters Market Revenue Million Forecast, by End-User 2020 & 2034
Table 10: North America Fire Adapters Market Revenue Million Forecast, by Sales Channel 2020 & 2034
Table 11: North America Fire Adapters Market Revenue Million Forecast, by Pressure Rating 2020 & 2034
Table 12: North America Fire Adapters Market Revenue Million Forecast, by Country 2020 & 2034
Table 13: USA Fire Adapters Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: Canada Fire Adapters Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 15: Mexico Fire Adapters Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Europe Fire Adapters Market Revenue Million Forecast, by Product Type 2020 & 2034
Frequently Asked Questions
1. What is the Fire Adapters Market size?
The global Fire Adapters Market was sized at 454 Million in 2025 and is projected to reach 716 Million by 2031, growing at a 7.9% CAGR. North America leads with 34% value share.
2. Which region leads the Fire Adapters Market?
North America leads with an estimated 34% value share in 2025, driven by NFPA enforcement and dense municipal hydrant networks. Asia-Pacific is the fastest-growing region at 29% share and rising.
3. What drives demand for fire adapters?
Industrial fire-safety investment, tightening code enforcement and legacy thread incompatibility drive demand. Oil & gas facility expansion and municipal service-test regimes are the strongest structural drivers.
4. Who are the leading fire adapter vendors?
Leading vendors include Angus Fire, Kuriyama of America, Dixon Valve & Coupling, Mercedes Textiles, Jakob Eschbach and Guardian Fire Equipment. Differentiation rests on certification breadth and thread-standard coverage.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the fire adapter value chain, including aluminum and brass alloy suppliers, specialized adapter and coupling producers, contract machining and finishing firms, and global and regional fire-equipment distributors. Interviews targeted decision-makers with direct specification authority: VP of Sourcing, Heads of R&D and Product Engineering, Technical Directors for fire safety, and Commercial Operations Leads in municipal and industrial channels. Fieldwork captured pressure-rating practices, certification pathways and tender dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Directors
35%
R&D and Product Engineering Heads
30%
Technical & Fire Safety Directors
25%
Commercial Operations Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Alloy & Raw Material Suppliers
30%
Adapter & Coupling Manufacturers
40%
Distributors & Municipal Suppliers
30%
Secondary Benchmarking & Public Trade Validation
Findings were validated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases, and recognized technical standards and industry associations. No third-party market research publisher data was used as a primary validation source.
Demand Modeling & Market Sizing Triangulation
Market sizing used simultaneous top-down and bottom-up triangulation. The top-down model allocated macroeconomic fire-protection spending across end-user segments and regions. The bottom-up model estimated manufacturer capacity, product pricing and end-use consumption by adapter family, reconciling the two to a consensus base-year value.


 Fire Adapters Market