Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Electrical Resistor Market Size, Share & Growth to 2030
Electrical Resistor Market
Electrical Resistor Market Size, Share & Growth to 2030
Electrical Resistor Market by Type (Surface-Mount Chip Resistors, Network/Array Resistors, Shunt & Current-Sense Resistors, Wirewound Resistors, Variable Resistors), by Power Rating (Below 1/8 W, 1/8-1 W, 1-5 W, Above 5 W), by Application (Electric Motor, Driver, Inverter, Sensing & Termination, Others), by End-User (Automotive, Consumer Electronics, Telecommunications & Data Infrastructure, Industrial, Aerospace & Defense, Medical Devices), by Asia Pacific (China, Japan, South Korea, India, Taiwan, Southeast Asia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0
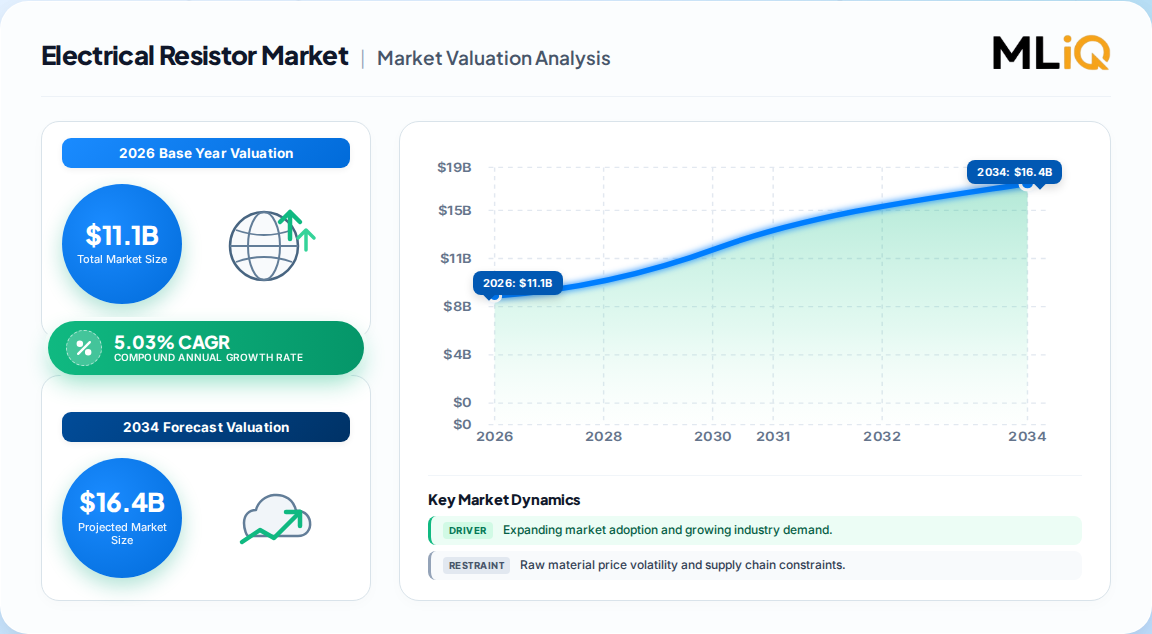
The global Electrical Resistor Market was sized at roughly 10.57 Billion in 2025 and 11.10 Billion in 2026, on a medium-concentration global footprint.
Forecast growth runs at 5.03% CAGR to 2031, reaching about 14.19 Billion in value terms.
Surface-mount chip resistors led type segments at 38.22% share in 2025; shunt and current-sense parts grow fastest at 6.49% CAGR.
Automotive is the fastest end-user at 6.74% CAGR; resistors above 5 W grow at 6.67% CAGR through 2031.
Asia-Pacific dominates with 55.42% of 2025 revenue and advances at 5.62% CAGR through the forecast window.
Key players include Yageo, Vishay Intertechnology, Murata, Panasonic Industry and KOA Corporation.
Why this matters for decision-makers: Automotive-grade, ultra-low-ohmic shunt capacity — not generic chip volume — will decide who captures the electrification premium before price competition compresses mainstream chip margins.
Electrical Resistor Market Size (In Billion)
15.0B
10.0B
5.0B
0
10.57 B
2025
11.10 B
2026
11.66 B
2027
12.24 B
2028
12.86 B
2029
13.51 B
2030
14.19 B
2031
Electrical Resistor Market Size (In Billion)
Year
Market Size
2025
10.57 B
2026
11.10 B
2027
11.66 B
2028
12.24 B
2029
12.86 B
2030
13.51 B
2031
14.19 B
What is the Electrical Resistor Market?
The Electrical Resistor Market covers passive two-terminal components that limit current, divide voltage and terminate signals inside electronic circuits. It spans fixed, variable and non-linear types across chip, through-hole and power formats, sold into consumer electronics, automotive, industrial, telecom and medical systems, measured by manufacturer-level revenue.
Scope: what this report covers and excludes
This analysis covers globally traded resistors by type, power rating, application and end-user industry, with revenue measured at manufacturer level for the 2025 base year and forecast to 2031. It includes surface-mount chip, network/array, shunt/current-sense, wirewound and variable formats. This analysis does not cover thermistors, varistors, integrated passive networks, or the passive-component distribution channel's resale margins.
How big is the market for Electrical Resistor Market?
Estimates cluster between roughly 5.8 Billion and 11.1 Billion, a spread that reflects scope, not disagreement about demand. The gap is definitional: narrower studies exclude shunts and power-resistor formats.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
5.83 Billion
2023
2030
5.9%
Fixed, variable and non-linear resistors; conservative format scope
One published estimate
6.6 Billion
2025
2034
4.65%
Product plus application split; motor and inverter-led
A competing analysis
11.10 Billion
2026
2035
5.03%
Chip, array and shunt formats across all end-users
A competing analysis
10.76 Billion
2026
2035
3.65%
Type and application led, includes power-handling parts
A competing analysis
Our analysis suggests the 11.10 Billion framing is the most defensible for procurement and investment decisions. It explicitly counts shunt and current-sense resistors, the fastest-growing format at 6.49% CAGR, and captures automotive electrification content that narrower definitions omit. The lower 3.65% CAGR likely builds in heavier average-selling-price erosion from East Asian capacity additions.
How is the market segmented?
Segments split along four non-geographic axes, and the fastest growth sits away from the largest volume pools. Chip resistors supply scale; shunts, high-power parts and automotive grades supply margin.
Electric motor, driver, inverter, sensing/termination, others
Motor and inverter dominate volume
By End-User
Automotive, consumer electronics, telecom and data infrastructure, industrial, aerospace and defense, medical
Automotive fastest at 6.74% CAGR
Which region leads in Electrical Resistor Market?
Asia-Pacific leads the Electrical Resistor Market with 55.42% of 2025 revenue, advancing at 5.62% CAGR through 2031 on concentrated manufacturing and component capacity in China, Japan, South Korea and Taiwan.
Electrical Resistor Market Regional Market Share
Loading chart...
Electrical Resistor Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.55%
North America
0.18%
Europe
0.17%
South America
0.05%
Middle East & Africa
0.05%
Asia-Pacific
China
Japan
South Korea
India
Taiwan
Southeast Asia
North America
United States
Canada
Mexico
Europe
Germany
United Kingdom
France
Italy
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Region
2025 share
Growth posture
Asia-Pacific
55.42%
Capacity-led, price-competitive
North America
18%
Fastest-growing demand region
Europe
17%
Automotive and industrial qualification driven
Latin America
5%
Emerging assembly demand
Middle East & Africa
5%
Infrastructure and power led
This divergence implies buyers face a structural imbalance: supply concentrates in Asia-Pacific while premium demand concentrates in North America and Europe. That mismatch raises freight, tariff and dual-sourcing risk for automotive and defense programs, and rewards vendors with qualified non-Asian capacity.
What is driving growth — and what is holding it back?
Automotive electronics content is the strongest driver, adding roughly 1.2 percentage points to CAGR, followed by consumer and IoT volumes at about 0.9 points. Miniaturization and 5G add 0.6 and 0.7 points respectively.
Factor
Direction
Evidence strength
Mechanism
Automotive electronics per vehicle
Driver
High
Shunts and AEC-Q200 parts in BMS, ADAS, inverters
Consumer and IoT volumes
Driver
High
0402/0201 migration raises unit counts
5G and high-frequency rollout
Driver
Medium
Thin-film termination networks to 50 GHz
Miniaturization
Driver
High
Dense PCB footprints demand smaller chips
East Asian capacity additions
Restraint
Medium
Price competition compresses mainstream ASPs
Raw-material volatility
Restraint
Medium
Metal and substrate cost swings hit margins
On balance, the drivers outrun the restraints, but unevenly. Our analysis suggests the restraint operates almost entirely in commodity chip formats, while the drivers pull value toward automotive-grade and high-power parts — widening the margin gap between commodity and specialty suppliers.
Who are the leading vendors?
Competition is medium-concentrated, with five suppliers shaping global supply and qualification standards. Moats rest on automotive qualification, multi-site redundancy and thin-film process depth rather than raw scale.
Vendor
Core strength
Notable positioning
Yageo Corporation
Broad chip portfolio and scale
Volume leadership in surface-mount formats
Vishay Intertechnology
Precision, power and shunt devices
Strong automotive and industrial reach
Murata Manufacturing
Miniaturized components
High-volume consumer and telecom supply
Panasonic Industry
Films and reliability grades
Automotive and energy applications
KOA Corporation
Automotive-grade resistors
Tight-tolerance niche strength
Differentiation is shifting from cost to qualification. Suppliers holding AEC-Q200 approval and documented drift below ±15 ppm/°C enjoy design wins that persist for full model cycles, converting what looks like a commodity market into a multi-year revenue annuity.
What do buyers and operators need to know? (Decision Support)
Selection now hinges on tolerance drift, thermal performance up to 170 °C and supply-chain resilience, not headline price. Automotive and medical buyers should demand documented AEC-Q200 or equivalent qualification, multi-site manufacturing redundancy and lot traceability before awarding volume contracts.
Procurement risk is concentrated in single-region sourcing. With 55% of supply in Asia-Pacific, tariff shifts, logistics disruption or capacity reallocation can delay qualified parts. Switching costs are high: requalification cycles typically run several quarters, and design changes force PCB redesigns. Buyers should therefore lock dual-source agreements and pre-qualify high-power and shunt formats early rather than at peak demand.
Regulatory compliance adds friction. RoHS and halogen-free requirements, plus automotive zero-defect targets, narrow the approved vendor list and support price premiums for compliant suppliers.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-migration thesis. Unit growth is real but modest, held near 5% by price erosion in commodity chips; the money is moving toward shunts, high-power parts and automotive-qualified formats growing above 6.5%. Vendors who stay anchored in generic 0402 chip volume will face margin compression even as revenue rises.
The strongest counter-argument is that capacity additions in East Asia could deflate pricing faster than premium mix improves, dragging blended CAGR toward the 3.65% low estimate. We consider this unlikely to dominate, because automotive qualification creates switching friction that shields specialty pricing. The divergence between estimates is a scope story, not a demand story.
Investors should prioritize suppliers with automotive-grade shunt capacity and non-Asian qualified production footprints.
Operators should pre-qualify dual sources for above-5 W and current-sense parts before the next EV design cycle locks in.
Distributors should shift inventory toward thin-film and precision formats where ASPs are holding.
Evidence that would change our conclusion: sustained double-digit price declines in automotive-grade shunts, or a slowdown in EV platform launches that cuts shunt content per vehicle.
Electrical Resistor Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Electrical Resistor Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.03% from 2020-2034
Segmentation
By Type
Surface-Mount Chip Resistors
Network/Array Resistors
Shunt & Current-Sense Resistors
Wirewound Resistors
Variable Resistors
By Power Rating
Below 1/8 W
1/8-1 W
1-5 W
Above 5 W
By Application
Electric Motor
Driver
Inverter
Sensing & Termination
Others
By End-User
Automotive
Consumer Electronics
Telecommunications & Data Infrastructure
Industrial
Aerospace & Defense
Medical Devices
By Geography
Asia Pacific
China
Japan
South Korea
India
Taiwan
Southeast Asia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Electrical Resistor Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Electrical Resistor Market Executive Summary
2.1. Market Snapshot
3. Electrical Resistor Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Electrical Resistor Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Electrical Resistor Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Surface-Mount Chip Resistors
5.1.2. Network/Array Resistors
5.1.3. Shunt & Current-Sense Resistors
5.1.4. Wirewound Resistors
5.1.5. Variable Resistors
5.2. Analysis, Insights and Forecast - by Power Rating
5.2.1. Below 1/8 W
5.2.2. 1/8-1 W
5.2.3. 1-5 W
5.2.4. Above 5 W
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Electric Motor
5.3.2. Driver
5.3.3. Inverter
5.3.4. Sensing & Termination
5.3.5. Others
5.4. Analysis, Insights and Forecast - by End-User
5.4.1. Automotive
5.4.2. Consumer Electronics
5.4.3. Telecommunications & Data Infrastructure
5.4.4. Industrial
5.4.5. Aerospace & Defense
5.4.6. Medical Devices
5.5. Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. North America
5.5.3. Europe
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Electrical Resistor Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Surface-Mount Chip Resistors
6.1.2. Network/Array Resistors
6.1.3. Shunt & Current-Sense Resistors
6.1.4. Wirewound Resistors
6.1.5. Variable Resistors
6.2. Analysis, Insights and Forecast - by Power Rating
6.2.1. Below 1/8 W
6.2.2. 1/8-1 W
6.2.3. 1-5 W
6.2.4. Above 5 W
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Electric Motor
6.3.2. Driver
6.3.3. Inverter
6.3.4. Sensing & Termination
6.3.5. Others
6.4. Analysis, Insights and Forecast - by End-User
6.4.1. Automotive
6.4.2. Consumer Electronics
6.4.3. Telecommunications & Data Infrastructure
6.4.4. Industrial
6.4.5. Aerospace & Defense
6.4.6. Medical Devices
7. Electrical Resistor Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Surface-Mount Chip Resistors
7.1.2. Network/Array Resistors
7.1.3. Shunt & Current-Sense Resistors
7.1.4. Wirewound Resistors
7.1.5. Variable Resistors
7.2. Analysis, Insights and Forecast - by Power Rating
7.2.1. Below 1/8 W
7.2.2. 1/8-1 W
7.2.3. 1-5 W
7.2.4. Above 5 W
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Electric Motor
7.3.2. Driver
7.3.3. Inverter
7.3.4. Sensing & Termination
7.3.5. Others
7.4. Analysis, Insights and Forecast - by End-User
7.4.1. Automotive
7.4.2. Consumer Electronics
7.4.3. Telecommunications & Data Infrastructure
7.4.4. Industrial
7.4.5. Aerospace & Defense
7.4.6. Medical Devices
8. Electrical Resistor Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Surface-Mount Chip Resistors
8.1.2. Network/Array Resistors
8.1.3. Shunt & Current-Sense Resistors
8.1.4. Wirewound Resistors
8.1.5. Variable Resistors
8.2. Analysis, Insights and Forecast - by Power Rating
8.2.1. Below 1/8 W
8.2.2. 1/8-1 W
8.2.3. 1-5 W
8.2.4. Above 5 W
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Electric Motor
8.3.2. Driver
8.3.3. Inverter
8.3.4. Sensing & Termination
8.3.5. Others
8.4. Analysis, Insights and Forecast - by End-User
8.4.1. Automotive
8.4.2. Consumer Electronics
8.4.3. Telecommunications & Data Infrastructure
8.4.4. Industrial
8.4.5. Aerospace & Defense
8.4.6. Medical Devices
9. Electrical Resistor Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Surface-Mount Chip Resistors
9.1.2. Network/Array Resistors
9.1.3. Shunt & Current-Sense Resistors
9.1.4. Wirewound Resistors
9.1.5. Variable Resistors
9.2. Analysis, Insights and Forecast - by Power Rating
9.2.1. Below 1/8 W
9.2.2. 1/8-1 W
9.2.3. 1-5 W
9.2.4. Above 5 W
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Electric Motor
9.3.2. Driver
9.3.3. Inverter
9.3.4. Sensing & Termination
9.3.5. Others
9.4. Analysis, Insights and Forecast - by End-User
9.4.1. Automotive
9.4.2. Consumer Electronics
9.4.3. Telecommunications & Data Infrastructure
9.4.4. Industrial
9.4.5. Aerospace & Defense
9.4.6. Medical Devices
10. Electrical Resistor Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Surface-Mount Chip Resistors
10.1.2. Network/Array Resistors
10.1.3. Shunt & Current-Sense Resistors
10.1.4. Wirewound Resistors
10.1.5. Variable Resistors
10.2. Analysis, Insights and Forecast - by Power Rating
10.2.1. Below 1/8 W
10.2.2. 1/8-1 W
10.2.3. 1-5 W
10.2.4. Above 5 W
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Electric Motor
10.3.2. Driver
10.3.3. Inverter
10.3.4. Sensing & Termination
10.3.5. Others
10.4. Analysis, Insights and Forecast - by End-User
Table 16: Southeast Asia Electrical Resistor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the electrical resistor market in 2026?
The global Electrical Resistor Market is estimated at 11.10 Billion in 2026, up from roughly 10.57 Billion in 2025. Broader definitions including shunt and power formats reach this figure; narrower studies focusing only on fixed and variable types report lower values.
2. What is the growth rate of the electrical resistor market?
Published estimates place CAGR at 5.03% through 2031, reaching about 14.19 Billion. Alternative analyses span 3.65% to 5.9% depending on whether commodity chip price erosion is weighted heavily and which resistor formats are counted.
3. Which region dominates the electrical resistor market?
Asia-Pacific leads with 55.42% of 2025 revenue, driven by concentrated manufacturing in China, Japan, South Korea and Taiwan. North America is the fastest-growing demand region as automotive and data-infrastructure content expands.
4. Which segment grows fastest in the electrical resistor market?
Shunt and current-sense resistors grow fastest by type at 6.49% CAGR, while automotive is the fastest end-user at 6.74%. Resistors above 5 W also outpace the market at 6.67% CAGR through 2031.
5. Who are the leading companies in the electrical resistor market?
Key vendors include Yageo Corporation, Vishay Intertechnology, Murata Manufacturing, Panasonic Industry and KOA Corporation. Competition is medium-concentrated, with moats built on automotive qualification, thin-film process depth and multi-site supply redundancy.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a deliberate 70/30 primary-to-secondary split, prioritizing direct validation over published benchmarks. Structured interviews and in-depth sessions were conducted across the full resistor value chain with resistive-material and substrate suppliers, specialty component manufacturers, contract assembly houses, and global authorized distributors. Within these organizations we engaged decision-makers holding specific authority over component specification and sourcing, including VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Managers. Interviews probed qualification thresholds, tolerance drift expectations, price negotiation dynamics, and sourcing resilience, anchoring our demand assumptions in verified operator behavior rather than modeled inference.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
35%
R&D & Technical Directors
30%
Commercial Operations Managers
20%
Quality & Compliance Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Resistive Material & Substrate Suppliers
40%
Resistor Manufacturers
35%
Contract Assembly & OEM Buyers
15%
Global Distributors
10%
Secondary Benchmarking & Public Trade Validation
Findings were triangulated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings, 10-K and SEC disclosures, investor presentations, and patent databases tracking thin-film and shunt geometries. Recognized non-profit technical standards bodies and industry associations were consulted for qualification and compliance parameters. No competitor research publications informed the sizing framework.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic electronics output and end-market spend across resistor formats; the bottom-up path models manufacturer capacity, wafer and chip production volume, product pricing, and end-use consumption by industry. Convergence of both paths sets the base-year valuation.


 Electrical Resistor Market