Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Capacitive Touch Screen Market Outlook 2026
Capacitive Touch Screen Market
Capacitive Touch Screen Market Outlook 2026
Capacitive Touch Screen Market by Technology (Capacitive, Resistive, Surface Acoustic Wave, Infrared, Optical), by Display Size (Below 5 inch, 5-10 inch, 10-27 inch, 28-65 inch, Above 65 inch), by End-User Industry (Consumer Electronics, Automotive, Retail & POS, Industrial & Manufacturing, Healthcare, Education, Corporate & Enterprise, Hospitality), by Touch Points (Single-touch, Multi-touch), by Interface (I2C, SPI, USB, UART), by Product Form (Smartphones, Tablets, Laptops, Televisions, Kiosks, Large Interactive Screens, Wearables), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Taiwan), by Latin America (Brazil, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0
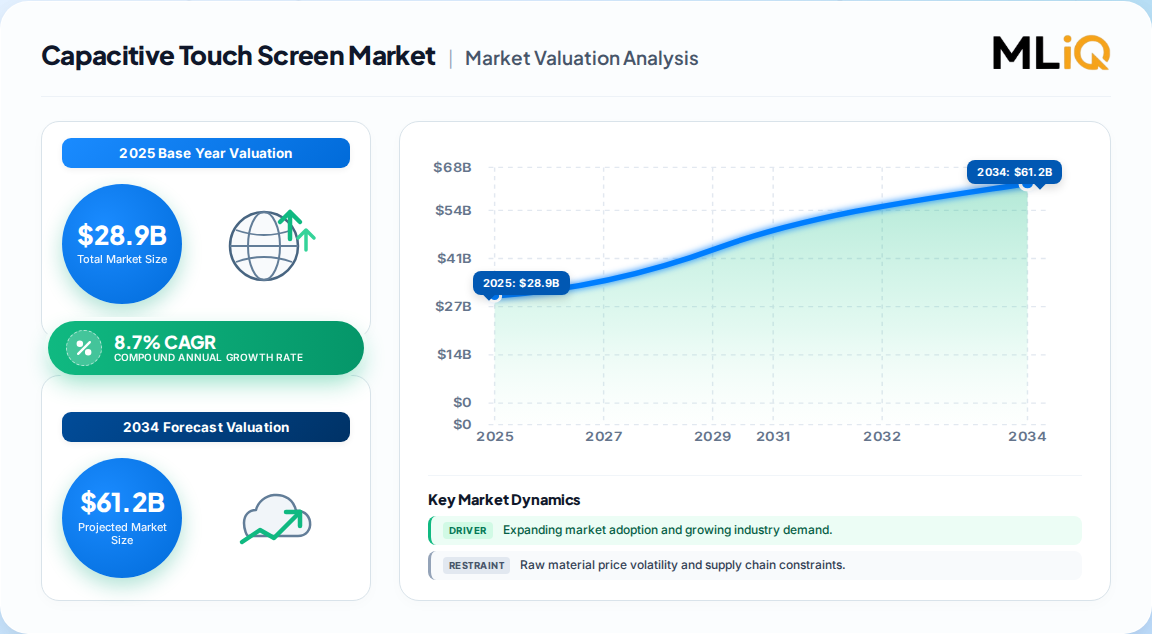
The global capacitive touch screen market was valued at approximately 28.9 Billion in 2025, representing the largest single technology segment within the broader touch display industry.
Forecast growth of 8.7% CAGR (2025–2031) puts the segment on track to exceed 47 Billion by 2031, driven by smartphone, automotive, and commercial interactive display demand.
Capacitive technology commands an estimated 41–43% share of total touch technology revenue, consistently outranking resistive, SAW, and infrared alternatives.
Asia-Pacific leads with roughly 42% of global capacitive revenue, anchored by China, South Korea, Japan, and Taiwan manufacturing ecosystems.
Leading players include Samsung Display, LG Display, BOE Technology, Elo Touch Solutions, NXP Semiconductors, Microchip Technology, and Synaptics, though concentration varies sharply by layer (panel vs. controller IC).
Display-size migration toward 5–10 inch and >10 inch panels is accelerating; the >10 inch class is forecast to grow at ~10.1% CAGR through 2031.
Why this matters for decision-makers: Vendors and buyers must pivot toward automotive-grade PCAP and large-format commercial displays, where ASP erosion from consumer panel commoditization is less severe and margin preservation is achievable.
Capacitive Touch Screen Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
28.90 B
2025
31.40 B
2026
34.20 B
2027
37.10 B
2028
40.40 B
2029
43.90 B
2030
47.70 B
2031
Capacitive Touch Screen Market Size (In Billion)
Year
Market Size
2025
28.90 B
2026
31.40 B
2027
34.20 B
2028
37.10 B
2029
40.40 B
2030
43.90 B
2031
47.70 B
What is the Capacitive Touch Screen Market?
The capacitive touch screen market encompasses the design, manufacture, and integration of displays that detect touch through changes in electrical capacitance, typically using projected capacitive (PCAP) sensing. It covers panel modules, touch controller ICs, and finished displays used across smartphones, tablets, automotive infotainment, commercial kiosks, medical devices, and industrial HMIs.
Scope: what this report covers and excludes
This analysis covers capacitive touch screen panels and modules across consumer electronics, automotive, commercial, industrial, healthcare, and retail applications, spanning all major display sizes and geographies. This analysis does not cover resistive, surface acoustic wave, infrared, or optical touch technologies except where cited for comparative context, nor does it cover adjacent component markets such as cover glass, display driver ICs outside touch functionality, or raw indium tin oxide supply chains.
How big is the market for Capacitive Touch Screen Market?
Capacitive touch screens represent the dominant and most commercially significant technology layer within the broader touch display ecosystem, with revenue estimates converging on the high-20-billion-dollar range for 2025. Several published analyses measure overlapping but differently bounded markets, which explains the variance in headline figures.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
~28.9 Billion
2025
2031
8.7%
Capacitive segment share of total touch screen display market (USD 79.1B in 2026, growing to USD 120B by 2031)
One published industry estimate
~31.0 Billion
2025
2031
~9.0%
Capacitive share of commercial and consumer touch display spend
A competing analysis
~4.4 Billion (controllers only)
2025
2031
8.4%
Touch controller ICs for capacitive panels (71.1% of a USD 8.69B controller market)
A competing analysis
~7.1 Billion
2025
2034
10.2%
Capacitive share of multi-touch screen market (USD 16.5B in 2025)
A competing analysis
Our analysis suggests the ~28.9 Billion figure is the most defensible for total capacitive display revenue, because it aligns with the 41–43% technology share observed across multiple overlapping datasets (touch display market at USD 79.1B in 2026, commercial touch display at USD 6.9B in 2025, multi-touch screen at USD 16.5B in 2025). The controller-IC figure is not comparable — it measures a component, not the panel or module. Buyers should normalize on the panel-plus-module definition to avoid conflating component markets with finished display markets.
How is the market segmented?
Segmentation follows four axes: touch technology, display size, end-user industry, and interface/controller type. The table below renders only the primary non-geographic parent segments and their children.
Smartphones, Tablets, Laptops, Televisions, Kiosks, Large Interactive Screens, Wearables
Capacitive technology's dominance is structural rather than cyclical: it is the only touch technology that simultaneously delivers multi-touch gesture recognition, optical clarity in glass-fronted designs, and glove/harsh-environment compatibility via tuned firmware.
Which regions lead in the Capacitive Touch Screen Market?
Asia-Pacific leads the global capacitive touch screen market with approximately 42% of revenue, underpinned by dense display fabrication, controller IC design, and final device assembly in China, South Korea, Japan, Taiwan, and Vietnam. North America and Europe follow with roughly 27% and 21% respectively, driven by commercial, automotive, and healthcare deployments.
Automotive (German OEMs), retail digital signage, industrial automation
Middle East & Africa
6%
Smart-city kiosks, self-checkout, public transit wayfinding
South America
4%
Retail POS, education deployments
The regional hierarchy that matters for planning is:
Asia-Pacific → China, South Korea, Japan, Taiwan, India, Vietnam
North America → United States, Canada, Mexico
Europe → Germany, UK, France, Italy, Spain, Eastern Europe
Middle East & Africa → UAE, Saudi Arabia, South Africa
South America → Brazil, Argentina, Chile
Our analysis suggests the MEA region is the fastest-compounding opportunity, with ~10% CAGR through 2031, as self-checkout and smart-city programs scale from a small base. Asia-Pacific remains the largest but also the most price-competitive, which implies margin expansion opportunities lie in automotive and commercial segments outside APAC.
What is driving growth — and what is holding it back?
Growth is balanced between a strong consumer-electronics base and rapidly accelerating automotive and commercial demand, but supply-chain and pricing headwinds cap the near-term upside. The net effect is a steady ~8.7% CAGR rather than a boom cycle.
Factor
Direction
Evidence Strength
Mechanism
Multi-touch PCAP adoption in foldable/OLED smartphones
Driver
High
+2.3% CAGR impact; forces complex touch-channel routing and palm rejection
This divergence between high-growth demand drivers and margin-compressing supply realities implies a two-tier market: premium automotive and medical segments will command healthier pricing, while consumer panel pricing continues to compress. Buyers must plan for component availability risk in 55nm controller IP and design for EMI resilience from day one.
Who are the leading vendors?
The competitive landscape is layered. Panel/module suppliers and controller-IC vendors serve different buying centers and face different moats, so a single list would mislead procurement teams.
Company
Layer
Primary Strength
Competitive Moat
Samsung Display
Panel/module
OLED and flexible smartphone panels
Scale, materials IP, OEM relationships
LG Display
Panel/module
OLED automotive and premium displays
Transparent OLED, automotive design wins
BOE Technology Group
Panel/module
Large-format LCD and commercial displays
Cost leadership, capacity scale
Elo Touch Solutions
Finished commercial displays
Retail, POS, kiosk systems
Vertical integration, installed base, software
NXP Semiconductors
Controller IC
Automotive-grade PCAP controllers
AEC-Q100 portfolio, ±15dB SNR advantage
Microchip Technology
Controller IC
Broad PCAP controller family
Ecosystem breadth, firmware tooling
Synaptics
Controller IC
Touch and display driver integration (TDDI)
IP portfolio, mobile OEM design ins
Our analysis suggests the top five controller vendors collectively hold ~44% share, indicating a moderately concentrated market where long-term supply agreements and reference designs matter more than unit price alone. Panel-side concentration is higher, but vertical integration is blurring boundaries: panel makers that build controller capabilities in-house gain a structural cost advantage at the expense of merchant IC vendors.
What do buyers and operators need to know?
Mission-critical selection criteria have shifted from raw touch sensitivity to environmental resilience, firmware support longevity, and regulatory compliance. For automotive and medical buyers, AEC-Q100 qualification and IEC 60601 EMC compliance are non-negotiable gates — not differentiators. Buyers should verify the controller's ability to handle glove touch, wet conditions, and electromagnetic interference from adjacent power electronics, because these requirements are rarely visible on standard datasheets.
Procurement risk concentrates in two areas: controller-IC supply continuity (55nm mixed-signal wafer allocation remains constrained at least through 2027) and firmware IP litigation, which has already affected white-box tablet makers in India. Switching costs are high once a controller is designed into a product platform — typically 9–18 months of re-qualification, tooling, and certification cycles. Operators should lock in multi-year supply agreements with secondary-source qualification for any automotive or medical design.
Regulatory exposure is increasing. Buyers in the EU must plan for RoHS and REACH compliance in module materials, while US healthcare deployments face cybersecurity scrutiny over kiosk-embedded OS and payment hardware. Our analysis suggests procurement teams should treat controller firmware update cadence and vendor EOL policies as primary scoring criteria, not secondary considerations.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a selective-growth thesis: the capacitive touch screen market is expanding steadily at ~8.7% CAGR, but the growth is uneven — automotive and large-format commercial segments expand at double-digit rates while consumer smartphone panels face structural margin compression. Investors and operators who treat the market as a single undifferentiated opportunity will systematically overpay for consumer exposure and underinvest in the segments where pricing power is actually improving.
The strongest counter-argument is that ASP erosion across consumer panels could be faster than new segment growth, creating a volume-up-value-flat scenario. This risk is real — panel-maker vertical integration and Chinese capacity expansion have compressed prices historically — but the data show that automotive segments (>10% CAGR) and large-format commercial displays (>10% CAGR) are large enough by 2031 to offset consumer erosion. The argument fails only if automotive adoption stalls, which current ADAS and infotainment trajectories do not support.
Actionable Strategy:
For investors: Prioritize exposure to controller-IC vendors with automotive qualification and firmware IP, where pricing power and switching costs create durable moats.
For operators: Shift procurement toward multi-year supply agreements for automotive/medical designs and qualify secondary controller sources to mitigate 55nm wafer allocation risk.
For product teams: Design capacitive interfaces for the >10 inch and industrial/harsh-environment classes, where ASP erosion is slower and differentiation through firmware and haptics is achievable.
The evidence that would change this conclusion is a sustained collapse in automotive touch display adoption (e.g., a regulatory shift back to physical controls) or a materials breakthrough that makes alternative touch technologies cost-competitive with PCAP in harsh environments. Neither is currently on the horizon, so the selective-growth thesis stands.
1. How big is the capacitive touch screen market in 2025?
The global capacitive touch screen market was valued at approximately 28.9 Billion in 2025, representing roughly 41–43% of the broader touch display technology market, based on triangulated estimates across multiple published sources.
2. What is the capacitive touch screen market CAGR?
The market is forecast to grow at approximately 8.7% CAGR from 2025 to 2031, reaching an estimated 47 Billion by the end of the forecast period, driven by smartphone, automotive, and commercial display demand.
3. Which region dominates the capacitive touch screen market?
Asia-Pacific dominates with approximately 42% of global revenue, supported by dense display and controller manufacturing in China, South Korea, Japan, and Taiwan. North America follows at roughly 27%, driven by commercial and automotive deployments.
4. What is the difference between capacitive and resistive touch screens?
Capacitive screens detect touch through electrical capacitance changes and support multi-touch gestures without pressure, while resistive screens require physical pressure. Capacitive technology commands over 40% share due to superior clarity and gesture support.
5. Who are the leading capacitive touch screen vendors?
Key players include Samsung Display, LG Display, BOE Technology Group, and Elo Touch Solutions on the panel side, and NXP Semiconductors, Microchip Technology, and Synaptics on the touch controller IC side.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study employs a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the capacitive touch screen value chain: indium tin oxide and cover glass suppliers, touch panel module manufacturers, controller IC design and foundry firms, and global display distributors. Interviewees included VP-level Sourcing leads at OEMs, Heads of R&D at panel makers, Technical Directors at controller-IC vendors, and Commercial Operations Leads at commercial display integrators. Structured interview programs targeted six demand markets to isolate segment-level procurement behavior and qualification timelines.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
38%
Procurement & Sourcing Leads
32%
Commercial Operations Leads
18%
Quality & Regulatory Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Panel & Module Manufacturers
40%
Controller IC Designers & Foundries
30%
Commercial Display Integrators
18%
Materials & Component Suppliers
12%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and US ITC trade classifications for display modules and semiconductor components, Eurostat electronics trade data, corporate 10-K and annual investor filings from listed panel and controller vendors, patent databases covering capacitive sensing and palm-rejection IP, and technical standards from IEC and JEDEC covering EMC, environmental resilience, and display qualification. All secondary benchmarks are cross-referenced against primary interview data before inclusion.
Demand Modeling & Market Sizing Triangulation
Market sizing is triangulated through simultaneous Top-Down and Bottom-Up models. The Top-Down model allocates macro electronics and display spending across technology segments by observed technology share. The Bottom-Up model aggregates manufacturer unit volumes, pricing, and end-use consumption by application and display size, with controller IC volumes cross-checked against panel shipment data.


 Capacitive Touch Screen Market