 Relay Market
 Size, Share & Forecast to 2035 | Growth 5.98%
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 250

Srinwanti Kar
Senior Research Analyst

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Relay Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 9.700 B |
| 2026 | 10.28 B |
| 2027 | 10.89 B |
| 2028 | 11.54 B |
| 2029 | 12.23 B |
| 2030 | 12.96 B |
| 2031 | 13.74 B |

The Relay Market covers electrically operated switches that open or close circuits in response to control signals, spanning electromechanical, solid-state, reed and latching types across automotive, grid, industrial, telecom and appliance applications. It is defined by voltage class, mounting format and end-use duty cycle.
This analysis covers electromechanical, solid-state, hybrid, reed and latching relays across low, medium and high voltage ratings, all mounting configurations, six end-user industries and five global regions. This analysis does not cover standalone contactors sold as motor starters, fuses, circuit breakers or semiconductor discrete switching modules.
Published estimates cluster tightly around USD 9.6–9.7 Billion for 2025–2026, with horizons diverging between 2031 and 2035, producing materially different terminal values even at similar growth rates.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 9.70 B → 17.34 B | 2025 | 2035 | 5.98% | All relay types, global | One published estimate |
| USD 9.13 B → 9.64 B | 2025 | 2026 | 5.63% | All types, 2026–2031 window | A competing analysis |
| USD 7.1 B (electromechanical only) | 2023 | 2032 | 3.6% | Electromechanical sub-segment only | Separate sub-segment study |
Our analysis suggests the 2035 figure is the more defensible planning number because it captures the full high-voltage DC and digital-protection upgrade cycle, not just the near-term replacement window. The electromechanical-only figure is not directly comparable: it excludes solid-state, which is the fastest-growing class.
Segmentation follows four non-geographic axes—relay type, voltage rating, mounting configuration and end-user industry—each of which shifts the revenue pool toward higher-value, certified products.
| Parent | Children |
|---|---|
| Relay Type | Electromechanical, Solid-State, Hybrid, Reed, Latching |
| Voltage Rating | Low Voltage, Medium Voltage, High Voltage |
| Mounting Configuration | PCB-Mount, DIN-Rail, Panel-Mount, Plug-In (Socket) |
| End-User Industry | Automotive & E-Mobility, Energy & Power, Industrial Automation & Robotics, Telecom & Data Centers, Consumer Electronics & Appliances, Aerospace & Defense |
PCB-mount leads mounting formats at roughly 49–53% share, while DIN-rail posts the strongest growth outlook at 6.1% as control cabinets and HVAC panels multiply. High-voltage relays are the smallest volume class but carry the highest unit value.
Asia-Pacific leads the Relay Market with 45.8% share in 2025, anchored by China's component manufacturing base and record State Grid capital spending, followed by Europe at roughly 21% on grid reinforcement and industrial electrification.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.46% |
| Europe | 0.21% |
| North America | 0.18% |
| Middle East & Africa | 0.08% |
| South America | 0.07% |
Middle East & Africa is the fastest-growing region at a 7.1% CAGR as Gulf utilities build giga-scale solar and storage. Europe generated USD 2.08 Billion in 2025. Our analysis suggests regional share will shift only gradually because certification and qualification cycles protect incumbent positions in grid and automotive sockets.
Vehicle electrification and grid modernization together contribute roughly 2.5 percentage points of the forecast CAGR, but commodity price erosion and semiconductor substitution cap the upside in low-power switching.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Vehicle electrification & charging | +1.4% CAGR | High | 4–8 HV contactors per BEV; 17M+ EV sales in 2024 |
| Grid modernization & digital protection | +1.1% CAGR | High | IEC 61850 retrofits; EUR 584B EU grid investment |
| Renewable & storage buildout | +0.9% CAGR | High | 585 GW added in 2024; 1,500 V DC architectures |
| Industrial automation & robotics | +0.7% CAGR | Medium | 541,000 robot installations in 2023 |
| Semiconductor substitution | −0.7% CAGR | Medium | MOSFET/IGBT modules displace low-power relays |
| Commodity price erosion | −0.8% CAGR | High | Double-digit ASP declines in standard categories since 2024 |
The balance favors growth, but the composition matters more than the total: value migrates from commodity open-frame devices to sealed, arc-free and digitally integrated products. Our analysis suggests vendors without HV-DC certification will compete in a shrinking share of the revenue pool.
The vendor landscape is moderately concentrated, with Chinese, Japanese, European and US suppliers competing on different axes—cost, certification and systems integration—rather than on a single product specification.
| Company | HQ | Primary strength | Strategic position |
|---|---|---|---|
| Xiamen Hongfa | China | Electromechanical scale & cost | Volume leader in commodity and automotive |
| OMRON | Japan | PCB relays, automation interface | Broad portfolio, strong APAC distribution |
| TE Connectivity | Switzerland/US | HV-DC contactors (EVC 250-800) | EV and charging infrastructure incumbent |
| Panasonic Industry | Japan | Sealed gas-filled, PhotoMOS | Premium EV and telecom niches |
| ABB | Switzerland | Grid protection & substation relays | Utility specification strength |
| Siemens | Germany | Digital substations, IEC 61850 | Systems-level integration moat |
Differentiation increasingly rests on certification speed and ceramic-sealed production capacity rather than catalogue breadth. The commodity tier faces double-digit ASP erosion, while certified HV-DC and protection-relay suppliers retain pricing power.
Selection criteria differ sharply by application. Automotive buyers prioritize AEC-Q qualified parts, arc-free interruption at 800 V, vibration tolerance and PPAP documentation; a specification error surfaces as a warranty or safety event, not a procurement variance. Grid operators weight IEC 61850 interoperability, cyber-security certification and multi-decade service life, where switching costs are high because protection settings and SCADA integration are engineered around a specific device family.
Procurement risk concentrates in counterfeit and grey-market supply, particularly in commodity electromechanical categories where informal Asian suppliers have entered. Buyers should require traceability, lot-level test data and authorized-channel sourcing. Regulatory compliance—UL, IEC, and automotive functional-safety standards—is a gating item, not a differentiator. Our analysis suggests qualification cycles of 12–24 months create lock-in that outweighs unit-price differences in mission-critical sockets.
The balance of evidence favors a selective-growth thesis: the Relay Market expands at roughly 6% annually, but value concentrates in high-voltage DC switching and digital protection rather than in the flat-to-declining commodity core. Vendors that treat solid-state and electromechanical as separate businesses, with separate certification roadmaps, will outperform those defending a single catalogue.
The strongest counter-argument is that electromechanical relays retain 57–61% share precisely because they handle arcs and harsh environments at low cost, and that solid-state thermal limits above 60 A will slow substitution in heavy-duty applications. That is credible—but it argues for a longer transition, not a reversal. Our analysis suggests the hybrid relay category is the underappreciated beneficiary of this constraint.
Actionable strategy:
The conclusion would change if solid-state thermal management improved materially above 60 A, or if grid investment timelines slipped by more than two years. While this overview establishes the strategic direction, precise sub-segment forecasting and vendor-level share analysis require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.98% from 2020-2034 |
| Segmentation |
|
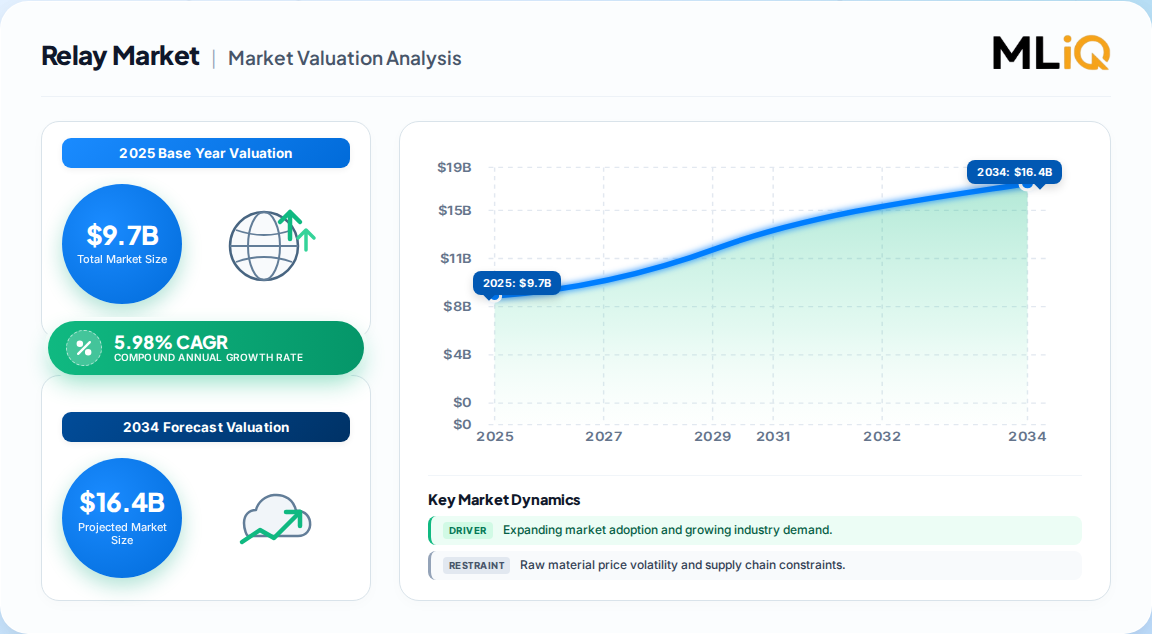
The global Relay Market was valued at USD 9.70 Billion in 2025 and is projected to reach USD 10.28 Billion in 2026, according to one published estimate covering all relay types worldwide.
The market is forecast to grow at a 5.98% CAGR from 2026 to 2035, reaching USD 17.34 Billion. Competing analyses using shorter horizons report rates between 5.63% and higher sub-segment figures.
Electromechanical relays hold approximately 56.8% of 2025 revenue, sustained by arc-handling capacity and low cost. Solid-state relays are the fastest-growing class at a 7.3% CAGR, driven by 800 V platforms.
Asia-Pacific leads with 45.8% share, supported by China's manufacturing base and State Grid spending. Middle East & Africa is the fastest-growing region at a 7.1% CAGR on giga-scale solar and storage.
Vehicle electrification, grid modernization, renewable and storage buildout, and industrial automation are the primary drivers, together contributing roughly 4.1 percentage points of upside to the forecast CAGR.
Leading vendors include Xiamen Hongfa, OMRON, TE Connectivity, Panasonic Industry, ABB and Siemens, competing across commodity scale, HV-DC certification and systems integration.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the relay value chain, including contact and reed-switch suppliers, specialized relay producers, ceramic-sealed component manufacturers, contract assembly partners and global distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of R&D, Technical Directors and Commercial Operations Leads at automotive, grid and industrial OEMs.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 40% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Relay & Component Producers | 45% |
| Contract Assembly & Sealing Partners | 25% |
| Global Distributors & Traders | 30% |
Secondary validation draws on UN Comtrade and US ITC trade flows, corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and standards bodies including IEC, UL and AEC automotive qualification frameworks. Trade statistics are reconciled against reported supplier segment revenues to discard outliers.
Sizing runs simultaneously top-down, allocating macroeconomic and industry segment output to relay content per application, and bottom-up, modeling manufacturer capacity, ASPs and end-use consumption. Divergence between the two approaches is resolved through scenario-weighted adoption curves for EVs, storage and grid investment.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |