Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Level Sensor Market Size, Share & Growth Forecast to 2035
Level Sensor Market Size, Share & Growth Forecast to 2035
Level Sensor Market
Level Sensor Market Size, Share & Growth Forecast to 2035
Level Sensor Market by Monitoring Type (Point Level, Continuous Level), by Technology (Contact, Non-Contact), by Sensor Technology (Capacitive, Conductive, Optical/Photoelectric, Microwave/Radar, Ultrasonic, Laser, Float, Magnetostrictive, Hydrostatic), by Component (Sensing Element & Probe, Transmitter/Converter, Display & Controller), by End-Use Industry (Oil & Gas, Chemicals, Water & Wastewater, Food & Beverage, Energy & Power, Pharma, Other), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands, Belgium), by Asia Pacific (China, Japan, India, South Korea, Taiwan, Singapore, Indonesia, Australia), by Middle East & Africa (Saudi Arabia, UAE, Qatar, Kuwait, South Africa), by Latin America (Brazil, Argentina, Chile, Colombia) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 289
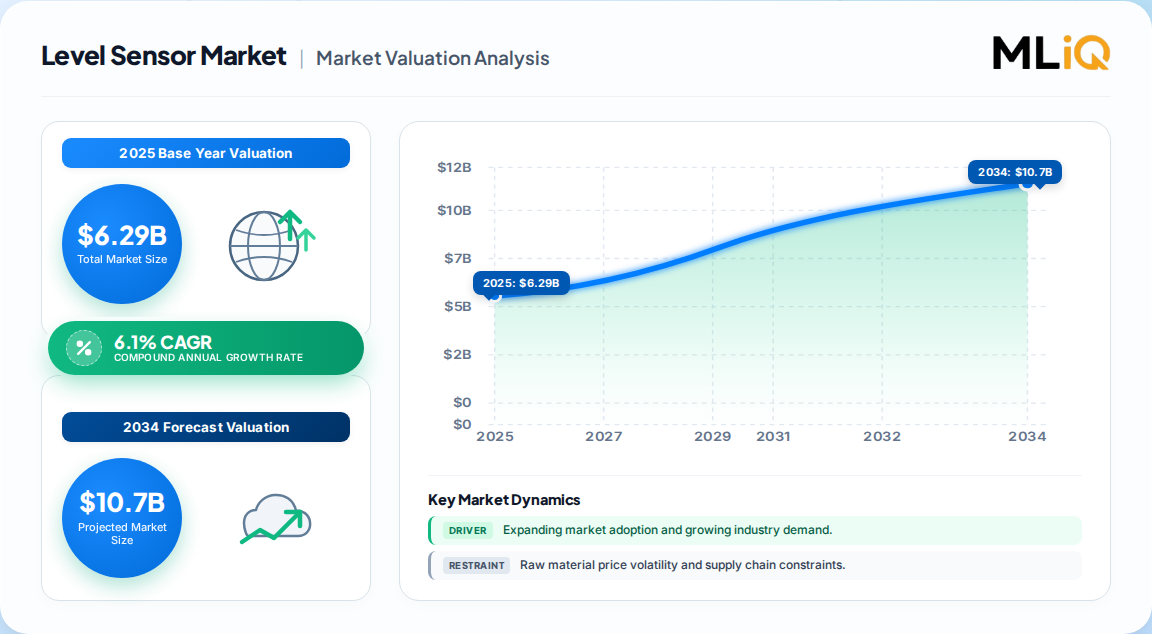
The global Level Sensor Market was valued at USD 6.29 billion in 2025 and is projected to reach USD 11.37 billion by 2035, advancing at a 6.1% CAGR.
Continuous level monitoring dominates demand, holding roughly 64–68% of revenue, while non-contact technologies capture about 57–62% of deployments.
Microwave/radar is the fastest-growing sensor technology, expanding near 9.5% annually as 80 GHz FMCW units displace legacy mechanical floats.
Asia-Pacific leads with approximately 38.5% of global revenue; the Middle East is the fastest-growing region at roughly 10.4% CAGR.
Emerson, Endress+Hauser, Siemens, VEGA, ABB and Ametek anchor a low-concentration competitive field with strong SIL-certification moats.
Why this matters for decision-makers: Procurement teams must lock in 80 GHz radar and SIL-3-certified supply now, because GaAs foundry constraints will tighten lead times and shift pricing power toward certified incumbents through 2029.
Level Sensor Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
6.290 B
2025
6.670 B
2026
7.080 B
2027
7.510 B
2028
7.970 B
2029
8.450 B
2030
8.970 B
2031
Level Sensor Market Size (In Billion)
Year
Market Size
2025
6.290 B
2026
6.670 B
2027
7.080 B
2028
7.510 B
2029
7.970 B
2030
8.450 B
2031
8.970 B
What is the Level Sensor Market?
The Level Sensor Market covers instruments that detect and measure the level of liquids, slurries, powders and granular solids in tanks, silos, reservoirs and process vessels. It spans point-level switches and continuous transmitters using ultrasonic, radar, capacitive, conductive, optical, float and hydrostatic technologies across oil and gas, water, chemicals and food applications.
Scope: what this report covers and excludes
This analysis covers point and continuous level instruments by technology, sensor type, component and end-use industry across five global regions, with 2025 as the base year and forecasts to 2035. This analysis does not cover flow, pressure or temperature instrumentation, nor does it address analytical and gas-detection sensors or general-purpose proximity switches.
How big is the market for Level Sensor Market?
One published estimate puts the market at USD 6.29 billion in 2025 rising to USD 11.37 billion by 2035 at 6.1% CAGR, a figure our analysis treats as the most defensible anchor because it aligns with reported installed-base growth and radar replacement cycles.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
USD 6.29 Bn
2025
2035
6.1%
Contact + non-contact level instruments, all industries
One published estimate
USD 6.48 Bn
2026
2031
6.04%
Level sensors by monitoring, technology, component
A competing analysis
USD 5.5 Bn
2025
2035
7.5%
Broad sensor-type taxonomy incl. laser and hydrostatic
A competing analysis
Our analysis suggests the divergence stems from taxonomy breadth, not demand disagreement: the 7.5% figure includes laser, hydrostatic and magnetostrictive devices, while the 6.1% and 6.04% estimates narrow scope to core level instrumentation. The mid-single-digit consensus is therefore more reliable for procurement budgeting, while the higher figure better reflects total addressable instrumentation spend.
How is the market segmented?
The market segments along four non-geographic axes, with continuous monitoring, non-contact technology and radar dominating value while sensing elements and probes represent over half of component-level revenue.
Sensing Element & Probe, Transmitter/Converter, Display & Controller
By End-Use Industry
Oil & Gas, Chemicals, Water & Wastewater, Food & Beverage, Energy & Power, Pharma, Other
Radar's rise is the structural story: non-contact operation eliminates process-seal failures, embeds self-diagnostics and integrates WirelessHART and IO-Link, which cuts installation labor and supports predictive maintenance. That is why radar commands roughly 35% of the installed base yet grows fastest.
Which region leads in Level Sensor Market?
Asia-Pacific leads the Level Sensor Market with approximately 38.5% of 2025 revenue, near USD 2.12 billion, driven by desalination megaprojects, wastewater build-out and concentrated chemical and electronics manufacturing. The Middle East is the fastest-growing region, advancing near 10.4% CAGR on tank-farm digitization.
Level Sensor Market Regional Market Share
Loading chart...
Level Sensor Market Regional Market Share
Region
Market Share (%)
North America
0.26%
Europe
0.21%
Asia-Pacific
0.39%
Middle East & Africa
0.1%
Latin America
0.05%
Region
Share of 2025 Revenue
Asia-Pacific
38.5%
North America
26.0%
Europe
21.0%
Middle East & Africa
10.0%
Latin America
4.5%
Asia-Pacific: China, India, Japan, South Korea, Taiwan, Singapore, Indonesia, Australia
North America: United States, Canada, Mexico
Europe: Germany, UK, France, Italy, Netherlands, Belgium, Spain, Nordics
Middle East & Africa: Saudi Arabia, UAE, Qatar, Kuwait, South Africa
Latin America: Brazil, Argentina, Chile, Colombia
Our analysis suggests the Middle East's growth premium reflects a compressed retrofit cycle: GCC operators are automating over 10,000 tanks simultaneously, concentrating demand that other regions spread over a decade. This implies lumpier order books but higher per-project margin for vendors holding IEC 61511 and SIL-3 portfolios.
What is driving growth — and what is holding it back?
Growth is driven by the 80 GHz radar migration in custody-transfer systems, GCC tank-farm digitization, Asia-Pacific desalination build-out and mandatory SIL-3 safety audits in European chemical parks, while GaAs foundry scarcity and electromagnetic interference temper the pace.
Factor
Direction
Evidence strength
Mechanism
80 GHz FMCW radar adoption in custody transfer
Driver (+1.8%)
High
±0.5 mm accuracy mandates; ~12,000 tank retrofits planned
GCC tank-farm automation
Driver (+1.5%)
High
10,000+ tanks automated; SIL-2/3 specifications
Asia-Pacific desalination and wastewater
Driver (+1.3%)
Medium-High
Corrosion-resistant transmitters; 1,200 sensors per plant
European SIL-3 safety audits
Driver (+1.1%)
High
Seveso III compliance; independent secondary devices
8-inch GaAs MMIC capacity shortage
Restraint (−0.9%)
Medium
Constrains 80 GHz front-end supply
EMI-induced accuracy drift in steel mills
Restraint
Medium
False echoes and signal degradation
The balance clearly favors expansion: quantified drivers sum to roughly 6.3 percentage points of incremental growth against about 0.9 points of constraint. Our analysis suggests the binding limit is not demand but certified component supply, which effectively caps near-term radar volume and sustains premium pricing.
Who are the leading vendors?
The market is low-concentration and led by Emerson, Endress+Hauser, Siemens, VEGA and ABB, each differentiated by radar frequency capability, safety certification depth and digital protocol integration rather than by price.
Vendor
Notable Position
Differentiation
Emerson
Rosemount 3408 Wireless, 80 GHz FMCW
WirelessHART native, custody-transfer installed base
Endress+Hauser
Micropilot FMR43, 80/180 GHz
±1 mm accuracy, wide temperature/pressure range
ABB
LRT100 radar family
30 m range, 4° beam angle, Bluetooth commissioning
Siemens
Process instrumentation portfolio
DCS integration and plant-wide automation lock-in
VEGA Grieshaber
Radar and guided-wave specialist
Hazardous-area certification depth
AMETEK / Magnetrol
Level and flow portfolio
Niche industrial and OEM channels
Moats accrue to vendors holding 80 GHz IP, gallium-arsenide wafer supply agreements and SIL-3 certificates, which enable premium pricing in hazardous and custody-transfer duty. Our analysis suggests certification portfolios, not sensor hardware, are the durable barrier.
What do buyers and operators need to know?
Buyers should prioritize safety certification, beam angle and accuracy over headline price. SIL-3 certification for hazardous service and ±0.5 mm accuracy for custody transfer are now contractual requirements in many tenders, so non-certified alternatives carry hidden compliance risk.
Switching costs are substantial: DCS integration, HART or Profibus configuration and technician training create multi-year lock-in once a platform is installed. Procurement teams should therefore negotiate protocol compatibility and spare-parts availability at the initial award rather than at replacement.
Regulatory exposure is rising. European Seveso III amendments, API measurement standards and IEC 61511 risk-reduction rules each impose device-level certification obligations. GaAs supply constraints add a second risk: operators should qualify dual-source suppliers or accept extended lead times for 80 GHz devices.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-single-digit growth market in which value migrates decisively toward non-contact radar and certified safety instrumentation. Vendors without 80 GHz capability or SIL-3 portfolios will increasingly compete on price in commoditized float, conductive and capacitive segments, where margin compression is structural rather than cyclical.
The strongest counter-argument is that ultrasonic retains a 23.5% share and remains cheaper for hygienic and short-range duty, so radar displacement may stall in food and pharmaceutical applications. This is credible but narrow: ultrasonic's advantage is price and cleanliness, not accuracy or diagnostics, so it caps rather than reverses the radar trajectory.
Actionable Strategy:
Operators should schedule 80 GHz retrofits before 2029 to avoid supply-constrained pricing and qualify dual-source GaAs supply.
Vendors should prioritize SIL-3 certification and WirelessHART integration to defend premium pricing in hazardous duty.
Investors should weight exposure toward radar component supply and certified transmitter vendors over mechanical-float specialists.
Our conclusion would change if GaAs capacity expanded faster than expected, collapsing radar pricing, or if a lower-cost non-contact technology achieved ±0.5 mm accuracy at scale. Absent either, certified radar remains the defensible growth vector through 2035.
Level Sensor Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Level Sensor Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.1% from 2020-2034
Segmentation
By Monitoring Type
Point Level
Continuous Level
By Technology
Contact
Non-Contact
By Sensor Technology
Capacitive
Conductive
Optical/Photoelectric
Microwave/Radar
Ultrasonic
Laser
Float
Magnetostrictive
Hydrostatic
By Component
Sensing Element & Probe
Transmitter/Converter
Display & Controller
By End-Use Industry
Oil & Gas
Chemicals
Water & Wastewater
Food & Beverage
Energy & Power
Pharma
Other
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Belgium
Asia Pacific
China
Japan
India
South Korea
Taiwan
Singapore
Indonesia
Australia
Middle East & Africa
Saudi Arabia
UAE
Qatar
Kuwait
South Africa
Latin America
Brazil
Table of Contents
1. Level Sensor Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Level Sensor Market Executive Summary
2.1. Market Snapshot
3. Level Sensor Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Level Sensor Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Level Sensor Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Monitoring Type
5.1.1. Point Level
5.1.2. Continuous Level
5.2. Analysis, Insights and Forecast - by Technology
5.2.1. Contact
5.2.2. Non-Contact
5.3. Analysis, Insights and Forecast - by Sensor Technology
5.3.1. Capacitive
5.3.2. Conductive
5.3.3. Optical/Photoelectric
5.3.4. Microwave/Radar
5.3.5. Ultrasonic
5.3.6. Laser
5.3.7. Float
5.3.8. Magnetostrictive
5.3.9. Hydrostatic
5.4. Analysis, Insights and Forecast - by Component
5.4.1. Sensing Element & Probe
5.4.2. Transmitter/Converter
5.4.3. Display & Controller
5.5. Analysis, Insights and Forecast - by End-Use Industry
5.5.1. Oil & Gas
5.5.2. Chemicals
5.5.3. Water & Wastewater
5.5.4. Food & Beverage
5.5.5. Energy & Power
5.5.6. Pharma
5.5.7. Other
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Middle East & Africa
5.6.5. Latin America
6. Level Sensor Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Monitoring Type
6.1.1. Point Level
6.1.2. Continuous Level
6.2. Analysis, Insights and Forecast - by Technology
6.2.1. Contact
6.2.2. Non-Contact
6.3. Analysis, Insights and Forecast - by Sensor Technology
6.3.1. Capacitive
6.3.2. Conductive
6.3.3. Optical/Photoelectric
6.3.4. Microwave/Radar
6.3.5. Ultrasonic
6.3.6. Laser
6.3.7. Float
6.3.8. Magnetostrictive
6.3.9. Hydrostatic
6.4. Analysis, Insights and Forecast - by Component
6.4.1. Sensing Element & Probe
6.4.2. Transmitter/Converter
6.4.3. Display & Controller
6.5. Analysis, Insights and Forecast - by End-Use Industry
6.5.1. Oil & Gas
6.5.2. Chemicals
6.5.3. Water & Wastewater
6.5.4. Food & Beverage
6.5.5. Energy & Power
6.5.6. Pharma
6.5.7. Other
7. Level Sensor Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Monitoring Type
7.1.1. Point Level
7.1.2. Continuous Level
7.2. Analysis, Insights and Forecast - by Technology
7.2.1. Contact
7.2.2. Non-Contact
7.3. Analysis, Insights and Forecast - by Sensor Technology
7.3.1. Capacitive
7.3.2. Conductive
7.3.3. Optical/Photoelectric
7.3.4. Microwave/Radar
7.3.5. Ultrasonic
7.3.6. Laser
7.3.7. Float
7.3.8. Magnetostrictive
7.3.9. Hydrostatic
7.4. Analysis, Insights and Forecast - by Component
7.4.1. Sensing Element & Probe
7.4.2. Transmitter/Converter
7.4.3. Display & Controller
7.5. Analysis, Insights and Forecast - by End-Use Industry
7.5.1. Oil & Gas
7.5.2. Chemicals
7.5.3. Water & Wastewater
7.5.4. Food & Beverage
7.5.5. Energy & Power
7.5.6. Pharma
7.5.7. Other
8. Level Sensor Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Monitoring Type
8.1.1. Point Level
8.1.2. Continuous Level
8.2. Analysis, Insights and Forecast - by Technology
8.2.1. Contact
8.2.2. Non-Contact
8.3. Analysis, Insights and Forecast - by Sensor Technology
8.3.1. Capacitive
8.3.2. Conductive
8.3.3. Optical/Photoelectric
8.3.4. Microwave/Radar
8.3.5. Ultrasonic
8.3.6. Laser
8.3.7. Float
8.3.8. Magnetostrictive
8.3.9. Hydrostatic
8.4. Analysis, Insights and Forecast - by Component
8.4.1. Sensing Element & Probe
8.4.2. Transmitter/Converter
8.4.3. Display & Controller
8.5. Analysis, Insights and Forecast - by End-Use Industry
8.5.1. Oil & Gas
8.5.2. Chemicals
8.5.3. Water & Wastewater
8.5.4. Food & Beverage
8.5.5. Energy & Power
8.5.6. Pharma
8.5.7. Other
9. Level Sensor Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Monitoring Type
9.1.1. Point Level
9.1.2. Continuous Level
9.2. Analysis, Insights and Forecast - by Technology
9.2.1. Contact
9.2.2. Non-Contact
9.3. Analysis, Insights and Forecast - by Sensor Technology
9.3.1. Capacitive
9.3.2. Conductive
9.3.3. Optical/Photoelectric
9.3.4. Microwave/Radar
9.3.5. Ultrasonic
9.3.6. Laser
9.3.7. Float
9.3.8. Magnetostrictive
9.3.9. Hydrostatic
9.4. Analysis, Insights and Forecast - by Component
9.4.1. Sensing Element & Probe
9.4.2. Transmitter/Converter
9.4.3. Display & Controller
9.5. Analysis, Insights and Forecast - by End-Use Industry
9.5.1. Oil & Gas
9.5.2. Chemicals
9.5.3. Water & Wastewater
9.5.4. Food & Beverage
9.5.5. Energy & Power
9.5.6. Pharma
9.5.7. Other
10. Level Sensor Market Latin America Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Monitoring Type
10.1.1. Point Level
10.1.2. Continuous Level
10.2. Analysis, Insights and Forecast - by Technology
10.2.1. Contact
10.2.2. Non-Contact
10.3. Analysis, Insights and Forecast - by Sensor Technology
10.3.1. Capacitive
10.3.2. Conductive
10.3.3. Optical/Photoelectric
10.3.4. Microwave/Radar
10.3.5. Ultrasonic
10.3.6. Laser
10.3.7. Float
10.3.8. Magnetostrictive
10.3.9. Hydrostatic
10.4. Analysis, Insights and Forecast - by Component
10.4.1. Sensing Element & Probe
10.4.2. Transmitter/Converter
10.4.3. Display & Controller
10.5. Analysis, Insights and Forecast - by End-Use Industry
10.5.1. Oil & Gas
10.5.2. Chemicals
10.5.3. Water & Wastewater
10.5.4. Food & Beverage
10.5.5. Energy & Power
10.5.6. Pharma
10.5.7. Other
11. Level Sensor Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Level Sensor Market Research Methodology
List of Figures
Figure 1: Level Sensor Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Level Sensor Market Revenue (Billion), by Monitoring Type 2026 & 2034
Figure 3: North America Level Sensor Market Revenue Share (%), by Monitoring Type 2026 & 2034
Figure 4: North America Level Sensor Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America Level Sensor Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Level Sensor Market Revenue (Billion), by Sensor Technology 2026 & 2034
Figure 7: North America Level Sensor Market Revenue Share (%), by Sensor Technology 2026 & 2034
Figure 8: North America Level Sensor Market Revenue (Billion), by Component 2026 & 2034
Figure 9: North America Level Sensor Market Revenue Share (%), by Component 2026 & 2034
Figure 10: North America Level Sensor Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 11: North America Level Sensor Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 12: North America Level Sensor Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Level Sensor Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Level Sensor Market Revenue (Billion), by Monitoring Type 2026 & 2034
Figure 15: Europe Level Sensor Market Revenue Share (%), by Monitoring Type 2026 & 2034
Figure 16: Europe Level Sensor Market Revenue (Billion), by Technology 2026 & 2034
Europe Level Sensor Market Revenue Share (%), by Technology 2026 & 2034
List of Tables
Table 1: Level Sensor Market Revenue Billion Forecast, by Monitoring Type 2020 & 2034
Table 16: Europe Level Sensor Market Revenue Billion Forecast, by Monitoring Type 2020 & 2034
Frequently Asked Questions
1. How big is the Level Sensor Market in 2025?
The Level Sensor Market was valued at approximately USD 6.29 billion in 2025. Published estimates range from USD 5.5 billion to USD 6.48 billion depending on whether laser, hydrostatic and magnetostrictive devices are included in scope.
2. What is the growth rate of the Level Sensor Market?
Most published analyses converge on a mid-single-digit CAGR of roughly 6.0% to 6.1% through the early 2030s. Broader taxonomies that include laser and hydrostatic sensors project up to 7.5%, reflecting wider scope rather than stronger underlying demand.
3. Which region leads the Level Sensor Market?
Asia-Pacific leads with approximately 38.5% of global revenue, near USD 2.12 billion in 2025. Desalination, wastewater and chemical manufacturing in China, India and Taiwan drive the regional concentration, while the Middle East grows fastest.
4. Which technology is growing fastest in level sensing?
Microwave and radar sensors are the fastest-growing technology, expanding near 9.5% annually. The migration to 80 GHz FMCW units in custody-transfer and hazardous-area applications drives replacement demand and premium pricing.
5. Who are the leading vendors in the Level Sensor Market?
Emerson, Endress+Hauser, Siemens, VEGA Grieshaber and ABB lead the market. Differentiation rests on 80 GHz radar capability, safety integrity level certification and digital protocol integration such as WirelessHART, IO-Link and Profibus.
6. Why are non-contact level sensors replacing contact devices?
Non-contact radar and ultrasonic sensors operate without process seals, eliminating a common failure point in corrosive or hygienic service. They also embed self-diagnostics and wireless connectivity, reducing installation labor and enabling predictive maintenance.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a deliberate 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews across the level instrumentation value chain, including semiconductor and MMIC component suppliers, specialized level transmitter manufacturers, system integrators and automation OEMs, global industrial distributors, and end-user engineering contractors. Interviewees were selected by decision authority and included VP-level Sourcing executives, Heads of Instrumentation R&D, Technical Directors responsible for safety system design, and Commercial Operations Leads managing hazardous-area portfolios. Structured interview guides captured pricing architecture, qualification timelines and certification bottlenecks.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
35%
R&D & Technical Directors
30%
Safety & Compliance Managers
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Component & MMIC Suppliers
30%
Level Transmitter Manufacturers
35%
System Integrators & OEMs
20%
Industrial Distributors
15%
Secondary Benchmarking & Public Trade Validation
Fieldwork was triangulated against official multilateral trade databases including UN Comtrade, WTO statistics, US ITC and Eurostat, alongside corporate annual filings, 10-K disclosures and investor presentations from publicly listed instrumentation vendors. Patent databases were screened for 80 GHz radar and FMCW front-end filings, while recognized technical standards bodies and industry associations informed certification and safety-integrity benchmarks. No third-party market research publisher data was used as a validation source.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous Top-Down and Bottom-Up models. The top-down model allocates macroeconomic industrial output and process-industry capital expenditure across level-sensing applications. The bottom-up model builds from manufacturer capacity, average selling prices and end-use consumption at the plant level, reconciling both against reported revenue and installed-base replacement cycles.


 Level Sensor Market