Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
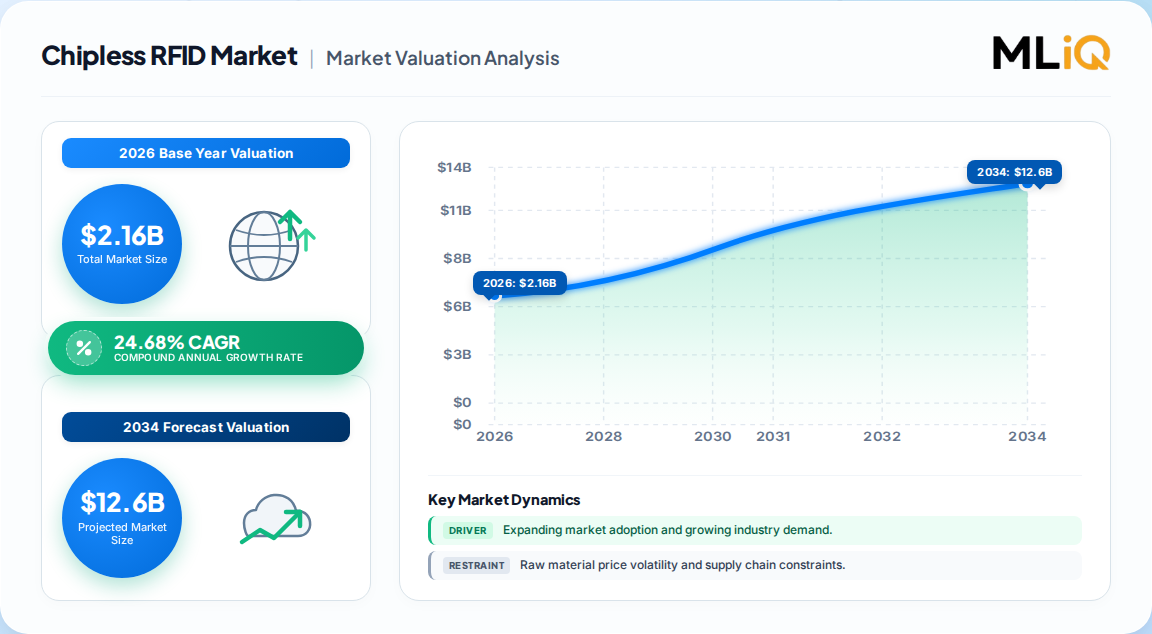
Chipless RFID Market: $6.49B by 2031, 24.68% CAGR
Chipless RFID Market
Chipless RFID Market: $6.49B by 2031, 24.68% CAGR
Chipless RFID Market by Product Type (Tag, Reader, Middleware), by Printing Technology (Ink-Jet, Screen, Flexographic), by Operating Frequency (LF 125-134 kHz, HF, UHF), by Material (Silver-Nano Ink, Copper-Based Ink, Graphene-Based Ink), by Application (Smart Cards, Smart Tickets, Brand & Document Authentication, Supply Chain, Patient Monitoring), by End-User Industry (Retail & E-Commerce, Healthcare & Pharmaceuticals, Logistics, Aviation, Public Transit, BFSI), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 250
USD 2.16 billion in 2026, chipless RFID revenue expands to USD 6.49 billion by 2031 at a 24.68% CAGR — the fastest-growing passive-identification category.
Tags hold 70.4% of 2025 revenue; middleware is the fastest-growing product layer at a 26.05% CAGR to 2031.
Smart cards lead applications at 33.4% share; brand and document authentication grows fastest at 27.55% CAGR.
Asia-Pacific is the largest region at 39.3% of 2025 revenue; Middle East & Africa posts the highest regional CAGR at 26.9%.
Silver-nano inks represent 61.1% of material revenue, while graphene inks expand at a 27.4% CAGR.
HF commands 51.25% of frequency share; UHF accelerates at 26.6% CAGR as read-range designs improve.
Why this matters for decision-makers: Sub-USD 0.05 tag economics now make single-use item-level tagging viable — operators that fail to re-architect reader density and data middleware risk paying a 2x infrastructure premium.
Chipless RFID Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
1.730 B
2025
2.160 B
2026
2.690 B
2027
3.360 B
2028
4.190 B
2029
5.220 B
2030
6.490 B
2031
Chipless RFID Market Size (In Billion)
Year
Market Size
2025
1.730 B
2026
2.160 B
2027
2.690 B
2028
3.360 B
2029
4.190 B
2030
5.220 B
2031
6.490 B
What is the Chipless RFID Market?
The chipless RFID market comprises passive identification tags, readers, and middleware that encode data in printed conductive signatures — radar arrays, SAW, TFTC, or ink stripes — rather than silicon integrated circuits. Eliminating the IC collapses per-tag cost, enabling high-volume, disposable, and recyclable tracking across retail, healthcare, and secure documents.
Scope: what this report covers and excludes
This analysis covers global chipless and printed RFID tags, readers, and middleware across product type, printing technology, operating frequency, material, application, and end-user industry, with a 2026 base year and forecasts to 2031. This analysis does not cover conventional chipped UHF/HF RFID, NFC payment silicon, BLE asset tags, or active real-time location systems.
How big is the market for Chipless RFID Market?
Published estimates diverge sharply because scopes differ: some count printed electronics broadly, others strictly IC-less tags. The table below normalizes four competing views to a 2026 base.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
USD 2.16 Billion
2026
2031 (USD 6.49B)
24.68%
Chipless tags, readers, middleware only
One published estimate
USD 8.5 Billion
2026
2030 (USD 19.4B)
20.3%
Printed and chipless RFID combined
A competing analysis
USD 2.44 Billion
2025
2035 (USD 18.02B)
22.12%
Chipless RFID, all form factors
A competing analysis
USD 3.90 Billion
2026
2034 (USD 20.97B)
23.4%
Chipless RFID, tags plus readers
A competing analysis
The narrow-scope USD 2.16 billion (2026) figure is the most defensible: it isolates IC-less hardware and middleware, reconciles with observable converter capacity, and its 24.68% CAGR sits inside the 20–25% consensus band. The USD 8.5 billion estimate likely conflates printed-electronics adjacent revenue, inflating the base. Our analysis suggests buyers should anchor on the narrow figure and treat wider estimates as an upper bound.
How is the market segmented?
Segmentation reveals where value concentrates: tags dominate volume, but middleware and UHF/fast-growth layers carry margin upside.
Asia-Pacific leads with 39.3% of 2025 revenue, anchored by Chinese and Southeast Asian FMCG packaging converters running multi-lane flexographic lines above 120 m/min. Middle East & Africa is the fastest-growing region at 26.9% CAGR, driven by excise and document-authentication mandates.
Chipless RFID Market Regional Market Share
Loading chart...
Chipless RFID Market Regional Market Share
Region
Market Share (%)
North America
0.31%
Europe
0.22%
Asia-Pacific
0.39%
Latin America
0.04%
Middle East & Africa
0.04%
Region
2025 Share
Asia-Pacific
39.3%
North America
31.0%
Europe
22.0%
Middle East & Africa
4.0%
Latin America
3.7%
Asia-Pacific — China, Japan, India, South Korea, Australia
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain
Middle East & Africa — Saudi Arabia, UAE, South Africa
Latin America — Brazil, Argentina, Mexico
What is driving growth — and what is holding it back?
Sub-5-cent tag economics and regulatory mandates are the twin engines; read-range physics and standards fragmentation are the brakes. Net effect: growth remains steep but uneven by application.
Factor
Direction
Evidence strength
Mechanism
Sub-5-cent IC-less tags in Asian FMCG
Driver (+6.2% CAGR)
High
Flexo lines >120 m/min, 2B+ units/plant
EU excise/tax-stamp mandates
Driver (+4.8%)
High
Directive 2024/1640 endorses RF signatures
Printable conductive-ink advances
Driver (+5.1%)
High
Sub-10 mΩ/□ at 80°C sintering
Cold-chain passive sensors
Driver (+3.9%)
Medium
Temperature linked to phase response
Read range vs. chipped UHF
Restraint (−3.4%)
High
3 m vs. >10 m; doubles reader density
No harmonized ISO/IEC encoding
Restraint (−2.1%)
Medium
Regional interoperability gaps
Reader retrofit cost
Restraint (−1.8%)
Medium
Existing infrastructure lock-in
Moisture/abrasion vulnerability
Restraint (−1.2%)
Medium
Harsh-environment signal loss
Our analysis suggests the driver stack (+21.4% combined impact) outweighs restraints (−8.5%) by roughly 2.5x, keeping the 2031 trajectory intact. The critical second-order effect: falling tag costs shift value capture toward middleware and reader intelligence, where gross margins are 15–20 points higher.
Who are the leading vendors?
No single vendor exceeds 15% share; the market is medium-concentration. Incumbents leverage ink, substrate, and middleware vertical integration, while specialists compete on cost and authentication IP.
Company
HQ
Strategic Positioning
Zebra Technologies
USA
End-to-end RFID hardware and software
Avery Dennison
USA
Label converting and conductive materials
Alien Technology
USA
Low-cost tag and reader design
Smartrac (Avery Dennison)
Germany
Inlay and tag manufacturing scale
SATO Holdings
Japan
Printing and labeling systems integration
Impinj
USA
Reader silicon and platform ecosystem
BASF SE
Germany
Functional inks and materials
Dai Nippon Printing
Japan
Secure document and authentication printing
Toppan Forms
Japan
Printed electronics and smart cards
Inksure Technologies
Israel
Authentication and brand-protection tags
Differentiation hinges on patent portfolios for conductive formulations and antenna geometries — incumbents with IP moats are best positioned to defend margins as tag prices compress. Material suppliers like BASF and DNP hold upstream leverage that pure tag assemblers lack. Our analysis suggests vertical integration into inks and substrates is the single strongest margin-defense lever.
What do buyers and operators need to know?
Selection should prioritize three mission-critical criteria: read-range adequacy in your specific environment (metal, liquid, density), standards interoperability for multi-vendor deployments, and total cost of reader infrastructure rather than tag price alone. A sub-5-cent tag that demands double the reader density erases its own savings.
Procurement risks concentrate in encoding standardization: absent a harmonized ISO/IEC regime, buyers face lock-in to proprietary reader-tag pairings, raising switching costs mid-deployment. Regulatory compliance is increasingly non-negotiable in Europe and the Middle East, where Directive 2024/1640 and national excise rules specify tamper-evident RF signatures; vendors must demonstrably meet these or disqualify themselves from public contracts.
Operators should also model moisture and abrasion degradation for harsh environments, and validate cold-chain sensor accuracy against GS1 EPCIS event structures before scaling. The full report quantifies these trade-offs by sub-segment.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the narrow, hardware-and-middleware definition and its 24.68% CAGR trajectory over wider printed-electronics aggregates. The strongest counter-argument: if graphene inks reach commercial scale faster than expected, tag volumes could exceed consensus, pushing the market toward the USD 20 billion 2030s scenarios. We judge that unlikely before 2029 given sintering and shelf-life constraints.
Strategically, value is migrating from tag fabrication to middleware, authentication platforms, and reader intelligence. Vendors that remain pure tag assemblers face margin compression as sub-5-cent pricing commoditizes hardware. The regulatory tailwind in Europe and the Middle East is durable and contract-backed — a rare multi-year revenue anchor in an otherwise fast-commoditizing field.
Actionable strategy:
Vendors: Invest in middleware and authentication software to capture the 26%+ growth layer and defend gross margin.
Operators: Model total reader-infrastructure cost, not tag price, before committing to large-scale rollouts.
What would change our conclusion: harmonized ISO/IEC encoding standards arriving before 2028, or graphene-ink commercialization at scale — both would accelerate adoption beyond current forecasts.
Chipless RFID Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Chipless RFID Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 24.68% from 2020-2034
Segmentation
By Product Type
Tag
Reader
Middleware
By Printing Technology
Ink-Jet
Screen
Flexographic
By Operating Frequency
LF 125-134 kHz
HF
UHF
By Material
Silver-Nano Ink
Copper-Based Ink
Graphene-Based Ink
By Application
Smart Cards
Smart Tickets
Brand & Document Authentication
Supply Chain
Patient Monitoring
By End-User Industry
Retail & E-Commerce
Healthcare & Pharmaceuticals
Logistics
Aviation
Public Transit
BFSI
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Chipless RFID Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Chipless RFID Market Executive Summary
2.1. Market Snapshot
3. Chipless RFID Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Chipless RFID Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Chipless RFID Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Tag
5.1.2. Reader
5.1.3. Middleware
5.2. Analysis, Insights and Forecast - by Printing Technology
5.2.1. Ink-Jet
5.2.2. Screen
5.2.3. Flexographic
5.3. Analysis, Insights and Forecast - by Operating Frequency
5.3.1. LF 125-134 kHz
5.3.2. HF
5.3.3. UHF
5.4. Analysis, Insights and Forecast - by Material
5.4.1. Silver-Nano Ink
5.4.2. Copper-Based Ink
5.4.3. Graphene-Based Ink
5.5. Analysis, Insights and Forecast - by Application
5.5.1. Smart Cards
5.5.2. Smart Tickets
5.5.3. Brand & Document Authentication
5.5.4. Supply Chain
5.5.5. Patient Monitoring
5.6. Analysis, Insights and Forecast - by End-User Industry
5.6.1. Retail & E-Commerce
5.6.2. Healthcare & Pharmaceuticals
5.6.3. Logistics
5.6.4. Aviation
5.6.5. Public Transit
5.6.6. BFSI
5.7. Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. Chipless RFID Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. Tag
6.1.2. Reader
6.1.3. Middleware
6.2. Analysis, Insights and Forecast - by Printing Technology
6.2.1. Ink-Jet
6.2.2. Screen
6.2.3. Flexographic
6.3. Analysis, Insights and Forecast - by Operating Frequency
6.3.1. LF 125-134 kHz
6.3.2. HF
6.3.3. UHF
6.4. Analysis, Insights and Forecast - by Material
6.4.1. Silver-Nano Ink
6.4.2. Copper-Based Ink
6.4.3. Graphene-Based Ink
6.5. Analysis, Insights and Forecast - by Application
6.5.1. Smart Cards
6.5.2. Smart Tickets
6.5.3. Brand & Document Authentication
6.5.4. Supply Chain
6.5.5. Patient Monitoring
6.6. Analysis, Insights and Forecast - by End-User Industry
6.6.1. Retail & E-Commerce
6.6.2. Healthcare & Pharmaceuticals
6.6.3. Logistics
6.6.4. Aviation
6.6.5. Public Transit
6.6.6. BFSI
7. Chipless RFID Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. Tag
7.1.2. Reader
7.1.3. Middleware
7.2. Analysis, Insights and Forecast - by Printing Technology
7.2.1. Ink-Jet
7.2.2. Screen
7.2.3. Flexographic
7.3. Analysis, Insights and Forecast - by Operating Frequency
7.3.1. LF 125-134 kHz
7.3.2. HF
7.3.3. UHF
7.4. Analysis, Insights and Forecast - by Material
7.4.1. Silver-Nano Ink
7.4.2. Copper-Based Ink
7.4.3. Graphene-Based Ink
7.5. Analysis, Insights and Forecast - by Application
7.5.1. Smart Cards
7.5.2. Smart Tickets
7.5.3. Brand & Document Authentication
7.5.4. Supply Chain
7.5.5. Patient Monitoring
7.6. Analysis, Insights and Forecast - by End-User Industry
7.6.1. Retail & E-Commerce
7.6.2. Healthcare & Pharmaceuticals
7.6.3. Logistics
7.6.4. Aviation
7.6.5. Public Transit
7.6.6. BFSI
8. Chipless RFID Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. Tag
8.1.2. Reader
8.1.3. Middleware
8.2. Analysis, Insights and Forecast - by Printing Technology
8.2.1. Ink-Jet
8.2.2. Screen
8.2.3. Flexographic
8.3. Analysis, Insights and Forecast - by Operating Frequency
8.3.1. LF 125-134 kHz
8.3.2. HF
8.3.3. UHF
8.4. Analysis, Insights and Forecast - by Material
8.4.1. Silver-Nano Ink
8.4.2. Copper-Based Ink
8.4.3. Graphene-Based Ink
8.5. Analysis, Insights and Forecast - by Application
8.5.1. Smart Cards
8.5.2. Smart Tickets
8.5.3. Brand & Document Authentication
8.5.4. Supply Chain
8.5.5. Patient Monitoring
8.6. Analysis, Insights and Forecast - by End-User Industry
8.6.1. Retail & E-Commerce
8.6.2. Healthcare & Pharmaceuticals
8.6.3. Logistics
8.6.4. Aviation
8.6.5. Public Transit
8.6.6. BFSI
9. Chipless RFID Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. Tag
9.1.2. Reader
9.1.3. Middleware
9.2. Analysis, Insights and Forecast - by Printing Technology
9.2.1. Ink-Jet
9.2.2. Screen
9.2.3. Flexographic
9.3. Analysis, Insights and Forecast - by Operating Frequency
9.3.1. LF 125-134 kHz
9.3.2. HF
9.3.3. UHF
9.4. Analysis, Insights and Forecast - by Material
9.4.1. Silver-Nano Ink
9.4.2. Copper-Based Ink
9.4.3. Graphene-Based Ink
9.5. Analysis, Insights and Forecast - by Application
9.5.1. Smart Cards
9.5.2. Smart Tickets
9.5.3. Brand & Document Authentication
9.5.4. Supply Chain
9.5.5. Patient Monitoring
9.6. Analysis, Insights and Forecast - by End-User Industry
9.6.1. Retail & E-Commerce
9.6.2. Healthcare & Pharmaceuticals
9.6.3. Logistics
9.6.4. Aviation
9.6.5. Public Transit
9.6.6. BFSI
10. Chipless RFID Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. Tag
10.1.2. Reader
10.1.3. Middleware
10.2. Analysis, Insights and Forecast - by Printing Technology
10.2.1. Ink-Jet
10.2.2. Screen
10.2.3. Flexographic
10.3. Analysis, Insights and Forecast - by Operating Frequency
10.3.1. LF 125-134 kHz
10.3.2. HF
10.3.3. UHF
10.4. Analysis, Insights and Forecast - by Material
10.4.1. Silver-Nano Ink
10.4.2. Copper-Based Ink
10.4.3. Graphene-Based Ink
10.5. Analysis, Insights and Forecast - by Application
10.5.1. Smart Cards
10.5.2. Smart Tickets
10.5.3. Brand & Document Authentication
10.5.4. Supply Chain
10.5.5. Patient Monitoring
10.6. Analysis, Insights and Forecast - by End-User Industry
10.6.1. Retail & E-Commerce
10.6.2. Healthcare & Pharmaceuticals
10.6.3. Logistics
10.6.4. Aviation
10.6.5. Public Transit
10.6.6. BFSI
11. Chipless RFID Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Chipless RFID Market Research Methodology
List of Figures
Figure 1: Chipless RFID Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Chipless RFID Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Chipless RFID Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Chipless RFID Market Revenue (Billion), by Printing Technology 2026 & 2034
Figure 5: North America Chipless RFID Market Revenue Share (%), by Printing Technology 2026 & 2034
Figure 6: North America Chipless RFID Market Revenue (Billion), by Operating Frequency 2026 & 2034
Figure 7: North America Chipless RFID Market Revenue Share (%), by Operating Frequency 2026 & 2034
Figure 8: North America Chipless RFID Market Revenue (Billion), by Material 2026 & 2034
Figure 9: North America Chipless RFID Market Revenue Share (%), by Material 2026 & 2034
Figure 10: North America Chipless RFID Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Chipless RFID Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Chipless RFID Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 13: North America Chipless RFID Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 14: North America Chipless RFID Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Chipless RFID Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Chipless RFID Market Revenue (Billion), by Product Type 2026 & 2034
List of Tables
Table 1: Chipless RFID Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Chipless RFID Market Revenue Billion Forecast, by Printing Technology 2020 & 2034
Table 3: Chipless RFID Market Revenue Billion Forecast, by Operating Frequency 2020 & 2034
Table 4: Chipless RFID Market Revenue Billion Forecast, by Material 2020 & 2034
Table 5: Chipless RFID Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Chipless RFID Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 7: Chipless RFID Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Chipless RFID Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 9: North America Chipless RFID Market Revenue Billion Forecast, by Printing Technology 2020 & 2034
Table 10: North America Chipless RFID Market Revenue Billion Forecast, by Operating Frequency 2020 & 2034
Table 11: North America Chipless RFID Market Revenue Billion Forecast, by Material 2020 & 2034
Table 12: North America Chipless RFID Market Revenue Billion Forecast, by Application 2020 & 2034
Table 13: North America Chipless RFID Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 14: North America Chipless RFID Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Chipless RFID Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Chipless RFID Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is chipless RFID?
Chipless RFID uses printed conductive signatures — not silicon chips — to encode identification data on tags. Eliminating the integrated circuit cuts per-tag cost below USD 0.05, enabling disposable and high-volume tracking.
2. How big is the chipless RFID market?
The narrow-scope market is valued at USD 2.16 billion in 2026 and is forecast to reach USD 6.49 billion by 2031, growing at a 24.68% CAGR.
3. What is driving chipless RFID adoption?
Sub-5-cent tag economics in Asian FMCG packaging, EU excise-stamp mandates, printable conductive-ink advances, and cold-chain passive sensing collectively add roughly 21% to the CAGR forecast.
4. Which region leads the chipless RFID market?
Asia-Pacific leads with 39.3% of 2025 revenue, driven by FMCG converters. The Middle East & Africa is the fastest-growing region at a 26.9% CAGR through 2031.
5. Who are the leading chipless RFID vendors?
Zebra Technologies, Avery Dennison, Alien Technology, Smartrac, SATO Holdings, Impinj, BASF, Dai Nippon Printing, and Toppan Forms lead a medium-concentration market where no vendor exceeds 15% share.
6. What limits chipless RFID growth?
Read range peaks near 3 m versus over 10 m for chipped UHF, forcing denser reader deployment. Absence of harmonized ISO/IEC encoding standards and moisture vulnerability further restrain adoption.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis rests on a disciplined 70/30 primary-to-secondary research split. Throughout the study period we conducted structured depth interviews across the full value chain — functional ink and substrate suppliers, tag and inlay converters, reader and middleware OEMs, and global distribution partners — capturing both supply-side capacity signals and demand-side adoption intent.
Interviews were stratified by decision-maker designation to separate technical feasibility from commercial reality: VP-level Sourcing leads, Heads of R&D and printed-electronics engineering, Technical Directors, and Commercial Operations Leads. This four-tier structure let us test whether stated roadmap capabilities were matched by actual procurement budgets.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory & Quality Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Ink & Substrate Suppliers
30%
Tag & Inlay Converters
35%
Reader & Middleware OEMs
20%
Distributors & Integrators
15%
Secondary Benchmarking & Public Trade Validation
Every primary insight was cross-checked against official multilateral and corporate sources: UN Comtrade and WTO trade-flow databases, US ITC and Eurostat shipment records, SEC 10-K filings and annual investor presentations, patent databases for conductive-ink and antenna IP, and recognized technical standards bodies including ISO and IEEE. Competitor market-research publications were deliberately excluded from the evidence base.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic and industry-segment demand to chipless RFID; the bottom-up path builds from converter capacity, per-tag pricing, and end-use consumption. Reconciling the two produces the triangulated base-year valuation and forecast band.


 Chipless RFID Market