Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Studio Camera System Market: 2026 Strategy & Forecast
Studio Camera System Market
Studio Camera System Market: 2026 Strategy & Forecast
Studio Camera System Market by Type (2K, 4K, 8K, Other), by Signal Architecture (SDI-Based, IP-Based, Hybrid SDI/IP), by System Configuration (Single-Camera System, Multi-Camera System, Centralized Control System), by Application (Broadcasters, Production Companies, Sports Venues, Educational Institutions), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
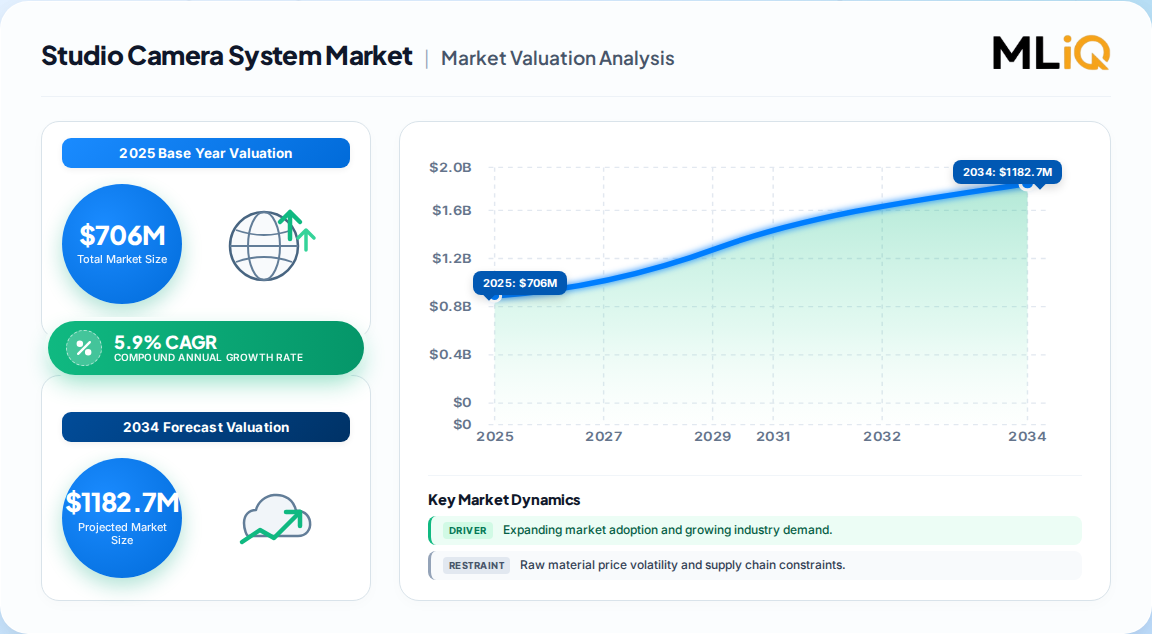
Scope: Global. The Studio Camera System Market is valued at 706 Million in 2025, forecast to reach 1,053 Million by 2032 at a 5.9% CAGR (2026–2032).
Volume is approximately 3,900 systems in 2025 at an average selling price near 185,000 per system, implying a 30%–50% gross margin structure.
4K is the dominant production tier while 8K remains a selective, premium-adoption workflow; IP and hybrid SDI/IP architectures are the primary architecture battleground.
Asia Pacific grows fastest at 7.2% CAGR, ahead of Latin America (6.2%), MEA (5.5%), Europe (4.8%) and North America (4.4%).
Broadcasters and production companies together account for roughly 48% of application demand; sports venues and educational institutions contribute the balance.
Sony, Panasonic, Grass Valley, Hitachi Kokusai, Blackmagic Design, Canon, JVCKENWOOD and ARRI anchor a medium-concentration vendor field.
Why this matters for decision-makers: Vendors that do not deliver IP-native, multi-camera color-matched systems with strong service SLAs will lose share to integrated fiber/IP incumbents as studios converge around fewer, more capable platforms.
Studio Camera System Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
706.0 M
2025
748.0 M
2026
792.0 M
2027
839.0 M
2028
888.0 M
2029
940.0 M
2030
996.0 M
2031
Studio Camera System Market Size (In Million)
Year
Market Size
2025
706.0 M
2026
748.0 M
2027
792.0 M
2028
839.0 M
2029
888.0 M
2030
940.0 M
2031
996.0 M
What is the Studio Camera System Market?
The Studio Camera System market covers professional broadcast imaging systems built for fixed installation in television studios and large production environments. A system typically bundles camera head, camera control unit (CCU), viewfinder, optical or fiber transmission, and centralized control interfaces for multi-camera color matching and long-distance signal transport.
Scope: what this report covers and excludes
This analysis covers global studio camera system demand by resolution tier, signal architecture, system configuration and end application. It addresses fixed-installation professional broadcast systems, not consumer or prosumer camcorders. This analysis does not cover adjacent markets such as multi-camera automotive ADAS systems, smart-city surveillance arrays, or robotic vision systems, which follow different regulatory and procurement logic.
How big is the market for Studio Camera System Market?
The Studio Camera System market is most defensibly sized at 706 Million in 2025, with a 2032 forecast of 1,053 Million at 5.9% CAGR, supported by a clearly stated unit volume and price benchmark. Competing published estimates diverge mainly because of scope definitions rather than demand disagreement.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
706 Million
2025
2032
5.9%
Fixed-install studio systems; 2K/4K/8K; broadcast, production, sports, education
One published strategic research estimate
2.47 Billion
2025
2031
8.88%
Multi-camera systems incl. automotive, smart-city, industrial
A competing analysis
2.32 Billion
2025
2035
8.31%
Multi-camera systems across all end-user industries
A competing analysis
The higher figures reflect multi-camera demand that is dominated by automotive safety mandates, not studio workflows. Our analysis suggests the 706 Million figure is the only estimate aligned to studio-specific unit economics (roughly 3,900 systems at 185,000 ASP). Buyers comparing these figures without a scope check will systematically overstate studio TAM by a factor of three or more.
How is the market segmented?
The market segments along four non-geographic axes: resolution tier, signal architecture, system configuration and application. Resolution and architecture are the two dimensions that most directly determine price band and upgrade timing for buyers.
Parent segment
Children
By Type / Resolution
2K, 4K, 8K, Other
By Signal Architecture
SDI-Based, IP-Based, Hybrid SDI/IP
By System Configuration
Single-Camera, Multi-Camera, Centralized Control
By Application
Broadcasters, Production Companies, Sports Venues, Educational Institutions
Our analysis suggests the most commercially consequential split is architecture: IP-based and hybrid systems carry higher software and service attach, which is where margin expansion will concentrate through 2032.
Which region leads in Studio Camera System Market?
Asia Pacific leads growth momentum at 7.2% CAGR, followed by Latin America at 6.2%, while North America and Europe remain the largest installed bases but grow at 4.4% and 4.8% respectively. Europe and North America together still likely hold roughly half of global value.
Studio Camera System Market Regional Market Share
Loading chart...
Studio Camera System Market Regional Market Share
Region
Market Share (%)
North America
0.26%
Europe
0.24%
Asia-Pacific
0.31%
South America
0.08%
Middle East & Africa
0.11%
Asia Pacific — China, Japan, South Korea, Southeast Asia, India, Australia, Rest of Asia Pacific
North America — United States, Canada, Mexico, Rest of North America
Europe — Germany, France, UK, Italy, Russia, Rest of Europe
Latin America — Brazil, Rest of Latin America
Middle East & Africa — Egypt, South Africa, Israel, Turkey, GCC Countries, Rest of MEA
This divergence implies that capacity and channel investment should follow Asia Pacific demand growth, while service and after-sales revenue pools stay anchored in mature broadcast markets. Precise country-level share data is not available in the public domain; the full report models it.
What is driving growth — and what is holding it back?
HD-to-4K upgrades, IP-based studio architectures and remote production capability are the strongest demand drivers, while high system costs and slow broadcaster refresh cycles cap the pace of replacement. The balance favors steady, mid-single-digit growth rather than a step change.
Factor
Direction
Evidence strength
Mechanism
HD-to-4K and selective 8K upgrades
Driver
High
Raises ASP and forces multi-camera color-matched replacement
IP and hybrid SDI/IP studio architectures
Driver
High
Lowers cabling cost, enables remote production and centralized control
Sports venue and education studio builds
Driver
Medium
Adds fixed multi-camera installations outside traditional broadcast
High system and integration cost
Restraint
High
Delays refresh cycles, especially in mid-tier broadcasters
Raises integration risk and procurement complexity
Our analysis suggests the drivers are structural and the restraints are cyclical, which supports a base case of sustained 5%–6% growth rather than acceleration.
Who are the leading vendors?
Sony and Panasonic lead on installed base and sensor-to-system integration, while Grass Valley, Hitachi Kokusai, Blackmagic Design, Canon, JVCKENWOOD and ARRI compete on workflow, price-performance and premium cinema-adjacent capability. Competition centers on color science consistency, reliability and IP workflow compatibility.
Vendor
Core strength
Positioning
Sony Corporation
Sensor and system integration
Premium broadcast incumbent
Panasonic Corporation
Studio and PTZ workflow breadth
Broad installed base
Grass Valley USA LLC
Live production and IP workflow
Workflow-led differentiation
Hitachi Kokusai Electric
Broadcast studio systems
Reliability and service
Blackmagic Design
Price-performance and ecosystem
Value-tier disruptor
Canon
Optics and color science
Premium imaging
JVCKENWOOD
Studio and field systems
Mid-market reach
ARRI
Premium cinema and studio
High-end niche
This divergence implies that moats are built on service networks and workflow lock-in rather than on sensor specifications alone.
What do buyers and operators need to know? (Decision Support)
Buyers should prioritize color-match consistency across the full camera chain, CCU and transport redundancy, and proven IP/SDI interoperability with existing switchers and routers. Procurement risk concentrates in multi-vendor integration and firmware lifecycle commitments, not in image quality alone.
Switching costs are high because a studio camera system is a decade-scale asset tied to control-room infrastructure, lens mounts and operator training. Buyers should demand explicit firmware support horizons, service-level agreements and upgrade paths to 4K and 8K before signing. Regulatory and standards compliance (broadcast transport, EMC, safety) should be validated at the system level, not per component.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a steady mid-single-digit growth market where value migrates from hardware to workflow software and service. The strongest counter-argument is that a faster 8K adoption cycle or a wave of IP refresh spending could push growth toward the high single digits; we regard this as plausible but not base case, given long broadcast replacement cycles. Our analysis suggests the 5.9% CAGR is the most defensible anchor for planning.
Vendors: prioritize IP-native, multi-camera color-matched platforms with service SLAs to defend margin as hardware commoditizes.
Investors: favor exposure to workflow software, CCU/transport and after-sales service rather than camera-head assembly.
Operators: lock firmware and upgrade commitments into procurement contracts to protect decade-scale assets.
What would change our conclusion: sustained 8K studio adoption, a regulatory mandate accelerating IP transition, or evidence of materially shorter replacement cycles. While this overview covers the strategic shape of the market, precise sub-segment and country-level forecasting requires the full report's modeled datasets.
Studio Camera System Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Studio Camera System Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.9% from 2020-2034
Segmentation
By Type
2K
4K
8K
Other
By Signal Architecture
SDI-Based
IP-Based
Hybrid SDI/IP
By System Configuration
Single-Camera System
Multi-Camera System
Centralized Control System
By Application
Broadcasters
Production Companies
Sports Venues
Educational Institutions
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Studio Camera System Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Studio Camera System Market Executive Summary
2.1. Market Snapshot
3. Studio Camera System Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Studio Camera System Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Studio Camera System Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. 2K
5.1.2. 4K
5.1.3. 8K
5.1.4. Other
5.2. Analysis, Insights and Forecast - by Signal Architecture
5.2.1. SDI-Based
5.2.2. IP-Based
5.2.3. Hybrid SDI/IP
5.3. Analysis, Insights and Forecast - by System Configuration
5.3.1. Single-Camera System
5.3.2. Multi-Camera System
5.3.3. Centralized Control System
5.4. Analysis, Insights and Forecast - by Application
5.4.1. Broadcasters
5.4.2. Production Companies
5.4.3. Sports Venues
5.4.4. Educational Institutions
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Studio Camera System Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. 2K
6.1.2. 4K
6.1.3. 8K
6.1.4. Other
6.2. Analysis, Insights and Forecast - by Signal Architecture
6.2.1. SDI-Based
6.2.2. IP-Based
6.2.3. Hybrid SDI/IP
6.3. Analysis, Insights and Forecast - by System Configuration
6.3.1. Single-Camera System
6.3.2. Multi-Camera System
6.3.3. Centralized Control System
6.4. Analysis, Insights and Forecast - by Application
6.4.1. Broadcasters
6.4.2. Production Companies
6.4.3. Sports Venues
6.4.4. Educational Institutions
7. Studio Camera System Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. 2K
7.1.2. 4K
7.1.3. 8K
7.1.4. Other
7.2. Analysis, Insights and Forecast - by Signal Architecture
7.2.1. SDI-Based
7.2.2. IP-Based
7.2.3. Hybrid SDI/IP
7.3. Analysis, Insights and Forecast - by System Configuration
7.3.1. Single-Camera System
7.3.2. Multi-Camera System
7.3.3. Centralized Control System
7.4. Analysis, Insights and Forecast - by Application
7.4.1. Broadcasters
7.4.2. Production Companies
7.4.3. Sports Venues
7.4.4. Educational Institutions
8. Studio Camera System Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. 2K
8.1.2. 4K
8.1.3. 8K
8.1.4. Other
8.2. Analysis, Insights and Forecast - by Signal Architecture
8.2.1. SDI-Based
8.2.2. IP-Based
8.2.3. Hybrid SDI/IP
8.3. Analysis, Insights and Forecast - by System Configuration
8.3.1. Single-Camera System
8.3.2. Multi-Camera System
8.3.3. Centralized Control System
8.4. Analysis, Insights and Forecast - by Application
8.4.1. Broadcasters
8.4.2. Production Companies
8.4.3. Sports Venues
8.4.4. Educational Institutions
9. Studio Camera System Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. 2K
9.1.2. 4K
9.1.3. 8K
9.1.4. Other
9.2. Analysis, Insights and Forecast - by Signal Architecture
9.2.1. SDI-Based
9.2.2. IP-Based
9.2.3. Hybrid SDI/IP
9.3. Analysis, Insights and Forecast - by System Configuration
9.3.1. Single-Camera System
9.3.2. Multi-Camera System
9.3.3. Centralized Control System
9.4. Analysis, Insights and Forecast - by Application
9.4.1. Broadcasters
9.4.2. Production Companies
9.4.3. Sports Venues
9.4.4. Educational Institutions
10. Studio Camera System Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. 2K
10.1.2. 4K
10.1.3. 8K
10.1.4. Other
10.2. Analysis, Insights and Forecast - by Signal Architecture
10.2.1. SDI-Based
10.2.2. IP-Based
10.2.3. Hybrid SDI/IP
10.3. Analysis, Insights and Forecast - by System Configuration
10.3.1. Single-Camera System
10.3.2. Multi-Camera System
10.3.3. Centralized Control System
10.4. Analysis, Insights and Forecast - by Application
10.4.1. Broadcasters
10.4.2. Production Companies
10.4.3. Sports Venues
10.4.4. Educational Institutions
11. Studio Camera System Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Studio Camera System Market Research Methodology
List of Figures
Figure 1: Studio Camera System Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: Studio Camera System Market Volume Breakdown (Units, %) by Region 2026 & 2034
Figure 3: North America Studio Camera System Market Revenue (Million), by Type 2026 & 2034
Figure 4: North America Studio Camera System Market Volume (Units), by Type 2026 & 2034
Figure 5: North America Studio Camera System Market Revenue Share (%), by Type 2026 & 2034
Figure 6: North America Studio Camera System Market Volume Share (%), by Type 2026 & 2034
Figure 7: North America Studio Camera System Market Revenue (Million), by Signal Architecture 2026 & 2034
Figure 8: North America Studio Camera System Market Volume (Units), by Signal Architecture 2026 & 2034
Figure 9: North America Studio Camera System Market Revenue Share (%), by Signal Architecture 2026 & 2034
Figure 10: North America Studio Camera System Market Volume Share (%), by Signal Architecture 2026 & 2034
Figure 11: North America Studio Camera System Market Revenue (Million), by System Configuration 2026 & 2034
Figure 12: North America Studio Camera System Market Volume (Units), by System Configuration 2026 & 2034
Figure 13: North America Studio Camera System Market Revenue Share (%), by System Configuration 2026 & 2034
Figure 14: North America Studio Camera System Market Volume Share (%), by System Configuration 2026 & 2034
Figure 15: North America Studio Camera System Market Revenue (Million), by Application 2026 & 2034
North America Studio Camera System Market Volume (Units), by Application 2026 & 2034
List of Tables
Table 1: Studio Camera System Market Revenue Million Forecast, by Type 2020 & 2034
Table 2: Studio Camera System Market Volume Units Forecast, by Type 2020 & 2034
Table 3: Studio Camera System Market Revenue Million Forecast, by Signal Architecture 2020 & 2034
Table 4: Studio Camera System Market Volume Units Forecast, by Signal Architecture 2020 & 2034
Table 5: Studio Camera System Market Revenue Million Forecast, by System Configuration 2020 & 2034
Table 6: Studio Camera System Market Volume Units Forecast, by System Configuration 2020 & 2034
Table 7: Studio Camera System Market Revenue Million Forecast, by Application 2020 & 2034
Table 8: Studio Camera System Market Volume Units Forecast, by Application 2020 & 2034
Table 9: Studio Camera System Market Revenue Million Forecast, by Region 2020 & 2034
Table 10: Studio Camera System Market Volume Units Forecast, by Region 2020 & 2034
Table 11: North America Studio Camera System Market Revenue Million Forecast, by Type 2020 & 2034
Table 12: North America Studio Camera System Market Volume Units Forecast, by Type 2020 & 2034
Table 13: North America Studio Camera System Market Revenue Million Forecast, by Signal Architecture 2020 & 2034
Table 14: North America Studio Camera System Market Volume Units Forecast, by Signal Architecture 2020 & 2034
Table 15: North America Studio Camera System Market Revenue Million Forecast, by System Configuration 2020 & 2034
Table 16: North America Studio Camera System Market Volume Units Forecast, by System Configuration 2020 & 2034
Frequently Asked Questions
1. How big is the Studio Camera System market?
The global Studio Camera System market is valued at approximately 706 Million in 2025 and is forecast to reach 1,053 Million by 2032, growing at a 5.9% CAGR over the 2026–2032 period.
2. What is the growth rate of the Studio Camera System market?
The market is expected to grow at a 5.9% CAGR from 2026 to 2032, driven by HD-to-4K upgrades, IP-based studio architectures and remote production adoption across broadcasters and production companies.
3. Which region grows fastest in the Studio Camera System market?
Asia Pacific grows fastest at approximately 7.2% CAGR, ahead of Latin America at 6.2%, while North America and Europe remain the largest installed bases with slower growth of 4.4% and 4.8% respectively.
4. Who are the leading vendors in the Studio Camera System market?
Leading vendors include Sony, Panasonic, Grass Valley, Hitachi Kokusai Electric, Blackmagic Design, Canon, JVCKENWOOD and ARRI, competing on color science, system reliability and IP workflow compatibility.
5. What are the main segments of the Studio Camera System market?
The market segments by resolution (2K, 4K, 8K, Other), signal architecture (SDI, IP, hybrid), system configuration (single-camera, multi-camera, centralized control) and application (broadcasters, production companies, sports venues, educational institutions).
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including image-sensor and optical component suppliers, camera-head and CCU manufacturers, system integrators and broadcast distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of Broadcast Engineering, Technical Directors and Commercial Operations Leads. Interviews validated unit pricing, refresh cycles and IP-transition timing.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Broadcast Engineering & Technical Directors
40%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory & Standards Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Camera Head & CCU Manufacturers
45%
Optical & Sensor Suppliers
25%
System Integrators
20%
Distributors & Channel Partners
10%
Secondary Benchmarking & Public Trade Validation
Estimates were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K and equivalent), patent databases, and recognized technical standards bodies and broadcast industry associations. No competitor market-research publications were used as validation sources.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous Top-Down (macroeconomic broadcast capex and segment allocation) and Bottom-Up (manufacturer capacity, system pricing and end-use consumption) models. Divergences were reconciled through triangulation, with unit-volume and average-selling-price cross-checks anchoring the base-year value.
 Studio Camera System Market