Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Optical Position Sensor Market: Size, Trends & Forecast 2035
Optical Position Sensor Market
Optical Position Sensor Market: Size, Trends & Forecast 2035
Optical Position Sensor Market by Type (Linear Position Sensors, Rotary Position Sensors), by Contact Type (Non-Contact Type, Contact Type), by Output (Digital Output, Analog Output), by Application (Machine Tools, Robotics, Motion Systems, Material Handling, Test Equipment, Inspection Systems, Measurement), by End-User (Manufacturing, Automotive, Aerospace, Packaging, Healthcare, Electronics, Others), by Asia Pacific (China, Japan, India, South Korea), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
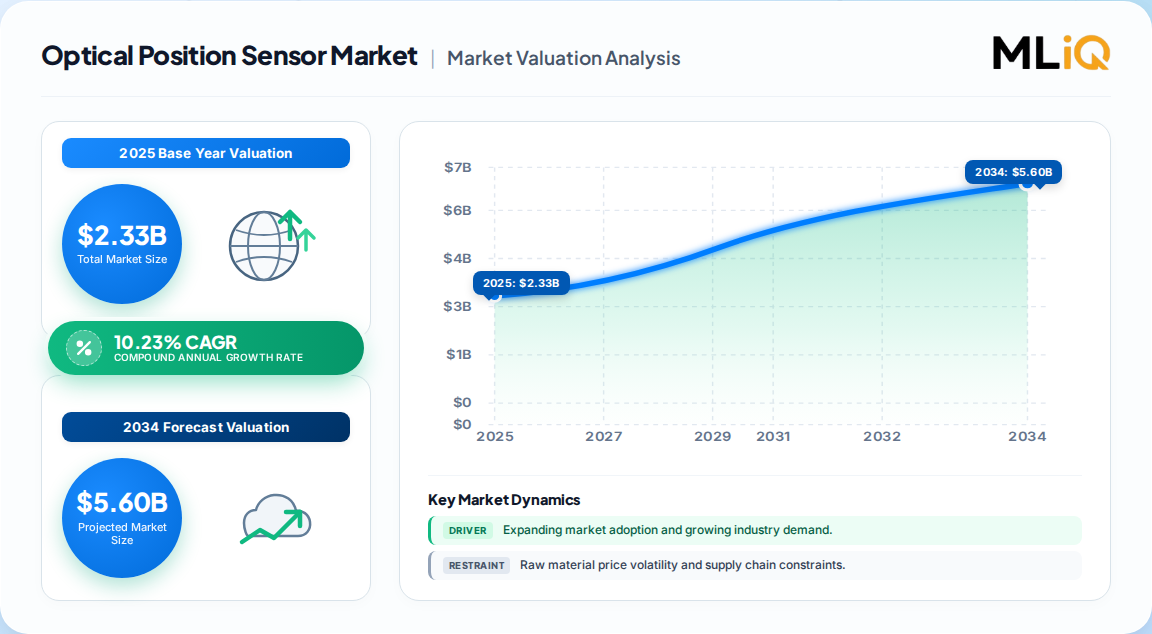
2.33 Billion in 2025 — the global optical position sensor market sits in the narrow slice of the broader position-sensor category, estimated at USD 2.326 Billion for the base year, growing to 6.16 Billion by 2035.
10.23 CAGR (2025–2035): this is roughly 2x the growth rate of the overall position sensor market (~8.1%), implying optical is taking share from magnetic and resistive technologies rather than simply riding category growth.
Linear position sensors hold the largest product-type share, while rotary sensors grow fastest — a split that maps to the slowdown in fixed CNC tooling versus the boom in articulated robotics.
Asia-Pacific leads with roughly 41% of global revenue, followed by North America (~25%) and Europe (~22%); Asia-Pacific is also the epicenter of rotary-sensor demand and price pressure.
Consolidated but contested: Honeywell, Omron, Texas Instruments, STMicroelectronics, Microchip, ams AG, Renesas, Broadcom and Infineon dominate, with semiconductor incumbents driving integration economics.
Fastest-growing application is robotics, outrunning machine tools — a decisive signal for product roadmaps.
Why this matters for decision-makers: the premium on resolution, non-contact durability and digital output means vendors that cannot deliver IO-Link-class digital integration will be squeezed into low-margin commodity segments within five years.
Optical Position Sensor Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.110 B
2024
2.330 B
2025
2.560 B
2026
2.830 B
2027
3.120 B
2028
3.430 B
2029
3.790 B
2030
Optical Position Sensor Market Size (In Billion)
Year
Market Size
2024
2.110 B
2025
2.330 B
2026
2.560 B
2027
2.830 B
2028
3.120 B
2029
3.430 B
2030
3.790 B
What is the Optical Position Sensor Market?
The optical position sensor market covers devices that measure linear or rotary displacement by converting light intensity, phase or beam interruption into a position signal. These are typically non-contact, high-resolution sensors used in machine tools, robotics, motion systems, material handling, test equipment and automotive systems.
Scope: what this report covers and excludes
This report covers optical position sensors by type (linear, rotary), contact type (non-contact, contact), output (digital, analog), application (machine tools, robotics, motion systems, material handling, test equipment, inspection and measurement) and end-user (manufacturing, automotive, aerospace, packaging, healthcare, electronics). This analysis does not cover the broader position sensor market, proximity-only sensors, optical encoders as a standalone category, or optical sensors used outside position measurement (temperature, biomedical, biometric).
How big is the market for Optical Position Sensor Market?
One published estimate places the global optical position sensor market at 2.326 Billion in 2025, rising to 6.163 Billion by 2035 at a 10.23% CAGR — but competing analyses of adjacent categories imply materially different trajectories, so the figures must be read with scope caution.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
2.11 Bn → 6.16 Bn
2024
2035
10.23%
Optical position sensors only (linear + rotary)
One published estimate
Optical sensors 31.4 Bn → 51.8 Bn
2025
2033
11.8%
All optical sensors, position sub-segment implied
A competing analysis
Position sensors 10.2 Bn → 17.6 Bn
2026
2033
8.1%
All position-sensing technologies incl. magnetic
A competing analysis
Position sensors 13.73 Bn → 22.49 Bn
2025
2032
7.3%
All position-sensing technologies
A competing analysis
Our analysis suggests the 2.33 Billion base and 10.23% CAGR are the most defensible figures for the optical-specific segment. The divergence between the 10.23% optical CAGR and the 7.3–8.1% all-technology CAGR is the single most important number here: optical is a share-gainer, driven by robotics precision demands and the retirement of contact-based wear parts.
How is the market segmented?
The segment structure is shaped by measurement geometry, contact method, signal format and application — with digital output and non-contact designs increasingly becoming the default specification rather than a premium option.
Parent
Children
By Type
Linear Position Sensors (largest), Rotary Position Sensors (fastest-growing)
By Contact Type
Non-Contact Type (largest), Contact Type (fastest-growing)
By Output
Digital Output (largest), Analog Output (fastest-growing)
By Application
Machine Tools (largest), Robotics (fastest), Motion Systems, Material Handling, Test Equipment, Inspection Systems, Measurement
Two segment readings deserve scrutiny. First, contact-type optics growing fastest is counterintuitive given the market's non-contact narrative; our analysis suggests this reflects low-cost edge-detection sensors in packaging and material handling rather than a reversal of the non-contact trend. Second, analog output labelled fastest-growing in one source while digital leads in another is a definitional conflict — many "digital" classifications include incremental pulse trains, not fieldbus-ready IO-Link.
Which region leads in Optical Position Sensor Market?
Asia-Pacific leads with roughly 41% of global optical position sensor revenue in 2025, supported by concentrated electronics manufacturing, automotive electrification and aggressive industrial automation investment across China, Japan and South Korea.
Optical Position Sensor Market Regional Market Share
Loading chart...
Optical Position Sensor Market Regional Market Share
Highest-value applications; strong OEM and ADAS presence
Europe
22%
Industrial automation and EV development; standards-driven
Latin America
6%
Emerging; import-dependent, moderate growth
Middle East & Africa
6%
Early-stage; project-led demand
This divergence implies a two-speed procurement landscape: Asian buyers will drive specification commoditization on linear sensors, while North American and European buyers will pay a premium for certified, high-reliability rotary and robotic sensing.
What is driving growth — and what is holding it back?
The dominant driver is robotics: industrial robot installations are expanding at more than 20% annually in key segments, and every articulated joint requires precise, non-contact position feedback, pulling optical sensors into direct competition with magnetic encoders.
The balance of evidence favors structural expansion, but the restraint side is underweighted in most published forecasts. Our analysis suggests cost-driven substitution by magnetic sensors remains the single largest threat to optical's volume growth, and it bites hardest in the high-volume, low-precision end of material handling and packaging.
Who are the leading vendors?
The competitive field is anchored by diversified sensor and semiconductor incumbents, but leadership is fragmented between industrial-automation specialists and chip-level integrators with materially different moats.
Company
Base
Positioning
Honeywell
US
Industrial and aerospace sensing portfolio; certification-led moat
Omron
JP
Factory automation and optical sensing integration
Texas Instruments
US
Analog and signal-chain silicon; design-win economics
STMicroelectronics
CH
Sensor IC integration; high-volume automotive
Microchip Technology
US
Mixed-signal and embedded sensing platforms
ams AG
AT
Optical and photonic sensing specialization
Renesas Electronics
JP
Automotive and industrial MCU-adjacent sensing
Broadcom
US
Optoelectronics and industrial components
Infineon Technologies
DE
Power, automotive and industrial sensing
The clearest differentiation axis is vertical integration. Semiconductor players win on cost and miniaturization; automation specialists win on application engineering, functional-safety credentials and installed-base lock-in. Our analysis suggests the mid-tier—firms with neither silicon control nor a certified application moat—faces the sharpest margin compression.
What do buyers and operators need to know?
Selection should be governed by resolution, repeatability and environmental durability rather than headline accuracy figures, because the total cost of an optical position sensor is dominated by integration, calibration and downtime, not unit price. Buyers should demand documented performance across the full thermal range, since drift outside −40°C to 125°C is a common failure mode.
Procurement risk concentrates in three areas: electromagnetic interference in dense industrial environments, where shielding and filtering requirements inflate system cost; long qualification cycles for automotive and aerospace use, where supplier switching can consume 12–24 months; and supply continuity, as semiconductor R&D shifts toward high-volume MEMS products and constrains niche industrial capacity.
Regulatory and standards compliance should be verified early — functional-safety certification for machinery, automotive qualification for vehicle applications, and EMC conformance for industrial installation. Operators should also insist on digital connectivity readiness (IO-Link or equivalent) to avoid premature obsolescence in Industry 4.0 environments.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a constructive, share-gain thesis: optical position sensing is expanding roughly twice as fast as the aggregate position sensor category, and the demand drivers are structural rather than cyclical. The strongest counter-argument is substitution — magnetic and inductive sensors are cheaper, adequate for most commodity motion tasks, and improving. We would answer that substitution displaces volume, not value: optical will capture the precision, non-contact and robotics-articulation tiers while ceding commodity detection.
The second-order effect most forecasts miss is specification bifurcation. Asia-Pacific volume growth will commoditize linear sensors, while North America and Europe will sustain premiums on certified rotary and robotic sensing. Vendors positioned in the middle — undifferentiated linear optics without digital integration — face the worst margin trajectory in the entire value chain.
Actionable strategy for the next 24 months:
Prioritize robotics-grade rotary and multi-axis sensing with digital fieldbus output; robotics is the fastest-growing application and commands defensible pricing.
Secure silicon or photonic supply control to survive cost competition; buy-side operators should dual-source critical optical sub-components well before qualification.
Build compliance and certification assets for automotive and machinery safety — these create switching costs that price competition cannot easily erode.
What would change our conclusion: a sustained collapse in magnetic-sensor pricing combined with a plateau in robot installation rates would flip the share-gain thesis. We would also revise downward if digital integration standards stall, which would cap the premium currently priced into optical solutions. Precise sub-segment forecasts by output type and application tier require the full report's modelled breakdown, where definitional conflicts in published output and contact-type data are reconciled.
Research Methodology
Primary Research & Industry Fieldwork
This study is built on a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with optical component suppliers, specialized sensor producers, contract manufacturers, systems integrators and global distributors. Decision-makers interviewed include VP-level sourcing executives, heads of sensor R&D, technical directors and commercial operations leads.
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and national customs data, corporate annual filings and investor presentations, patent databases, and technical standards published by industry associations and standards bodies. No competitor market-research output is cited as evidence.
Demand Modeling & Market Sizing Triangulation
Sizing is triangulated simultaneously top-down (macroeconomic and end-use segment allocation) and bottom-up (manufacturer capacity, product pricing and end-use consumption modeling), with reconciliation against trade-flow evidence.
ISO and IEC technical standards for industrial sensing and EMC
Corporate 10-K, annual report and investor filings
Optical Position Sensor Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Optical Position Sensor Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.23% from 2020-2034
Segmentation
By Type
Linear Position Sensors
Rotary Position Sensors
By Contact Type
Non-Contact Type
Contact Type
By Output
Digital Output
Analog Output
By Application
Machine Tools
Robotics
Motion Systems
Material Handling
Test Equipment
Inspection Systems
Measurement
By End-User
Manufacturing
Automotive
Aerospace
Packaging
Healthcare
Electronics
Others
By Geography
Asia Pacific
China
Japan
India
South Korea
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Optical Position Sensor Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Optical Position Sensor Market Executive Summary
2.1. Market Snapshot
3. Optical Position Sensor Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Optical Position Sensor Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Optical Position Sensor Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Linear Position Sensors
5.1.2. Rotary Position Sensors
5.2. Analysis, Insights and Forecast - by Contact Type
5.2.1. Non-Contact Type
5.2.2. Contact Type
5.3. Analysis, Insights and Forecast - by Output
5.3.1. Digital Output
5.3.2. Analog Output
5.4. Analysis, Insights and Forecast - by Application
5.4.1. Machine Tools
5.4.2. Robotics
5.4.3. Motion Systems
5.4.4. Material Handling
5.4.5. Test Equipment
5.4.6. Inspection Systems
5.4.7. Measurement
5.5. Analysis, Insights and Forecast - by End-User
5.5.1. Manufacturing
5.5.2. Automotive
5.5.3. Aerospace
5.5.4. Packaging
5.5.5. Healthcare
5.5.6. Electronics
5.5.7. Others
5.6. Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Optical Position Sensor Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Linear Position Sensors
6.1.2. Rotary Position Sensors
6.2. Analysis, Insights and Forecast - by Contact Type
6.2.1. Non-Contact Type
6.2.2. Contact Type
6.3. Analysis, Insights and Forecast - by Output
6.3.1. Digital Output
6.3.2. Analog Output
6.4. Analysis, Insights and Forecast - by Application
6.4.1. Machine Tools
6.4.2. Robotics
6.4.3. Motion Systems
6.4.4. Material Handling
6.4.5. Test Equipment
6.4.6. Inspection Systems
6.4.7. Measurement
6.5. Analysis, Insights and Forecast - by End-User
6.5.1. Manufacturing
6.5.2. Automotive
6.5.3. Aerospace
6.5.4. Packaging
6.5.5. Healthcare
6.5.6. Electronics
6.5.7. Others
7. Optical Position Sensor Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Linear Position Sensors
7.1.2. Rotary Position Sensors
7.2. Analysis, Insights and Forecast - by Contact Type
7.2.1. Non-Contact Type
7.2.2. Contact Type
7.3. Analysis, Insights and Forecast - by Output
7.3.1. Digital Output
7.3.2. Analog Output
7.4. Analysis, Insights and Forecast - by Application
7.4.1. Machine Tools
7.4.2. Robotics
7.4.3. Motion Systems
7.4.4. Material Handling
7.4.5. Test Equipment
7.4.6. Inspection Systems
7.4.7. Measurement
7.5. Analysis, Insights and Forecast - by End-User
7.5.1. Manufacturing
7.5.2. Automotive
7.5.3. Aerospace
7.5.4. Packaging
7.5.5. Healthcare
7.5.6. Electronics
7.5.7. Others
8. Optical Position Sensor Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Linear Position Sensors
8.1.2. Rotary Position Sensors
8.2. Analysis, Insights and Forecast - by Contact Type
8.2.1. Non-Contact Type
8.2.2. Contact Type
8.3. Analysis, Insights and Forecast - by Output
8.3.1. Digital Output
8.3.2. Analog Output
8.4. Analysis, Insights and Forecast - by Application
8.4.1. Machine Tools
8.4.2. Robotics
8.4.3. Motion Systems
8.4.4. Material Handling
8.4.5. Test Equipment
8.4.6. Inspection Systems
8.4.7. Measurement
8.5. Analysis, Insights and Forecast - by End-User
8.5.1. Manufacturing
8.5.2. Automotive
8.5.3. Aerospace
8.5.4. Packaging
8.5.5. Healthcare
8.5.6. Electronics
8.5.7. Others
9. Optical Position Sensor Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Linear Position Sensors
9.1.2. Rotary Position Sensors
9.2. Analysis, Insights and Forecast - by Contact Type
9.2.1. Non-Contact Type
9.2.2. Contact Type
9.3. Analysis, Insights and Forecast - by Output
9.3.1. Digital Output
9.3.2. Analog Output
9.4. Analysis, Insights and Forecast - by Application
9.4.1. Machine Tools
9.4.2. Robotics
9.4.3. Motion Systems
9.4.4. Material Handling
9.4.5. Test Equipment
9.4.6. Inspection Systems
9.4.7. Measurement
9.5. Analysis, Insights and Forecast - by End-User
9.5.1. Manufacturing
9.5.2. Automotive
9.5.3. Aerospace
9.5.4. Packaging
9.5.5. Healthcare
9.5.6. Electronics
9.5.7. Others
10. Optical Position Sensor Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Linear Position Sensors
10.1.2. Rotary Position Sensors
10.2. Analysis, Insights and Forecast - by Contact Type
10.2.1. Non-Contact Type
10.2.2. Contact Type
10.3. Analysis, Insights and Forecast - by Output
10.3.1. Digital Output
10.3.2. Analog Output
10.4. Analysis, Insights and Forecast - by Application
10.4.1. Machine Tools
10.4.2. Robotics
10.4.3. Motion Systems
10.4.4. Material Handling
10.4.5. Test Equipment
10.4.6. Inspection Systems
10.4.7. Measurement
10.5. Analysis, Insights and Forecast - by End-User
10.5.1. Manufacturing
10.5.2. Automotive
10.5.3. Aerospace
10.5.4. Packaging
10.5.5. Healthcare
10.5.6. Electronics
10.5.7. Others
11. Optical Position Sensor Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Optical Position Sensor Market Research Methodology
List of Figures
Figure 1: Optical Position Sensor Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Optical Position Sensor Market Revenue (Billion), by Type 2026 & 2034
Figure 3: Asia Pacific Optical Position Sensor Market Revenue Share (%), by Type 2026 & 2034
Figure 4: Asia Pacific Optical Position Sensor Market Revenue (Billion), by Contact Type 2026 & 2034
Figure 5: Asia Pacific Optical Position Sensor Market Revenue Share (%), by Contact Type 2026 & 2034
Figure 6: Asia Pacific Optical Position Sensor Market Revenue (Billion), by Output 2026 & 2034
Figure 7: Asia Pacific Optical Position Sensor Market Revenue Share (%), by Output 2026 & 2034
Figure 8: Asia Pacific Optical Position Sensor Market Revenue (Billion), by Application 2026 & 2034
Figure 9: Asia Pacific Optical Position Sensor Market Revenue Share (%), by Application 2026 & 2034
Figure 10: Asia Pacific Optical Position Sensor Market Revenue (Billion), by End-User 2026 & 2034
Figure 11: Asia Pacific Optical Position Sensor Market Revenue Share (%), by End-User 2026 & 2034
Figure 12: Asia Pacific Optical Position Sensor Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific Optical Position Sensor Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Optical Position Sensor Market Revenue (Billion), by Type 2026 & 2034
Figure 15: North America Optical Position Sensor Market Revenue Share (%), by Type 2026 & 2034
Figure 16: North America Optical Position Sensor Market Revenue (Billion), by Contact Type 2026 & 2034
List of Tables
Table 1: Optical Position Sensor Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Optical Position Sensor Market Revenue Billion Forecast, by Contact Type 2020 & 2034
Table 3: Optical Position Sensor Market Revenue Billion Forecast, by Output 2020 & 2034
Table 4: Optical Position Sensor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Optical Position Sensor Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 6: Optical Position Sensor Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Optical Position Sensor Market Revenue Billion Forecast, by Type 2020 & 2034
Table 8: Asia Pacific Optical Position Sensor Market Revenue Billion Forecast, by Contact Type 2020 & 2034
Table 9: Asia Pacific Optical Position Sensor Market Revenue Billion Forecast, by Output 2020 & 2034
Table 10: Asia Pacific Optical Position Sensor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: Asia Pacific Optical Position Sensor Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 12: Asia Pacific Optical Position Sensor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Optical Position Sensor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan Optical Position Sensor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: India Optical Position Sensor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: South Korea Optical Position Sensor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the optical position sensor market?
The global optical position sensor market was estimated at approximately 2.33 Billion in 2025 and is forecast to reach 6.16 Billion by 2035 at a 10.23% CAGR, per one published estimate.
2. What is the growth rate of the optical position sensor market?
The market is projected to grow at a 10.23% compound annual rate from 2025 to 2035, roughly double the growth rate of the broader all-technology position sensor market.
3. Which region dominates optical position sensor demand?
Asia-Pacific leads with approximately 41% of global revenue, followed by North America at 25% and Europe at 22%, driven by electronics manufacturing and industrial automation.
4. Which application is growing fastest for optical position sensors?
Robotics is the fastest-growing application, overtaking machine tools, because each robot axis requires precise non-contact position feedback and robot installations are expanding above 20% annually.
5. Who are the leading optical position sensor vendors?
Key players include Honeywell, Omron, Texas Instruments, STMicroelectronics, Microchip Technology, ams AG, Renesas, Broadcom and Infineon, spanning industrial automation and semiconductor supply.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study rests on a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including photonic component suppliers, specialized optical sensor producers, contract manufacturing partners, systems integrators and global industrial distributors. Interviewees included VP-level sourcing executives, heads of sensor R&D, technical directors and commercial operations leads, ensuring both technical and commercial perspectives are represented in the demand model.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
30%
R&D and Technical Directors
35%
Commercial Operations Leads
20%
Quality & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Optical Component & Photonic Suppliers
30%
Specialized Sensor Producers
35%
Contract Manufacturers & Integrators
20%
Global Distributors & Traders
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent databases, and recognized technical standards and industry associations. Trading partner data is used to reconcile regional consumption estimates against reported export flows.
Demand Modeling & Market Sizing Triangulation
Sizing is triangulated simultaneously top-down (macroeconomic and end-use segment allocation) and bottom-up (manufacturer capacity, product pricing and end-use consumption modeling), with reconciliation against cross-border trade evidence and installed-base replacement dynamics.


 Optical Position Sensor Market