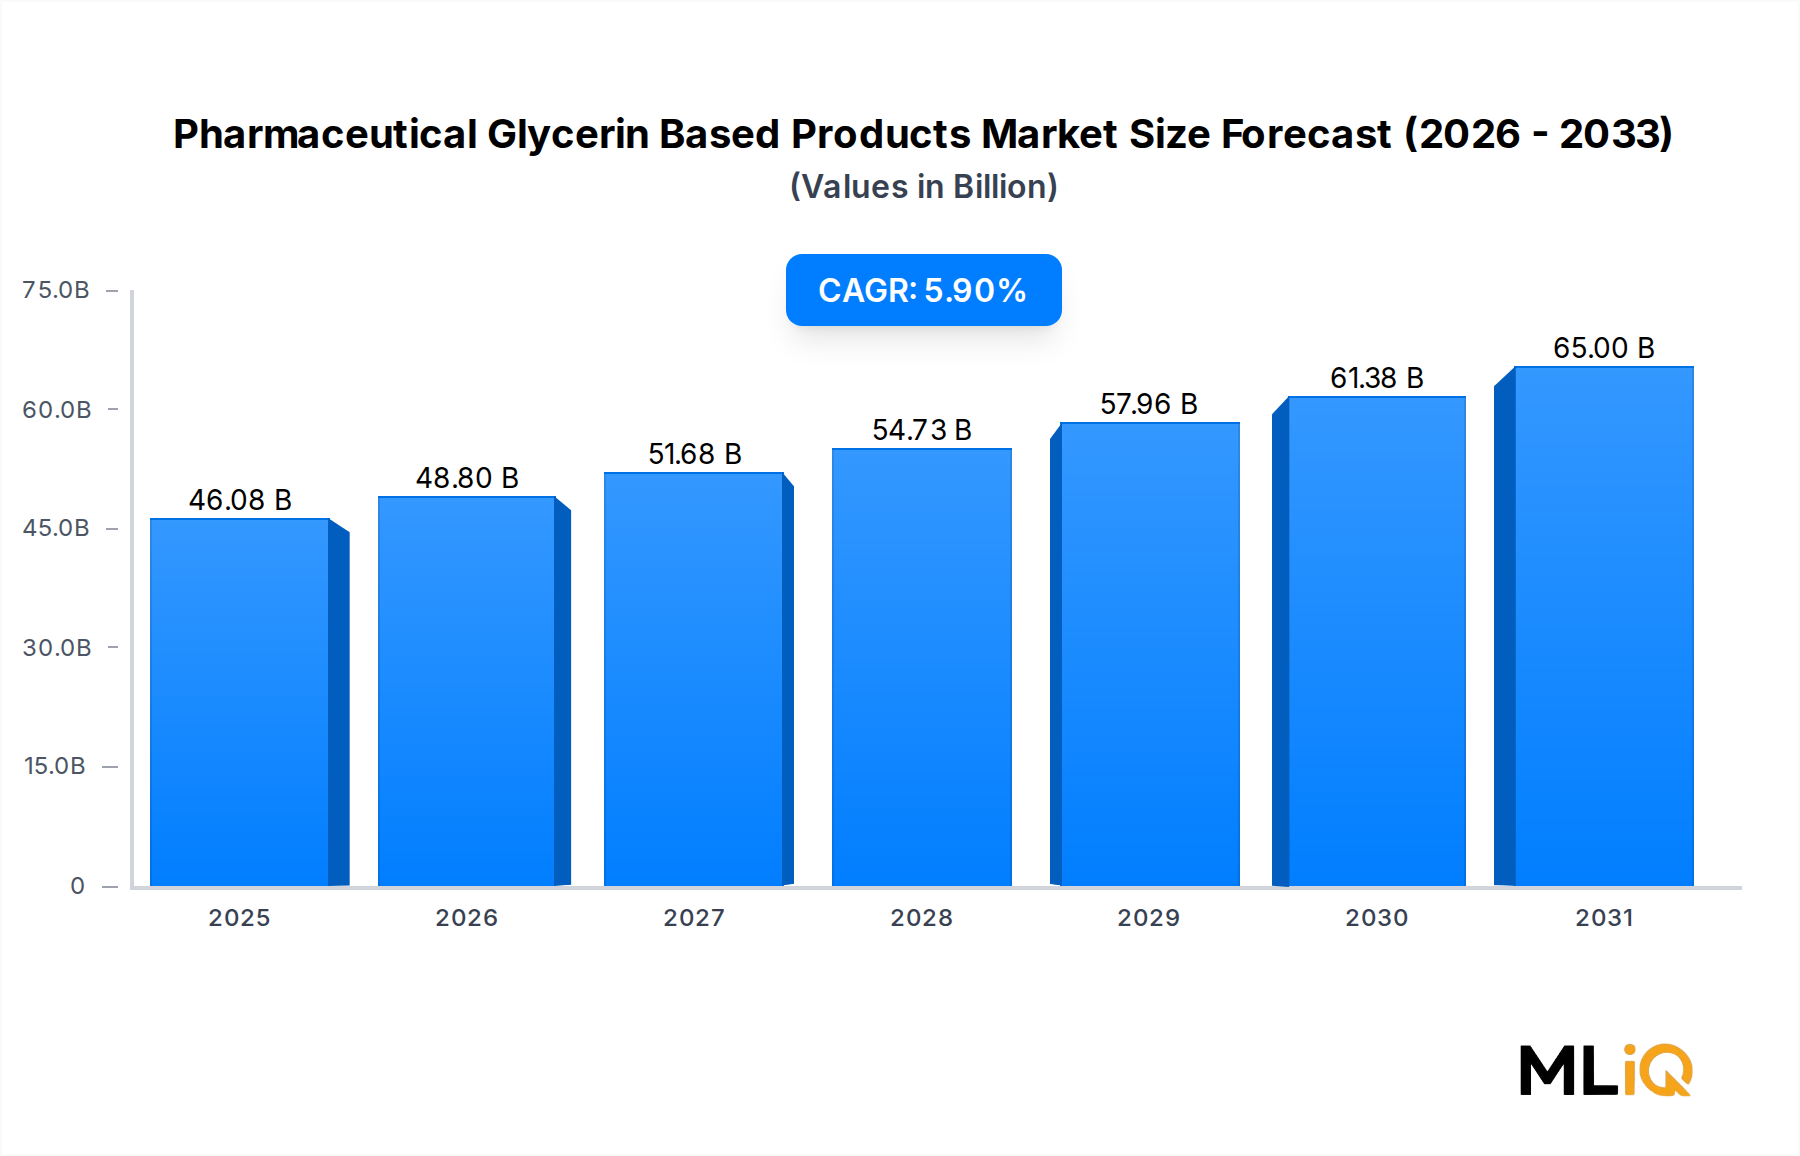
Among all drug type segments within the Pharmaceutical Glycerin Based Products Market — including ophthalmic, cough remedies, glycerine rectal, and angina formulations — the dermatological segment commands the largest revenue share. This dominance is attributable to the convergence of high product volume, broad OTC accessibility, diversified formulation formats, and the growing global prevalence of skin conditions such as eczema, psoriasis, xerosis, and contact dermatitis.
Glycerin's role as both an active moisturizing agent and a functional excipient in dermatological formulations is central to this segment's leadership. In topical creams, lotions, gels, ointments, and serums, pharmaceutical-grade glycerin serves simultaneously as a humectant that draws moisture to the skin surface, a solubilizer for active pharmaceutical ingredients, and a viscosity modifier that improves product spreadability and patient compliance. This multifunctional profile is difficult to replicate with alternative excipients at comparable cost-performance ratios.
The dermatological segment benefits from structural demographic tailwinds. Globally, more than 600 million individuals are estimated to suffer from chronic dermatological conditions requiring continuous or recurrent topical pharmacotherapy. Aging skin exhibits reduced natural moisturization factor (NMF) activity, making glycerin-containing emollients and barrier-repair formulations medically necessary for a growing elderly cohort. In parallel, rising urbanization, pollution exposure, and altered microbiome dynamics in younger populations are expanding the patient addressable market for dermatological glycerin-based products.
From a competitive standpoint, leading pharmaceutical companies active in the dermatological glycerin-based segment include Johnson and Johnson, which maintains a diversified topical product portfolio spanning consumer health and prescription dermatology; AbbVie Inc, with its immunology-linked dermatological pipeline that increasingly incorporates glycerin-based vehicles; Bausch Health Companies Inc., a dedicated dermatology-focused entity with significant exposure to branded topical formulations; and Croda International plc, which plays a pivotal role as a high-performance ingredient supplier enabling premium dermatological formulations for third-party drug manufacturers.
Market share within the dermatological sub-segment is gradually consolidating toward larger players with integrated supply chains and robust regulatory affairs capabilities, as pharmacopeial compliance requirements for glycerin purity (meeting United States Pharmacopeia and European Pharmacopoeia standards) create meaningful barriers to entry for smaller formulators. The segment is also witnessing premiumization, with dermocosmetic and prescription-strength glycerin formulations commanding higher average selling prices than standard OTC moisturizers.
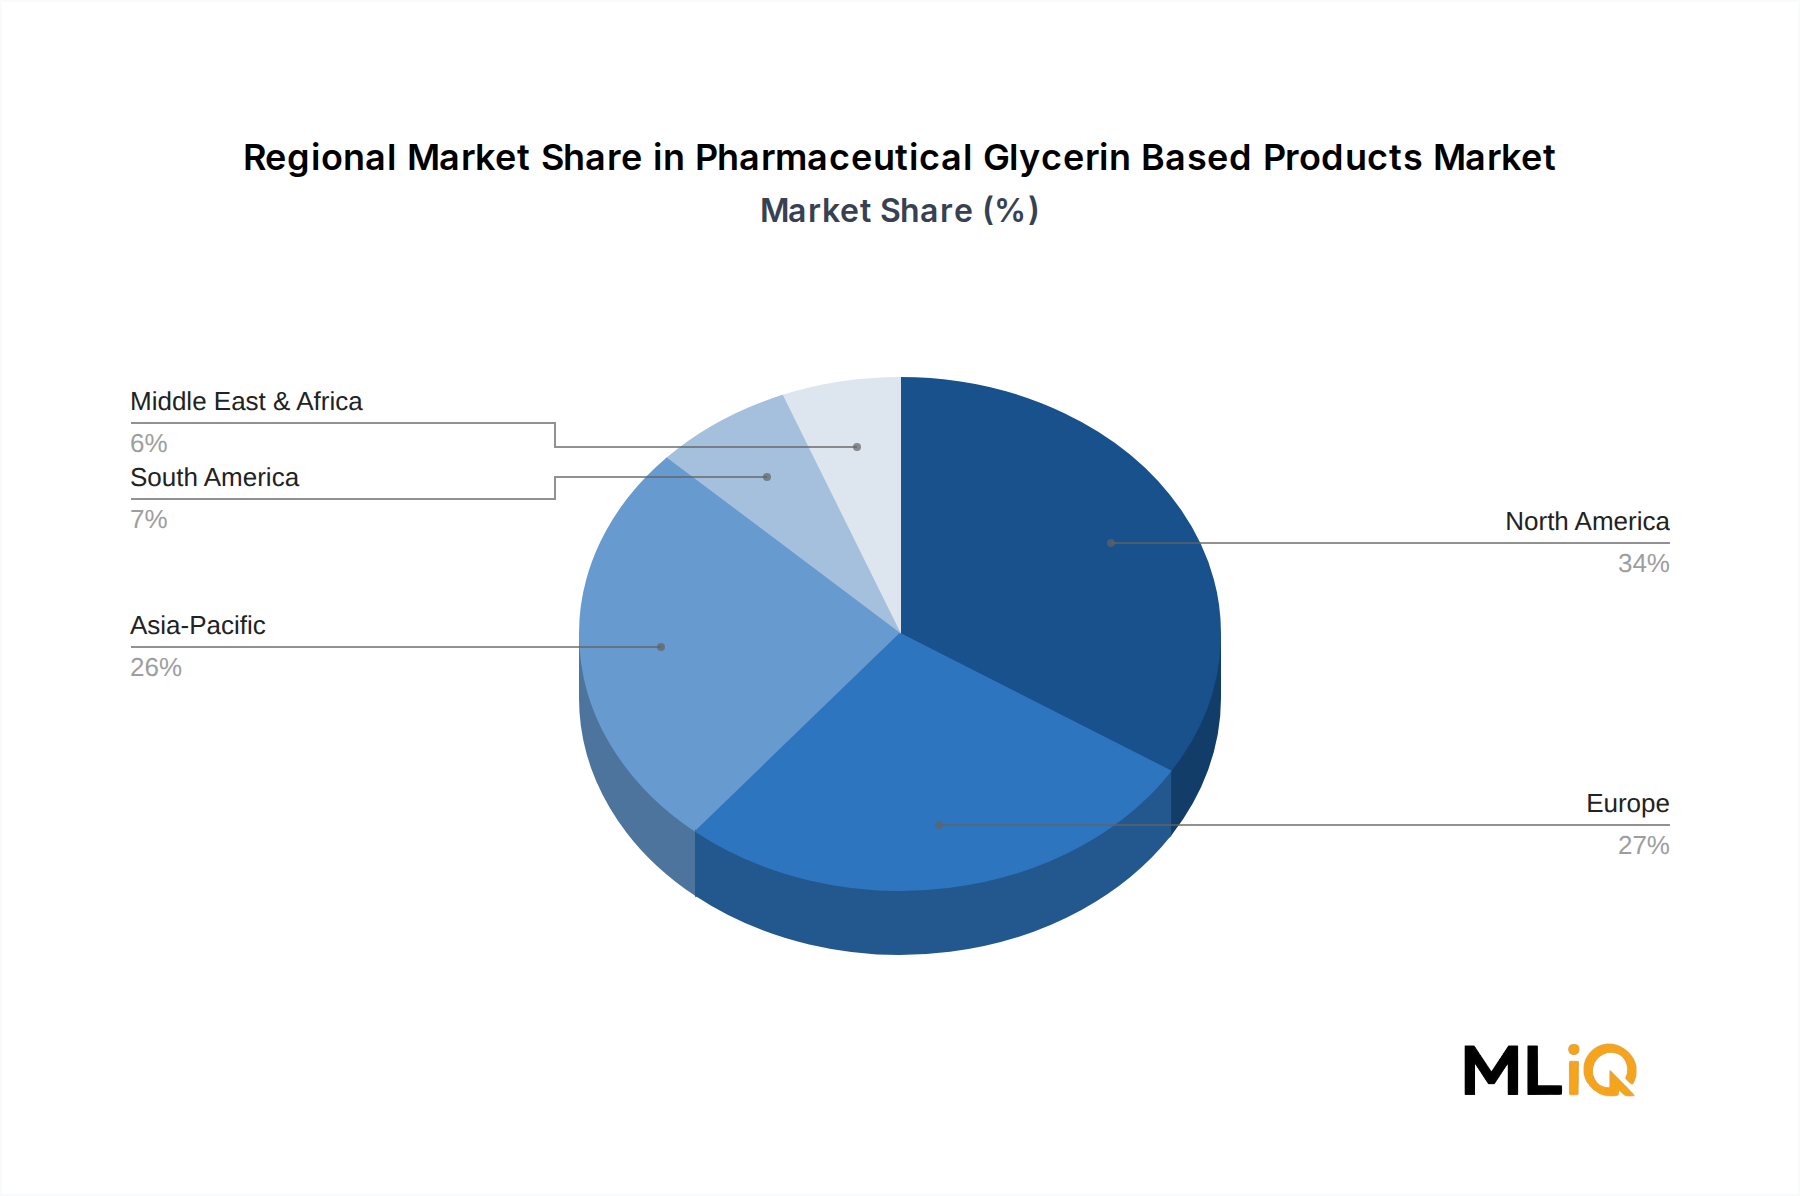
Geographically, North America and Europe collectively represent the dominant revenue pool for dermatological glycerin-based products, reflecting higher per-capita healthcare spending, well-established reimbursement frameworks for prescription dermatologicals, and elevated consumer awareness of skin health. However, Asia Pacific is the fastest-growing sub-region within this segment, driven by expanding middle-class populations in China and India, rising dermatological diagnosis rates, and increasing pharmaceutical retail infrastructure.
The dermatological segment's share is expected to remain above 35% of total market revenue through 2033, with its absolute growth in dollar terms outpacing all other drug type sub-segments owing to the sheer volume of OTC product launches, the expansion of private-label dermatological lines by major pharmacy chains, and continued R&D investment in novel glycerin-based transdermal systems.