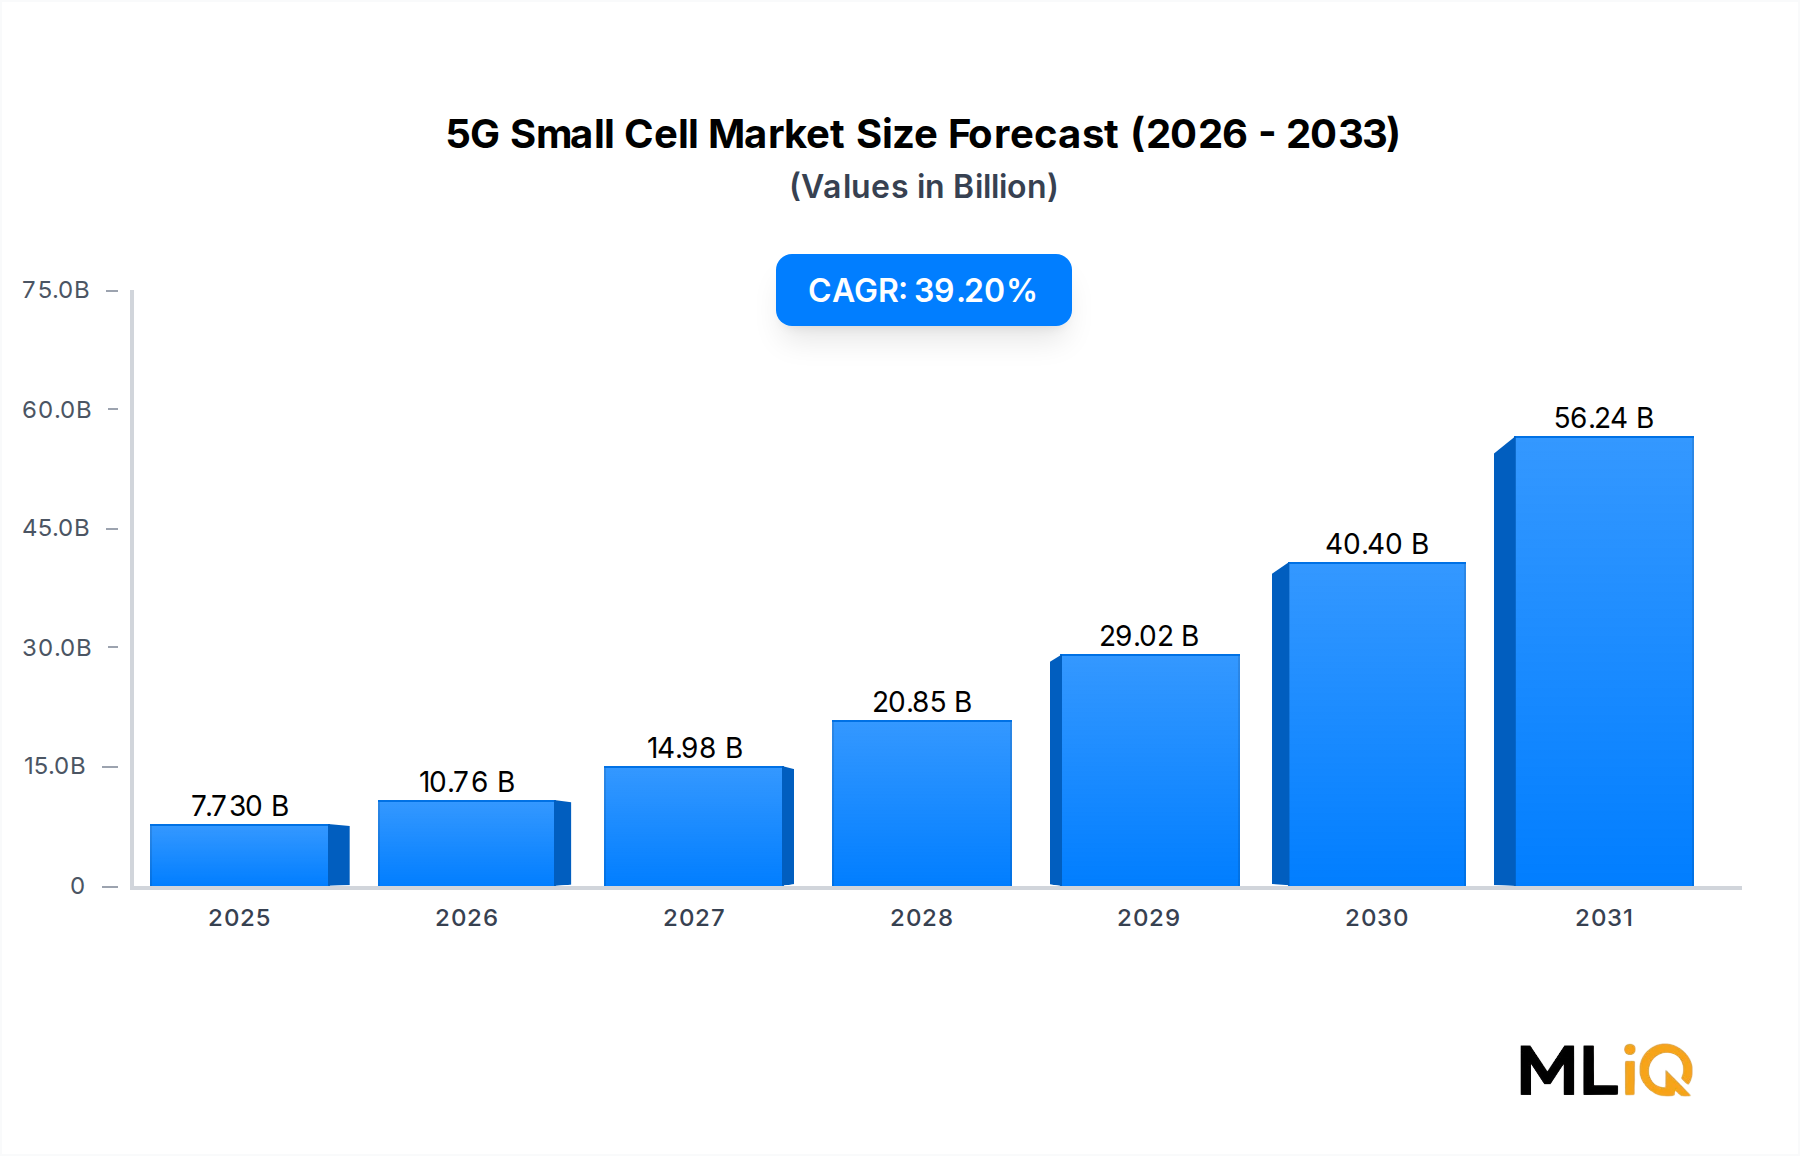
The global 5G Small Cell Market is poised for extraordinary expansion, with its valuation estimated at $7.73 billion in 2025 and projected to surge at a compound annual growth rate (CAGR) of 39.2% through 2033. This explosive trajectory reflects the accelerating global rollout of 5G networks, urbanization of mobile connectivity infrastructure, and the insatiable appetite for high-bandwidth, low-latency communications across enterprise and consumer segments.
Small cells — compact, low-power radio access points including picocells, femtocells, and microcells — are positioned as the architectural backbone of dense urban 5G deployments. Unlike macrocell towers, which cover broad geographic areas with high power, small cells are designed to fill coverage gaps, extend capacity in high-traffic zones, and deliver the millimeter-wave (mmWave) performance that next-generation applications demand. The convergence of smart city development, Industry 4.0 manufacturing automation, connected autonomous vehicles, and immersive augmented reality platforms is amplifying the demand signal for granular network densification.
From a macro-economic standpoint, government spectrum allocation programs, public-private partnerships, and national broadband initiatives across North America, Europe, and Asia Pacific are acting as powerful catalysts. The United States, China, South Korea, and members of the European Union have committed hundreds of billions of dollars to digital infrastructure modernization, with small cell deployments forming a critical component of urban connectivity strategies.
On the technology side, the transition from sub-6 GHz 5G to mmWave 5G is a structural tailwind. MmWave frequencies deliver multi-gigabit throughput but suffer from limited range and penetration, making dense small cell deployment a technical necessity rather than an option. Operators are deploying small cells across indoor venues — stadiums, airports, shopping malls, office complexes — as well as outdoor environments including street furniture, utility poles, and building facades.
The enterprise segment is increasingly adopting private 5G networks built on small cell architectures, enabling industrial automation, real-time asset tracking, and wireless process control in environments previously served by Wi-Fi or wired Ethernet. This enterprise adoption is expanding the total addressable market beyond traditional telecom operators.
Looking forward through 2033, the market will be defined by the maturation of Open RAN (O-RAN) standards, which are democratizing small cell hardware procurement and enabling multi-vendor interoperability. Simultaneously, energy efficiency imperatives are driving next-generation small cell designs toward lower power consumption per transmitted bit, reducing total cost of ownership for operators. The convergence of these trends positions the 5G Small Cell Market as one of the most dynamically growing segments within the broader Semiconductor and Electronics category.