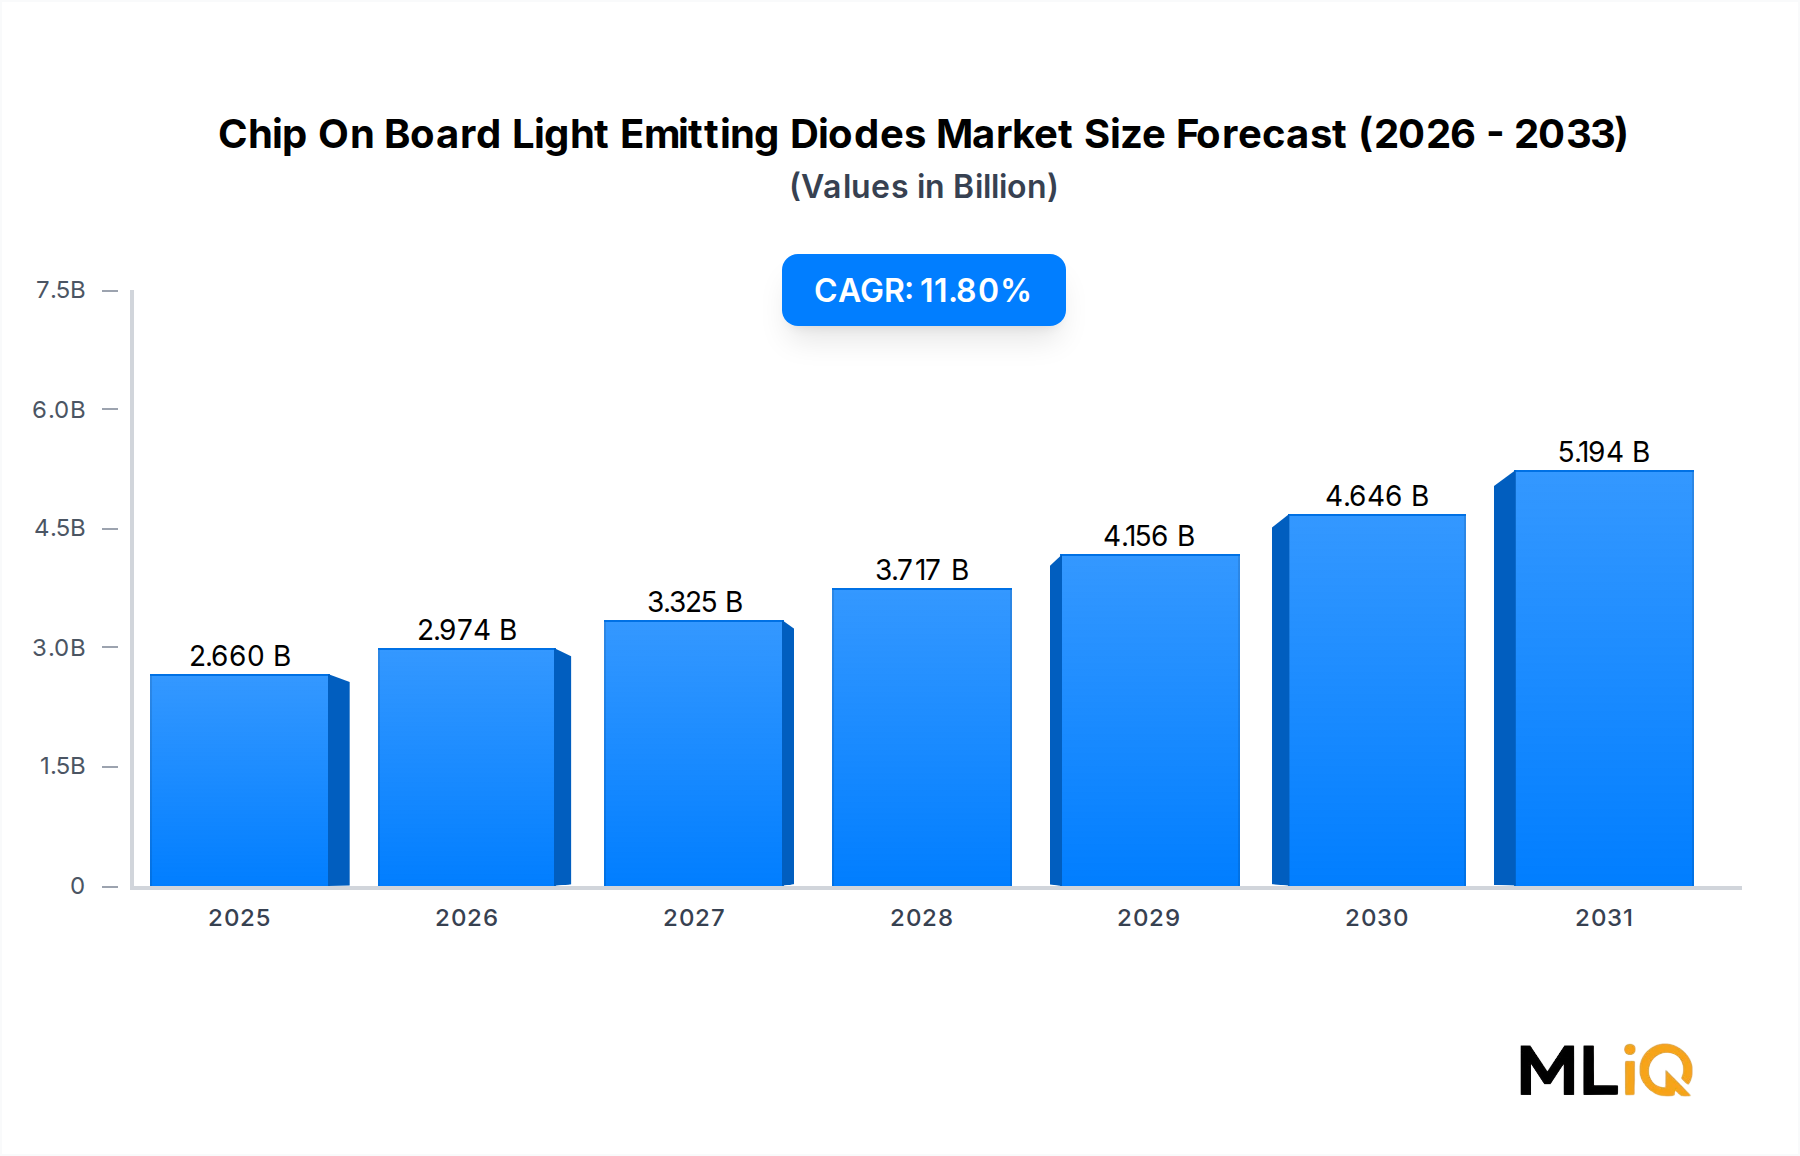
Among the application segments that constitute the Chip On Board Light Emitting Diodes Market, the illumination segment holds the single largest revenue share and continues to consolidate its leadership position. This dominance is attributable to a multi-layered set of structural factors spanning regulatory environments, end-user economics, and the intrinsic technical advantages of COB LED architecture in general lighting applications.
Illumination encompasses a broad range of end-use contexts, including commercial office lighting, industrial high-bay fixtures, retail accent lighting, outdoor area lighting, street lighting, and residential downlights. Across all these sub-categories, COB LEDs have demonstrated a compelling value proposition: their ability to produce high-intensity, omnidirectional light from a point source with minimal glare and excellent color uniformity makes them technically superior to multi-die LED arrays and conventional light sources for most general illumination requirements.
The economics of COB LEDs in illumination applications are particularly attractive. While the upfront module cost has historically been a constraint, aggressive scale economies achieved by leading Asian manufacturers have substantially compressed price-per-lumen metrics over the past several years. Coupled with operating cost savings derived from high efficacy and extended lamp lifetimes — often exceeding 50,000 hours — the total cost of ownership calculation strongly favors COB LED adoption in both new construction and retrofit scenarios.
Regulatory pressure has been a defining accelerant. The United States Department of Energy's energy efficiency standards for general service lamps, the European Union's Ecodesign Regulation framework, and analogous legislation across Japan, South Korea, Australia, and China have collectively eliminated or restricted the sale of incandescent and halogen alternatives, creating a structural demand floor for solid-state lighting technologies. COB LEDs, with their superior efficacy credentials, are direct beneficiaries of this legislative landscape.
Within the illumination segment, the commercial and industrial sub-segments command the highest average selling prices due to the premium placed on high-lumen-output modules, specialized color rendering index specifications, and demanding thermal performance requirements. High-bay industrial fixtures deployed in warehouses, manufacturing facilities, and logistics centers represent a particularly high-volume application category, where COB LEDs delivering upwards of 5,000 lumens from a single module are standard.
Key players competing actively in the illumination-focused segment of the Chip On Board Light Emitting Diodes Market include Cree LED, Inc., Nichia Corporation, OSRAM GmbH, Samsung Electronics Co Ltd, and Seoul Semiconductor Co., Ltd. These companies invest substantially in R&D to push luminous efficacy boundaries, with several having demonstrated laboratory-level efficiencies exceeding 200 lumens per watt under controlled conditions. Product differentiation in this segment is increasingly centered on spectral quality — specifically, high color rendering index values above 90 CRI — and on advanced dimming compatibility with digital lighting control systems.
The illumination segment's share within the overall COB LED market is expected to remain dominant through the forecast period, though the automotive and backlighting segments are growing at relatively faster rates from smaller bases. The segment's maturity in developed markets is offset by strong growth in emerging economies where urbanization is driving new construction activity and infrastructure investment at scale.