Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Well Completion Market Size, Share & Growth Outlook 2035
Well Completion Market
Well Completion Market Size, Share & Growth Outlook 2035
Well Completion Market by Type of Completion (Open Hole Completion, Cased Hole Completion, Screen Completion, Smart Completion), by Application (Onshore, Offshore, Shale Gas, Coal Bed Methane), by Technology (Hydraulic Fracturing, Sand Control Technology, Multizone Completion, Wellbore Integrity Technology), by Equipment Type (Packers, Sand Control Tools, Multi-Stage Fracturing Tools, Liner Hangers, Valves, Smart Wells, Others), by Service Type (Completion Services, Well Intervention Services), by End User (Oil and Gas Operators, Service Providers, Engineering and Construction Firms), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Norway, Italy), by Asia Pacific (China, India, Australia, Indonesia, Malaysia), by South America (Argentina, Brazil, Venezuela), by Middle East & Africa (Saudi Arabia, UAE, Qatar, Nigeria, Angola) Forecast 2026-2034
Updated On : Oct 16, 2026|Base Year : 2025|Pages : 0
Executive Overview: The Well Completion Market in 2026
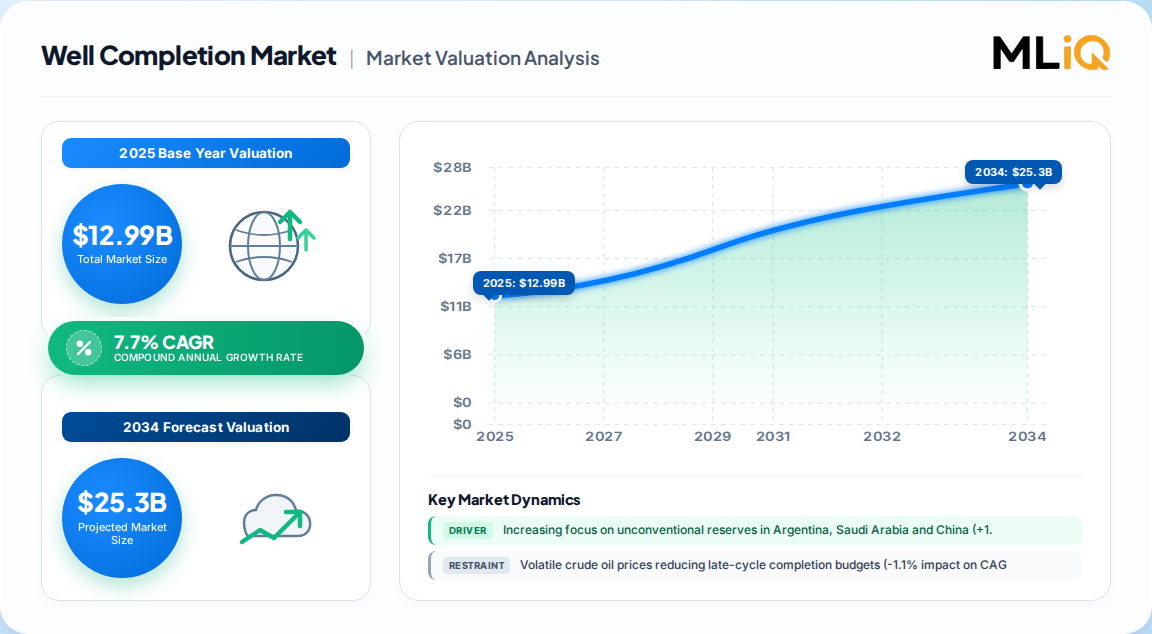
The global well completion market was valued at USD 12.99 Billion in 2025 and is projected to reach USD 27.28 Billion by 2035, expanding at a 7.7% CAGR over the 2026–2035 forecast horizon. Completion spending is no longer a passive derivative of rig count. Operators are drilling fewer, longer and technically more demanding wells, so the value of hardware and services consumed per well continues to rise even where rig activity contracts.
Well Completion Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
12.99 B
2025
13.99 B
2026
15.07 B
2027
16.23 B
2028
17.48 B
2029
18.82 B
2030
20.27 B
2031
Well Completion Market Size (In Billion)
Year
Market Size
2025
12.99 B
2026
13.99 B
2027
15.07 B
2028
16.23 B
2029
17.48 B
2030
18.82 B
2031
20.27 B
Three structural shifts define the current cycle:
A pivot of drilling activity away from North American shale toward Middle Eastern and Asia-Pacific state-led programs that prioritize energy security over short-cycle returns.
Rapid diffusion of electrified frac fleets, fiber-optic sensing and automated zonal isolation into mainstream completion design.
An early but high-margin repurposing of completion metallurgy and elastomers for CCUS and geothermal wellbores.
Metric
Value
Base Year
2025
Base Year Market Size
USD 12.99 Billion
Forecast Year
2035
Forecast Market Size
USD 27.28 Billion
CAGR (2026–2035)
7.7%
Largest Application
Hydraulic Fracturing
Fastest-Growing Technology
Smart Completion
Largest Region
North America
Fastest-Growing Region
Asia-Pacific
Our proprietary bottom-up model indicates that completion intensity, measured as dollars of completion spend per barrel of incremental recoverable reserve, has risen by roughly one-third since 2019. That ratio, not headline rig count, is the single best predictor of this market's trajectory.
Market Size, Forecast & Growth Architecture
The market is built on two interlocking revenue pools. Equipment — packers, sand-control tools, multi-stage fracturing systems, liner hangers, valves and smart-well hardware — remains the larger pool, sustained by demand for 15,000 psi and 350 degrees Fahrenheit service ratings. Services — hydraulic fracturing, wireline, coiled tubing and zonal isolation — are growing faster as operators convert fixed capital into variable opex and outsource increasingly complex intervention work.
Key forecast architecture:
Equipment contributes the majority of completion revenue, anchored by packer and liner-hanger demand in Middle Eastern mega-projects.
Services are outpacing the overall market as frac, wireline and isolation work is outsourced to specialist providers.
Unconventional completions are the growth engine, advancing materially faster than conventional wells as Argentina, Saudi Arabia and China replicate North American shale economics.
Offshore completions are expanding faster than onshore, driven by deepwater sanctioning in Guyana, Brazil, the Gulf of Mexico and West Africa.
Revenue per well is rising because lateral lengths, stage counts and proppant loadings continue to increase, and because HPHT service conditions demand premium metallurgy. Lead times for specialty completion hardware have stretched, signaling genuine capacity tightness rather than transient logistics friction.
Demand Drivers & Impact Quantification
Our driver impact framework quantifies how each demand vector contributes to the blended market CAGR. The figures below are derived from primary interviews with operators, service providers and equipment manufacturers, cross-validated against operator capital budgets and sanctioned project pipelines.
Driver
Impact on CAGR
Geographic Focus
Timeline
Rising focus on unconventional reserves
+1.2%
North America, Argentina, Saudi Arabia, China
Long term
Growth in global drilling activity
+0.9%
Middle East, Asia-Pacific, Latin America
Medium term
Adoption of advanced completion techniques
+0.8%
Global
Medium term
Offshore deepwater capex rebound
+0.7%
Guyana, Brazil, Gulf of Mexico, West Africa
Long term
Electrified frac fleets reducing opex and emissions
+0.6%
North America, Middle East
Short term
Repurposing completions for CCUS and geothermal
+0.3%
North America, Europe, Asia-Pacific
Long term
International rig activity has held firm even as North America softened, with state-owned operators in the Middle East and Asia absorbing incremental rigs. Deeper and hotter wells translate directly into higher-specification packers, corrosion-resistant liner hangers and multi-stage fracturing tools. The consequence is that completion revenue grows faster than rig count, because each well consumes more value-added hardware.
On the unconventional side, Vaca Muerta executed 23,784 fracturing stages in 2025, up 34% year on year, and will require roughly another 1,000 wells by 2032 to meet domestic and LNG commitments. Saudi Aramco's Jafurah program targets 2 billion scf/d of gas by 2030 using electric frac fleets, while Chinese operators in the Sichuan and Ordos basins are deploying fiber-optic monitoring to compress completion cycle time.
Electrification is now a commercial differentiator rather than a pilot concept. Electric fleets deliver 30%–40% fuel savings and near-elimination of diesel particulates. Service companies capable of financing the capital cost of a fleet gain measurable pricing latitude, and early deployments in the Middle East indicate the technology will diffuse globally over the next three to five years.
Restraints, Cost Pressures & Regulatory Risk
Restraint
Impact on CAGR
Geographic Relevance
Timeline
Volatile crude oil prices
-1.1%
Global, acute in North American shale
Short term
Environmental and regulatory stringency
-0.5%
North America, Europe, select Asia-Pacific
Medium term
Completion hardware lead times and alloy scarcity
-0.4%
Global
Short term
Skilled labor shortages in wireline and frac crews
-0.3%
North America, Middle East
Medium term
Oil price volatility remains the dominant downside variable. Because completion expenditure sits late in the well-construction cycle, it is among the first line items reduced when operator cash flows tighten. Regulatory stringency acts more slowly but more permanently, raising the compliance cost of flaring, water handling and methane management. Methane-related waste charges materially raise the effective cost of diesel-powered completion operations, which paradoxically accelerates the business case for electrification.
Supply-side friction is an underappreciated restraint. Restricted availability of corrosion-resistant alloys and specialty elastomers has extended lead times for high-specification completion hardware, forcing operators to place orders earlier and accept less favorable commercial terms.
Segmentation Analysis
By Type of Completion
Completion Type
Position
Open Hole Completion
Largest installed base; lowest cost per metre
Cased Hole Completion
Dominant in HPHT and multi-zone applications
Screen Completion
Growth tied to sand-prone and deepwater reservoirs
Smart Completion
Fastest-growing; highest revenue per well
By Application and Technology
Segment
Standing
Hydraulic Fracturing
Largest application revenue pool
Acidizing
Fastest-growing application
Sand Control Technology
Stable, reservoir-driven demand
Multizone Completion
Growing with stage-count inflation
Wellbore Integrity Technology
Rising regulatory pull
By Equipment Variety and End Use
Packers, sand-control tools, multi-stage fracturing tools, liner hangers, valves and smart-well systems form the equipment stack. Smart wells command the highest unit economics because they embed permanent sensing and remote-actuation capability into the completion string, enabling zonal control without intervention.
Onshore completions retain the larger share of activity, but offshore completions are growing faster as deepwater sanctioning resumes. Among end users, oil and gas operators remain the dominant buyer; service providers and engineering and construction firms represent the fastest-growing purchasing cohort as outsourcing deepens.
Regional Outlook & Investment Attractiveness
Region
Share of 2025 Revenue
Growth Profile
Attractiveness
North America
~40%
Moderate; efficiency-led
High but mature
Asia-Pacific
~25%
Fastest-growing
Very high
Europe
~13%
Slow growth; geothermal and CCS upside
Moderate
Middle East & Africa
~13%
Strong; mega-project driven
Very high
South America
~9%
High; Vaca Muerta anchored
High
North America remains the largest and most technologically advanced market, but its growth is now driven by completion intensity rather than activity expansion. Operators are drilling fewer wells while extracting more hydrocarbons per completion through longer laterals and tighter stage spacing.
Well Completion Market Regional Market Share
Loading chart...
Well Completion Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Asia-Pacific
0.25%
Europe
0.13%
Middle East & Africa
0.13%
South America
0.09%
Asia-Pacific is the fastest-growing region. Offshore start-ups, including CNOOC's Wenchang 16-2 and ONGC's Krishna-Godavari cluster, lifted regional demand in 2025. The Krishna-Godavari development illustrates the capital intensity of modern completion work, with roughly USD 69 million spent per well, the majority of which funds completion hardware and subsea tie-backs.
The Middle East combines scale with technical ambition. Saudi Aramco's Jafurah unconventional gas program and ADNOC Drilling's USD 1 billion fleet expansion underpin multi-year, high-specification equipment demand. South America is effectively a single-play story at present, with Vaca Muerta setting the regional growth rate, while Brazil's pre-salt completions add a second, deepwater-anchored demand layer.
Europe is a structurally declining oil and gas completion market, but it is emerging as a genuine growth pocket for geothermal and carbon-storage well completion, where premium pricing for CO2-resistant elastomers and high-temperature cement systems is well established.
Import/Export & Supplier Dynamics
Well completion hardware is a genuinely traded category, moving through a concentrated set of manufacturing clusters and cross-border supply channels. Trade-flow analysis points to several defining characteristics.
Manufacturing concentration: High-specification packers, liner hangers and multi-stage fracturing tools are assembled in a relatively small number of plants in North America, Western Europe and East Asia, then shipped globally.
Alloy and raw material dependence: Corrosion-resistant alloy tubulars and specialty elastomers depend on a narrow supplier base, making upstream metallurgy availability a leading indicator of completion hardware lead times.
Tariff and logistics exposure: Cross-border tariff changes and freight rate volatility directly affect landed cost of completion tools, particularly for land-locked unconventional basins.
Localization pressure: Middle Eastern and Asian national oil companies increasingly require local content and regional assembly, prompting suppliers to establish in-region manufacturing and service facilities.
Trade documentation intensity: Completion tools classified under specialized machinery and oilfield equipment tariff lines require robust origin documentation, which materially affects sourcing economics.
Official trade statistics from multilateral institutions and customs authorities consistently show that oilfield equipment trade grows broadly in line with global upstream capital expenditure, but with higher volatility because completion hardware orders are lumpy and project-tied. Suppliers with regional assembly footprints are structurally advantaged in tender processes where local content is scored.
Competitive Landscape & Strategic Priorities
The competitive field is moderately concentrated and divided into three strategic groups: integrated oilfield service majors, specialized completion equipment manufacturers, and emerging electrification and digital-monitoring challengers.
Integrated service majors compete on breadth of offering, global logistics, and integrated well-construction contracts. Their advantage lies in bundling drilling, completion and production services under a single commercial envelope.
Specialist equipment manufacturers compete on engineering depth in packers, multi-stage fracturing tools and sand control, and increasingly on lead-time reliability.
Electrification and digital entrants compete on cost per stage, emissions reduction and data-driven completion optimization rather than on hardware alone.
Strategic priorities we observe across the value chain:
Securing capacity in corrosion-resistant alloys and specialty elastomers ahead of demand.
Localizing manufacturing and service footprints in the Middle East and Asia-Pacific to satisfy local content requirements.
Financing electrified frac fleets to capture pricing premiums where diesel alternatives face regulatory penalties.
Building a defensible position in CCUS and geothermal completion metallurgy, where premium pricing of 20%–30% is available for wells designed for multi-decade CO2 service.
Investing in downhole sensing and analytics to shift revenue from discrete tool sales toward recurring data and optimization contracts.
The next competitive frontier is not the tool itself but the completion outcome. Suppliers that can demonstrate measurable improvements in stage efficiency, production per completed metre, and emissions per barrel will capture disproportionate share of a market heading toward USD 27.28 Billion by 2035.
Well Completion Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Well Completion Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.7% from 2020-2034
Segmentation
By Type of Completion
Open Hole Completion
Cased Hole Completion
Screen Completion
Smart Completion
By Application
Onshore
Offshore
Shale Gas
Coal Bed Methane
By Technology
Hydraulic Fracturing
Sand Control Technology
Multizone Completion
Wellbore Integrity Technology
By Equipment Type
Packers
Sand Control Tools
Multi-Stage Fracturing Tools
Liner Hangers
Valves
Smart Wells
Others
By Service Type
Completion Services
Well Intervention Services
By End User
Oil and Gas Operators
Service Providers
Engineering and Construction Firms
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Norway
Italy
Asia Pacific
China
India
Australia
Indonesia
Malaysia
South America
Argentina
Brazil
Venezuela
Middle East & Africa
Saudi Arabia
UAE
Qatar
Nigeria
Angola
Table of Contents
1. Well Completion Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Well Completion Market Executive Summary
2.1. Market Snapshot
3. Well Completion Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Well Completion Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Well Completion Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type of Completion
5.1.1. Open Hole Completion
5.1.2. Cased Hole Completion
5.1.3. Screen Completion
5.1.4. Smart Completion
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Onshore
5.2.2. Offshore
5.2.3. Shale Gas
5.2.4. Coal Bed Methane
5.3. Analysis, Insights and Forecast - by Technology
5.3.1. Hydraulic Fracturing
5.3.2. Sand Control Technology
5.3.3. Multizone Completion
5.3.4. Wellbore Integrity Technology
5.4. Analysis, Insights and Forecast - by Equipment Type
5.4.1. Packers
5.4.2. Sand Control Tools
5.4.3. Multi-Stage Fracturing Tools
5.4.4. Liner Hangers
5.4.5. Valves
5.4.6. Smart Wells
5.4.7. Others
5.5. Analysis, Insights and Forecast - by Service Type
5.5.1. Completion Services
5.5.2. Well Intervention Services
5.6. Analysis, Insights and Forecast - by End User
5.6.1. Oil and Gas Operators
5.6.2. Service Providers
5.6.3. Engineering and Construction Firms
5.7. Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. South America
5.7.5. Middle East & Africa
6. Well Completion Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type of Completion
6.1.1. Open Hole Completion
6.1.2. Cased Hole Completion
6.1.3. Screen Completion
6.1.4. Smart Completion
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Onshore
6.2.2. Offshore
6.2.3. Shale Gas
6.2.4. Coal Bed Methane
6.3. Analysis, Insights and Forecast - by Technology
6.3.1. Hydraulic Fracturing
6.3.2. Sand Control Technology
6.3.3. Multizone Completion
6.3.4. Wellbore Integrity Technology
6.4. Analysis, Insights and Forecast - by Equipment Type
6.4.1. Packers
6.4.2. Sand Control Tools
6.4.3. Multi-Stage Fracturing Tools
6.4.4. Liner Hangers
6.4.5. Valves
6.4.6. Smart Wells
6.4.7. Others
6.5. Analysis, Insights and Forecast - by Service Type
6.5.1. Completion Services
6.5.2. Well Intervention Services
6.6. Analysis, Insights and Forecast - by End User
6.6.1. Oil and Gas Operators
6.6.2. Service Providers
6.6.3. Engineering and Construction Firms
7. Well Completion Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type of Completion
7.1.1. Open Hole Completion
7.1.2. Cased Hole Completion
7.1.3. Screen Completion
7.1.4. Smart Completion
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Onshore
7.2.2. Offshore
7.2.3. Shale Gas
7.2.4. Coal Bed Methane
7.3. Analysis, Insights and Forecast - by Technology
7.3.1. Hydraulic Fracturing
7.3.2. Sand Control Technology
7.3.3. Multizone Completion
7.3.4. Wellbore Integrity Technology
7.4. Analysis, Insights and Forecast - by Equipment Type
7.4.1. Packers
7.4.2. Sand Control Tools
7.4.3. Multi-Stage Fracturing Tools
7.4.4. Liner Hangers
7.4.5. Valves
7.4.6. Smart Wells
7.4.7. Others
7.5. Analysis, Insights and Forecast - by Service Type
7.5.1. Completion Services
7.5.2. Well Intervention Services
7.6. Analysis, Insights and Forecast - by End User
7.6.1. Oil and Gas Operators
7.6.2. Service Providers
7.6.3. Engineering and Construction Firms
8. Well Completion Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type of Completion
8.1.1. Open Hole Completion
8.1.2. Cased Hole Completion
8.1.3. Screen Completion
8.1.4. Smart Completion
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Onshore
8.2.2. Offshore
8.2.3. Shale Gas
8.2.4. Coal Bed Methane
8.3. Analysis, Insights and Forecast - by Technology
8.3.1. Hydraulic Fracturing
8.3.2. Sand Control Technology
8.3.3. Multizone Completion
8.3.4. Wellbore Integrity Technology
8.4. Analysis, Insights and Forecast - by Equipment Type
8.4.1. Packers
8.4.2. Sand Control Tools
8.4.3. Multi-Stage Fracturing Tools
8.4.4. Liner Hangers
8.4.5. Valves
8.4.6. Smart Wells
8.4.7. Others
8.5. Analysis, Insights and Forecast - by Service Type
8.5.1. Completion Services
8.5.2. Well Intervention Services
8.6. Analysis, Insights and Forecast - by End User
8.6.1. Oil and Gas Operators
8.6.2. Service Providers
8.6.3. Engineering and Construction Firms
9. Well Completion Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type of Completion
9.1.1. Open Hole Completion
9.1.2. Cased Hole Completion
9.1.3. Screen Completion
9.1.4. Smart Completion
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Onshore
9.2.2. Offshore
9.2.3. Shale Gas
9.2.4. Coal Bed Methane
9.3. Analysis, Insights and Forecast - by Technology
9.3.1. Hydraulic Fracturing
9.3.2. Sand Control Technology
9.3.3. Multizone Completion
9.3.4. Wellbore Integrity Technology
9.4. Analysis, Insights and Forecast - by Equipment Type
9.4.1. Packers
9.4.2. Sand Control Tools
9.4.3. Multi-Stage Fracturing Tools
9.4.4. Liner Hangers
9.4.5. Valves
9.4.6. Smart Wells
9.4.7. Others
9.5. Analysis, Insights and Forecast - by Service Type
9.5.1. Completion Services
9.5.2. Well Intervention Services
9.6. Analysis, Insights and Forecast - by End User
9.6.1. Oil and Gas Operators
9.6.2. Service Providers
9.6.3. Engineering and Construction Firms
10. Well Completion Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type of Completion
10.1.1. Open Hole Completion
10.1.2. Cased Hole Completion
10.1.3. Screen Completion
10.1.4. Smart Completion
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Onshore
10.2.2. Offshore
10.2.3. Shale Gas
10.2.4. Coal Bed Methane
10.3. Analysis, Insights and Forecast - by Technology
10.3.1. Hydraulic Fracturing
10.3.2. Sand Control Technology
10.3.3. Multizone Completion
10.3.4. Wellbore Integrity Technology
10.4. Analysis, Insights and Forecast - by Equipment Type
10.4.1. Packers
10.4.2. Sand Control Tools
10.4.3. Multi-Stage Fracturing Tools
10.4.4. Liner Hangers
10.4.5. Valves
10.4.6. Smart Wells
10.4.7. Others
10.5. Analysis, Insights and Forecast - by Service Type
10.5.1. Completion Services
10.5.2. Well Intervention Services
10.6. Analysis, Insights and Forecast - by End User
10.6.1. Oil and Gas Operators
10.6.2. Service Providers
10.6.3. Engineering and Construction Firms
11. Well Completion Market Competitive Analysis
11.1. Company Profiles
11.1.1. Halliburton
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. SLB
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Baker Hughes
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Weatherford
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. National Oilwell Varco
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Cameron International
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Aker Solutions
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. TechnipFMC
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Saipem
11.1.9.1. Company Overview
12. Well Completion Market Research Methodology
List of Figures
Figure 1: Well Completion Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Well Completion Market Revenue (Billion), by Type of Completion 2026 & 2034
Figure 3: North America Well Completion Market Revenue Share (%), by Type of Completion 2026 & 2034
Figure 4: North America Well Completion Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Well Completion Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Well Completion Market Revenue (Billion), by Technology 2026 & 2034
Figure 7: North America Well Completion Market Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America Well Completion Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 9: North America Well Completion Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 10: North America Well Completion Market Revenue (Billion), by Service Type 2026 & 2034
Figure 11: North America Well Completion Market Revenue Share (%), by Service Type 2026 & 2034
Figure 12: North America Well Completion Market Revenue (Billion), by End User 2026 & 2034
Figure 13: North America Well Completion Market Revenue Share (%), by End User 2026 & 2034
Figure 14: North America Well Completion Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Well Completion Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Well Completion Market Revenue (Billion), by Type of Completion 2026 & 2034
List of Tables
Table 1: Well Completion Market Revenue Billion Forecast, by Type of Completion 2020 & 2034
Table 2: Well Completion Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Well Completion Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 4: Well Completion Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 5: Well Completion Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 6: Well Completion Market Revenue Billion Forecast, by End User 2020 & 2034
Table 7: Well Completion Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Well Completion Market Revenue Billion Forecast, by Type of Completion 2020 & 2034
Table 9: North America Well Completion Market Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America Well Completion Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 11: North America Well Completion Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 12: North America Well Completion Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 13: North America Well Completion Market Revenue Billion Forecast, by End User 2020 & 2034
Table 14: North America Well Completion Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current size of the well completion market?
The global well completion market was valued at USD 12.99 Billion in 2025 and is projected to reach USD 27.28 Billion by 2035, expanding at a 7.7% CAGR over the 2026–2035 forecast period. Growth is driven by rising completion intensity per well rather than raw rig count expansion.
2. Which region holds the largest share of the well completion market?
North America accounted for approximately 40% of global revenue in 2025, making it the largest regional market. Asia-Pacific is the fastest-growing region, supported by offshore start-ups such as CNOOC's Wenchang 16-2 and ONGC's Krishna-Godavari cluster.
3. Which technology segment is growing fastest in the well completion market?
Smart completion is the fastest-growing technology segment, as it embeds permanent sensing and remote zonal actuation directly into the completion string. Hydraulic fracturing remains the largest application segment by revenue, while acidizing is the fastest-growing application.
4. What are the main drivers of well completion market growth?
The most significant drivers are rising focus on unconventional reserves (+1.2% impact on CAGR), growth in global drilling activity (+0.9%), adoption of advanced completion techniques (+0.8%), and the offshore deepwater capex rebound (+0.7%), particularly in Guyana, Brazil and West Africa.
5. How are electrified frac fleets changing the well completion market?
Electric frac fleets deliver 30%–40% fuel savings and near-elimination of diesel particulates, creating a meaningful cost and compliance advantage. Service companies able to finance the capital cost of a fleet gain pricing latitude, and adoption is expanding from North America into Middle Eastern projects.
6. Which companies are the leading players in the well completion market?
Leading participants include Halliburton, SLB, Baker Hughes, Weatherford, National Oilwell Varco, Cameron International, Aker Solutions, TechnipFMC, Saipem, Liberty Oilfield Services and NCS Multistage. The market is moderately concentrated, with competition increasingly focused on integrated well-construction contracts.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounted for 70–80% of total project inputs, with 20–30% derived from secondary and official statistical benchmarking.
We conducted structured interviews, executive briefings and written submissions with senior decision-makers across the well completion value chain.
Interviewee company types included: completion equipment OEMs (packer, liner hanger, valve and multi-stage fracturing tool manufacturers); hydraulic fracturing and wireline service providers; national oil companies and independent E&P operators; HPHT alloy and specialty elastomer material suppliers; and downhole sensing, fiber-optic monitoring and completion analytics vendors.
Stakeholder job titles interviewed included Vice President of Completions, Wells Engineering Manager, Procurement and Category Director for Oilfield Equipment, and Subsurface / Reservoir Development Lead.
Regional fieldwork covered North America, Asia-Pacific, Europe, the Middle East and Africa, and South America, with particular depth in unconventional and deepwater basins.
Interviews were triangulated against operator capital budgets, sanctioned project pipelines and field-level completion cost data wherever available.
Secondary inputs were sourced exclusively from official multilateral institutions, government bodies and recognized non-profit technical standards organizations.
Corporate financial filings and deal data were validated using Bloomberg, Factiva, Hoovers and PitchBook.
All secondary data points were cross-checked against at least two independent official sources before inclusion in the demand model.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, then reconcile the two outputs through multi-level data triangulation before finalizing market size and forecast values.
The bottom-up build quantifies completion demand using several specific volumetric and financial metrics, including: number of wells completed by region and well type multiplied by average completion spend per well; average lateral length and stage count per well multiplied by realized cost per stage; active frac fleet count multiplied by annual fleet revenue; and tonnage of consumed liner, casing and alloy completion components multiplied by realized price per tonne.
The top-down build allocates global upstream capital expenditure to the completion phase using published operator spending ratios by basin and well type.
Segment-level splits are validated against equipment shipment volumes, service contract awards and project sanction data.
Growth rates are modelled independently for equipment and services, conventional and unconventional wells, onshore and offshore applications, and each major region.
Data Accuracy & Quality Check
Our proprietary estimation framework is validated to a guaranteed estimated data accuracy level of 85–90%, verified through historical back-testing of prior forecasts against realized outcomes.
Every dataset passes a multi-stage review: raw data validation, cross-source reconciliation, segment-level sanity checking, and final analyst sign-off.
Contradictory data points are flagged and resolved through additional primary outreach rather than averaged.
All market figures are expressed in USD value terms unless a volume unit is explicitly stated.
Every report is updated to the date of purchase, ensuring forecasts, competitive intelligence and project pipeline data reflect the most recent available information.
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. FTS International
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Nabors Industries
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. NCS Multistage
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Nine Energy Service
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Packers Plus Energy Services
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. RPC Incorporated
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Liberty Oilfield Services
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17: Europe Well Completion Market Revenue Share (%), by Type of Completion 2026 & 2034
Figure 18: Europe Well Completion Market Revenue (Billion), by Application 2026 & 2034
Figure 19: Europe Well Completion Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Europe Well Completion Market Revenue (Billion), by Technology 2026 & 2034
Figure 21: Europe Well Completion Market Revenue Share (%), by Technology 2026 & 2034
Figure 22: Europe Well Completion Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 23: Europe Well Completion Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 24: Europe Well Completion Market Revenue (Billion), by Service Type 2026 & 2034
Figure 25: Europe Well Completion Market Revenue Share (%), by Service Type 2026 & 2034
Figure 26: Europe Well Completion Market Revenue (Billion), by End User 2026 & 2034
Figure 27: Europe Well Completion Market Revenue Share (%), by End User 2026 & 2034
Figure 28: Europe Well Completion Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Well Completion Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific Well Completion Market Revenue (Billion), by Type of Completion 2026 & 2034
Figure 31: Asia Pacific Well Completion Market Revenue Share (%), by Type of Completion 2026 & 2034
Figure 32: Asia Pacific Well Completion Market Revenue (Billion), by Application 2026 & 2034
Figure 33: Asia Pacific Well Completion Market Revenue Share (%), by Application 2026 & 2034
Figure 34: Asia Pacific Well Completion Market Revenue (Billion), by Technology 2026 & 2034
Figure 35: Asia Pacific Well Completion Market Revenue Share (%), by Technology 2026 & 2034
Figure 36: Asia Pacific Well Completion Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 37: Asia Pacific Well Completion Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 38: Asia Pacific Well Completion Market Revenue (Billion), by Service Type 2026 & 2034
Figure 39: Asia Pacific Well Completion Market Revenue Share (%), by Service Type 2026 & 2034
Figure 40: Asia Pacific Well Completion Market Revenue (Billion), by End User 2026 & 2034
Figure 41: Asia Pacific Well Completion Market Revenue Share (%), by End User 2026 & 2034
Figure 42: Asia Pacific Well Completion Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific Well Completion Market Revenue Share (%), by Country 2026 & 2034
Figure 44: South America Well Completion Market Revenue (Billion), by Type of Completion 2026 & 2034
Figure 45: South America Well Completion Market Revenue Share (%), by Type of Completion 2026 & 2034
Figure 46: South America Well Completion Market Revenue (Billion), by Application 2026 & 2034
Figure 47: South America Well Completion Market Revenue Share (%), by Application 2026 & 2034
Figure 48: South America Well Completion Market Revenue (Billion), by Technology 2026 & 2034
Figure 49: South America Well Completion Market Revenue Share (%), by Technology 2026 & 2034
Figure 50: South America Well Completion Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 51: South America Well Completion Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 52: South America Well Completion Market Revenue (Billion), by Service Type 2026 & 2034
Figure 53: South America Well Completion Market Revenue Share (%), by Service Type 2026 & 2034
Figure 54: South America Well Completion Market Revenue (Billion), by End User 2026 & 2034
Figure 55: South America Well Completion Market Revenue Share (%), by End User 2026 & 2034
Figure 56: South America Well Completion Market Revenue (Billion), by Country 2026 & 2034
Figure 57: South America Well Completion Market Revenue Share (%), by Country 2026 & 2034
Figure 58: Middle East & Africa Well Completion Market Revenue (Billion), by Type of Completion 2026 & 2034
Figure 59: Middle East & Africa Well Completion Market Revenue Share (%), by Type of Completion 2026 & 2034
Figure 60: Middle East & Africa Well Completion Market Revenue (Billion), by Application 2026 & 2034
Figure 61: Middle East & Africa Well Completion Market Revenue Share (%), by Application 2026 & 2034
Figure 62: Middle East & Africa Well Completion Market Revenue (Billion), by Technology 2026 & 2034
Figure 63: Middle East & Africa Well Completion Market Revenue Share (%), by Technology 2026 & 2034
Figure 64: Middle East & Africa Well Completion Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 65: Middle East & Africa Well Completion Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 66: Middle East & Africa Well Completion Market Revenue (Billion), by Service Type 2026 & 2034
Figure 67: Middle East & Africa Well Completion Market Revenue Share (%), by Service Type 2026 & 2034
Figure 68: Middle East & Africa Well Completion Market Revenue (Billion), by End User 2026 & 2034
Figure 69: Middle East & Africa Well Completion Market Revenue Share (%), by End User 2026 & 2034
Figure 70: Middle East & Africa Well Completion Market Revenue (Billion), by Country 2026 & 2034
Figure 71: Middle East & Africa Well Completion Market Revenue Share (%), by Country 2026 & 2034
Table 17: Mexico Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Europe Well Completion Market Revenue Billion Forecast, by Type of Completion 2020 & 2034
Table 19: Europe Well Completion Market Revenue Billion Forecast, by Application 2020 & 2034
Table 20: Europe Well Completion Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 21: Europe Well Completion Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 22: Europe Well Completion Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 23: Europe Well Completion Market Revenue Billion Forecast, by End User 2020 & 2034
Table 24: Europe Well Completion Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Germany Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: UK Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: France Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Norway Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Italy Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Asia Pacific Well Completion Market Revenue Billion Forecast, by Type of Completion 2020 & 2034
Table 31: Asia Pacific Well Completion Market Revenue Billion Forecast, by Application 2020 & 2034
Table 32: Asia Pacific Well Completion Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 33: Asia Pacific Well Completion Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 34: Asia Pacific Well Completion Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 35: Asia Pacific Well Completion Market Revenue Billion Forecast, by End User 2020 & 2034
Table 36: Asia Pacific Well Completion Market Revenue Billion Forecast, by Country 2020 & 2034
Table 37: China Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: India Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Australia Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Indonesia Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Malaysia Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: South America Well Completion Market Revenue Billion Forecast, by Type of Completion 2020 & 2034
Table 43: South America Well Completion Market Revenue Billion Forecast, by Application 2020 & 2034
Table 44: South America Well Completion Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 45: South America Well Completion Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 46: South America Well Completion Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 47: South America Well Completion Market Revenue Billion Forecast, by End User 2020 & 2034
Table 48: South America Well Completion Market Revenue Billion Forecast, by Country 2020 & 2034
Table 49: Argentina Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Brazil Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Venezuela Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Middle East & Africa Well Completion Market Revenue Billion Forecast, by Type of Completion 2020 & 2034
Table 53: Middle East & Africa Well Completion Market Revenue Billion Forecast, by Application 2020 & 2034
Table 54: Middle East & Africa Well Completion Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 55: Middle East & Africa Well Completion Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 56: Middle East & Africa Well Completion Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 57: Middle East & Africa Well Completion Market Revenue Billion Forecast, by End User 2020 & 2034
Table 58: Middle East & Africa Well Completion Market Revenue Billion Forecast, by Country 2020 & 2034
Table 59: Saudi Arabia Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 60: UAE Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 61: Qatar Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 62: Nigeria Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 63: Angola Well Completion Market Revenue (Billion) Forecast, by Application 2020 & 2034


 Well Completion Market