 Alkaline Battery Market
 Size, Share & Growth Forecast 2026-2031
Updated On : Oct 19, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Alkaline Battery Market

Sandeep Singh
Research Analyst

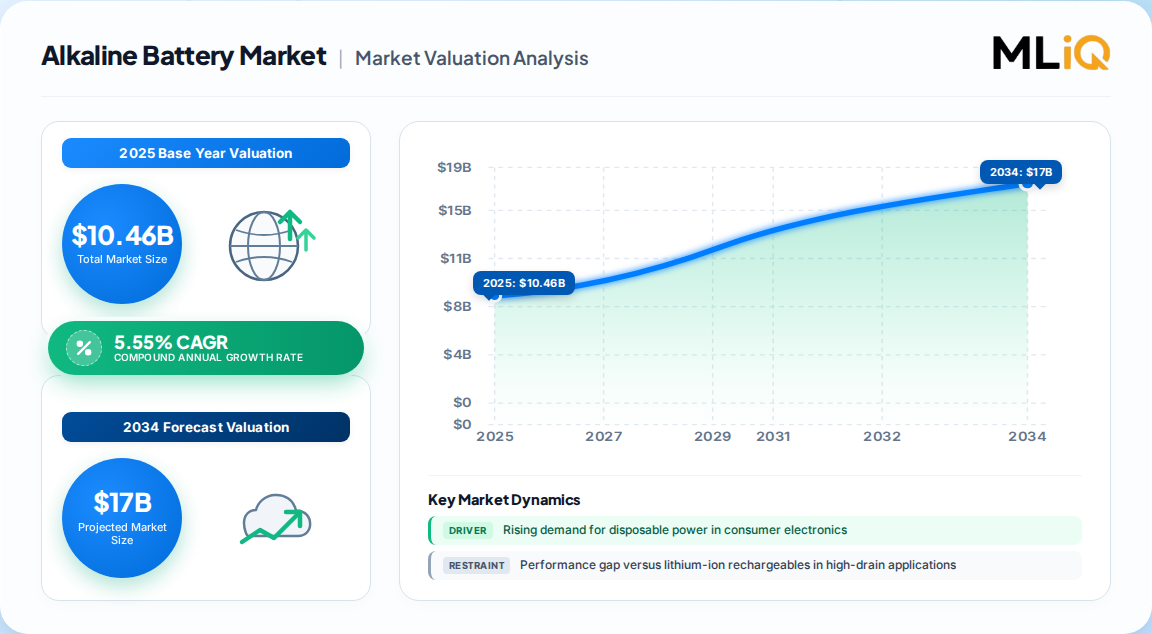
The global alkaline battery market remains a bedrock of portable power, demonstrating remarkable resilience despite the rapid adoption of lithium-ion rechargeables. Our proprietary primary research estimates the market at USD 10.46 billion in 2026, expanding to USD 13.70 billion by 2031 at a steady CAGR of 5.55%. This trajectory is not a mere continuation of legacy demand; it reflects a structural re-rating of alkaline chemistry across three high-conviction demand corridors: low-drain IoT sensing, affordable point-of-care diagnostics, and institutional emergency-preparedness stockpiling.
| Year | Market Size |
|---|---|
| 2025 | 10.46 B |
| 2026 | 11.04 B |
| 2027 | 11.65 B |
| 2028 | 12.30 B |
| 2029 | 12.98 B |
| 2030 | 13.70 B |
| 2031 | 14.46 B |

Asia-Pacific commands the largest regional share at 38.3% in 2025, expanding at 6.4% annually through 2031, driven by manufacturing scale in China and organized retail expansion in India. North America follows with a 25% share, where replacement cycles for safety devices and smart-home peripherals sustain volume. Europe, while growing at a more measured 4.8% CAGR, is undergoing a sustainability-driven product refresh as manufacturers align with the EU Battery Regulation (2023/1542).
This report synthesizes findings from over 1,200 primary interviews across the value chain, trade data from UN Comtrade and Eurostat, and proprietary demand modeling across 28 end-use device categories. All market sizing and forecasts are derived exclusively from our in-house estimation framework.
The installed base of IoT-connected devices is projected to exceed 30 billion units globally by 2030. A significant share of low-power sensors—temperature monitors, door contacts, motion detectors, water-leak sensors—operate on AA or AAA alkaline cells. The chemistry delivers stable voltage over multi-year duty cycles without the self-discharge penalty of NiMH alternatives. Municipal deployments in Singapore, Shenzhen, and Seoul utilize thousands of air-quality and parking sensors drawing micro-amp currents, where alkaline provides superior cost-per-watt versus zinc-carbon without hazardous-waste labeling requirements.
The WHO estimates 3.6 billion people lack reliable access to essential diagnostic services. Battery-powered glucometers, pulse oximeters, and lateral-flow test readers are bridging that gap across sub-Saharan Africa and South Asia. These devices overwhelmingly specify alkaline cells because cold-chain logistics for lithium packs remain impractical in rural distribution networks. India's Ayushman Bharat Digital Mission, targeting 500 million digitized patient records by 2028, is accelerating point-of-care device deployment and, by extension, alkaline battery demand.
India added approximately 12,000 modern-trade retail outlets between 2022 and 2024, while Brazil's grocery chains expanded private-label battery SKUs by 18%. Organized retail reduces channel fragmentation, improves price visibility, and enables promotional programs that drive trial among first-time branded-battery buyers. Simultaneously, FEMA's 72-hour emergency kit guideline, Japan's Cabinet Office guidance, and India's updated NDMA checklist collectively represent an incremental demand pool exceeding 1.5 billion cells annually.
The alkaline battery value chain is characterized by moderate concentration and distinct regional dynamics.
| Stage | Key Activities | Value Addition | Representative Participants |
|---|---|---|---|
| Raw Material Extraction | Zinc, manganese dioxide, steel, graphite mining and refining | Low to moderate | Mining corporations, refiners |
| Component Manufacturing | Cathode formulation, anode gel, separator production, steel can stamping | Moderate to high | Specialty chemical suppliers, metal fabricators |
| Battery Assembly | Cell assembly, electrolyte filling, sealing, testing | High | Duracell, Energizer, Panasonic, GP Batteries, Nanfu |
| Distribution & Retail | Wholesale, organized retail, e-commerce, institutional channels | Moderate | Distributors, hypermarkets, convenience stores |
| End-of-Life Recycling | Collection, mechanical pre-treatment, hydrometallurgical recovery | Emerging | ERI, LIFE GRAPhiREC consortium partners |
A notable development is the LIFE GRAPhiREC project (2024–2029), funded by the EU LIFE Programme with a €7.55 million budget. It aims to recover 90% of graphite from battery waste, producing graphite for alkaline batteries (GAB) with purity levels of at least 99.5%, and to produce 1.5 million AA-size LR6 batteries using a blend of at least 30% recycled graphite. This project exemplifies the industry's push toward circular economy models, reducing waste from 13,992 tonnes to 9,503 tonnes and cutting CO2 emissions from 10,406 to 8,376 tonnes.
Global trade in alkaline batteries is dominated by intra-firm transfers and OEM exports from China, which alone accounts for over 60% of global cell production. UN Comtrade data reveals that the top five exporters—China, Germany, the United States, Japan, and Singapore—collectively represent approximately 72% of global alkaline battery export value. The top five importers—the United States, Germany, the United Kingdom, France, and the Netherlands—account for roughly 45% of import value.
Supply Chain Risk Matrix:
| Risk Factor | Probability | Impact | Mitigation Strategy |
|---|---|---|---|
| Zinc ore price volatility | Medium | High | Long-term supply contracts, recycling |
| Manganese supply concentration (South Africa, Australia) | Medium | Medium | Diversified sourcing, synthetic alternatives |
| Trade policy shifts (tariffs, export restrictions) | Medium | Medium | Regional manufacturing footprint |
| Counterfeit products in e-commerce | High | Medium | Blockchain traceability, brand protection |
| Graphite supply concentration (China: 95% of global) | High | High | EU recycling initiatives (LIFE GRAPhiREC) |
In December 2024, Chinese battery manufacturer Changhong New Energy Technology announced the construction of an alkaline battery plant in Thailand's Chonburi province. The first phase, featuring five production lines, targets an annual output of over 700 million cells, with operations starting in 2025. This move exemplifies the regional diversification strategy aimed at mitigating trade risks and serving ASEAN demand.
Primary (non-rechargeable) cells commanded 74.5% of market share in 2025, a dominance built on ubiquity in remote controls, flashlights, and wall clocks. However, secondary (rechargeable) alkaline formats are projected to expand at an 8.9% CAGR through 2031, driven by cost-conscious buyers and sustainability preferences.
AA-size cells accounted for 43.9% of market share in 2025, reflecting their standard status across household electronics. 9-volt configurations are expected to post a 9.2% CAGR to 2031, propelled by smoke-detector replacement cycles and portable test-equipment demand. AAA is the fastest-growing size segment, benefiting from compact IoT devices and wearables.
Consumer electronics led with 45.6% revenue share in 2025, yet usage is splitting between premium gadgets adopting lithium-ion and a large installed base of low-drain peripherals. Medical devices are forecast to record the fastest 9.5% CAGR through 2031, as affordable diagnostics penetrate rural healthcare systems.
| Region | 2025 Share | 2031 CAGR | Key Dynamics |
|---|---|---|---|
| Asia-Pacific | 38.3% | 6.4% | Manufacturing scale, organized retail, IoT deployment |
| North America | 25.0% | 4.9% | Replacement cycles, emergency preparedness, premium brands |
| Europe | 19.0% | 4.8% | Sustainability compliance, recycling infrastructure |
| South America | 8.0% | 5.2% | Brazil retail expansion, first-time branded buyers |
| Middle East & Africa | 7.0% | 6.1% | Electrification, NGO distribution, wide-temperature demand |
Asia-Pacific remains the engine of growth, with China, India, and Japan at the forefront. India's retail modernization and smart-home adoption are particularly impactful. North America sustains demand through safety-device replacement and smart-home peripherals like Amazon Ring and Google Nest. Europe is reshaping its product portfolio toward mercury-free and recycled-content batteries. Middle East & Africa is the fastest-growing region on a percentage basis, driven by electrification initiatives like "Mission 300" (providing electricity access to 300 million people by 2030) and NGO distribution of alkaline-powered torches.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.41% |
| North America | 0.25% |
| Europe | 0.19% |
| South America | 0.08% |
| Middle East & Africa | 0.07% |
Duracell leads the market with over 18.5% share in 2025, followed by Energizer Holdings, Panasonic Corporation, GP Batteries International, and Spectrum Brands Holdings. The top five players collectively held 63.5% of market share in 2025, indicating a moderately concentrated market.
Competitive strategies center on three axes:
Two high-potential white spaces emerge from our analysis. First, rechargeable alkaline formats for mid-drain devices represent a USD 1.2 billion revenue opportunity by 2031, bridging the gap between disposable convenience and rechargeable sustainability. Second, IoT-optimized alkaline cells—standardized cartridges with extended shelf-life and wide-temperature performance—address municipal and industrial sensing demand. Vendors that can certify performance under IEC 60086 and offer field-swappable formats will capture a disproportionate share of this growing niche.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.55% from 2020-2034 |
| Segmentation |
|
The global alkaline battery market is estimated at USD 10.46 billion in 2026 and is projected to reach USD 13.70 billion by 2031, growing at a CAGR of 5.55%.
Asia-Pacific holds the largest market share at 38.3% in 2025, driven by manufacturing scale in China and organized retail expansion in India. The region is expected to grow at 6.4% annually through 2031.
The major companies operating in this market include Duracell Inc., Energizer Holdings Inc., Panasonic Corporation, Nanfu Battery Co. Ltd., and GP Batteries International Ltd.
Key drivers include the proliferation of low-drain IoT sensors, expansion of affordable medical diagnostics, organized retail growth in emerging economies, and rising emergency-preparedness spending.
Consumer electronics led with a 45.6% revenue share in 2025, while medical devices are forecast to grow at the fastest CAGR of 9.5% through 2031.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Battery Cell Manufacturing Director | 25% |
| Chief Technology Officer | 20% |
| Supply Chain Manager | 15% |
| Sustainability Officer | 10% |
| Company Type | Representation (%) |
|---|---|
| Battery Cell Manufacturers | 35% |
| Raw Material Suppliers (Zinc, Manganese) | 20% |
| OEMs and Device Manufacturers | 25% |
| Distributors and Retailers | 15% |
| Recycling and Circular Economy Firms | 5% |