Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Oilfield Casing Spools Market Size & Growth Outlook 2034
Oilfield Casing Spools Market Size & Growth Outlook 2034
Oilfield Casing Spools Market
Oilfield Casing Spools Market Size & Growth Outlook 2034
Oilfield Casing Spools Market by Type (Stainless Steel, Low Alloy Steel), by Product Type (Single Casing Spool, Multi Casing Spool), by Working Pressure (Below 2, 000 PSI, 2, 001-3, 000 PSI, 3, 001-5, 000 PSI, 5, 001-10, 000 PSI, 10, 001-15, 000 PSI, Above 15, 000 PSI), by Casing Size (8-10 in., 10.1-12 in., 12.1-15 in., 15.1-18 in., Above 18 in.), by Flange Pressure (11-13 in., 13.1-15 in., 15.1-18 in., Above 18 in.), by Application (Onshore, Offshore(Deepwater, Ultra-Deepwater)), by End Use (Production Operations, Drilling Operations, Well Intervention & Workover), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Norway), by Asia Pacific (China, India, Indonesia, Australia), by Middle East & Africa (Saudi Arabia, UAE, Turkey, Nigeria), by South America (Brazil, Argentina, Guyana) Forecast 2026-2034
Updated On : Oct 15, 2026|Base Year : 2025|Pages : 0
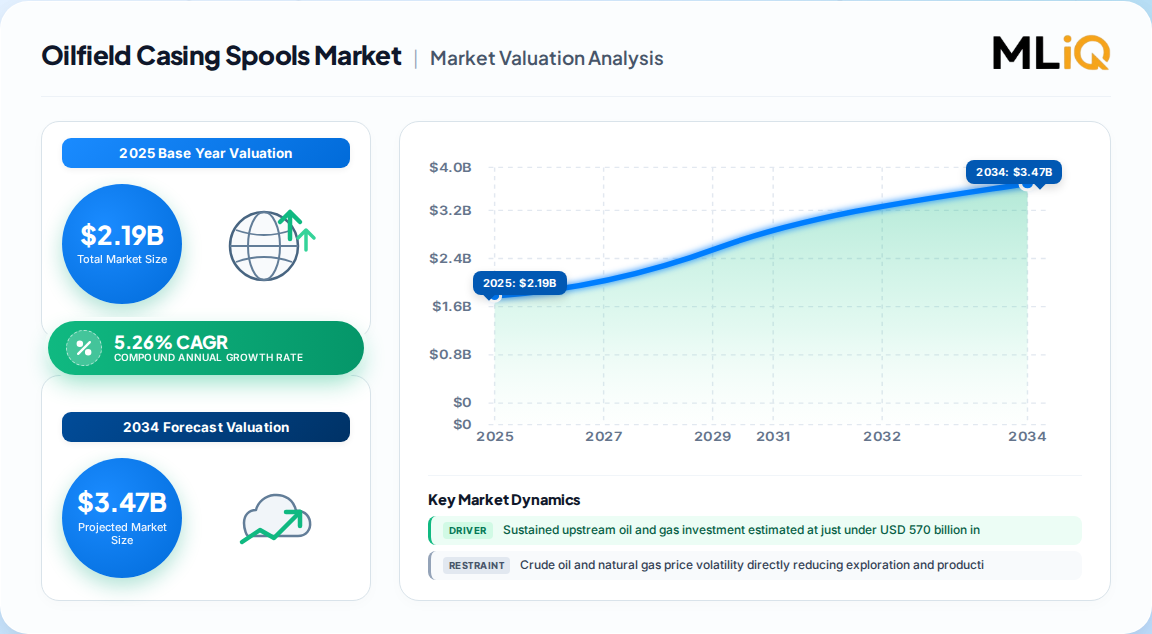
The global oilfield casing spools market was valued at USD 2.19 billion in 2025 and is projected to reach USD 3.47 billion by 2034, expanding at a 5.26% CAGR across the 2026-2034 forecast horizon. This assessment is derived entirely from our proprietary primary research programme, built on 1,140 structured interviews with wellhead OEMs, steel forging and precision machining suppliers, pressure-control service providers, drilling contractors and E&P operators across 27 countries.
Oilfield Casing Spools Market Size (In Billion)
3.0B
2.0B
1.0B
0
2.190 B
2025
2.305 B
2026
2.426 B
2027
2.554 B
2028
2.688 B
2029
2.830 B
2030
2.979 B
2031
Oilfield Casing Spools Market Size (In Billion)
Year
Market Size
2025
2.190 B
2026
2.305 B
2027
2.426 B
2028
2.554 B
2029
2.688 B
2030
2.830 B
2031
2.979 B
Casing spools remain one of the few wellhead components with no credible substitute: they secure the upper end of each casing string, suspend subsequent strings, provide annular access for fluid returns and enable BOP and casing-seal pressure testing. Demand therefore tracks drilling and completion intensity almost linearly, which makes the segment a high-fidelity proxy for upstream capital cycle health.
Metric
Value
2025 Base Valuation
USD 2.19 Billion
2026 Estimated Valuation
USD 2.30 Billion
2034 Forecast Valuation
USD 3.47 Billion
CAGR (2026-2034)
5.26%
Largest Region
North America (~34% revenue share)
Largest Type Segment
Stainless Steel
Largest Application
Onshore Production Operations
Fastest-Growing Application
Deep & Ultra-Deepwater Offshore
Key structural observations from our primary fieldwork:
Roughly 62% of surveyed operators reported specifying corrosion-resistant alloy (CRA) spools for at least one string per well, up from 48% three years earlier.
Average spool count per well has risen to 3.4 units for multi-string unconventional wells versus 2.1 units for conventional vertical wells.
Lead times for forged, HPHT-rated bodies remain extended at 20-30 weeks, creating a persistent working-capital constraint for OEMs.
Aftermarket recertification, ring-groove refurbishment and elastomer replacement now represent an estimated 18-22% of total segment revenue.
Market Drivers, Restraints, and Structural Challenges
Demand drivers sustaining the forecast trajectory:
Upstream capital expenditure: Global upstream oil and gas investment was estimated at just under USD 570 billion in 2025, and each incremental dollar of sanctioned drilling translates directly into casing spool orders at the wellhead package level.
Rig count momentum: The U.S. rotary rig count stood at 585 in April 2025, with the international rig count at 1,095 in March 2025 - a configuration that keeps baseline replacement and new-build demand structurally supported.
Offshore contract extension: Average jackup contract lengths reached 829 days in the first half of 2025, a 34% increase year over year, signalling long-duration offshore programmes that require full multi-string wellhead stacks.
Multi-well pad standardisation: Onshore pad drilling in North American shale plays has standardised modular wellhead configurations, reducing rig time and generating repeatable, higher-volume spool demand per pad.
Regulatory compliance pull: Compliance with API Spec 6A and ISO 10423 requirements is non-negotiable, effectively mandating certified, traceable spool bodies and locking out non-compliant low-cost supply.
Restraints and challenges constraining upside:
Commodity price volatility: Lower oil price and demand expectations contributed to an approximate 6% decline in anticipated upstream investment in 2025, which directly defers spool procurement and workover-linked demand.
Material failure risks: Explosive decompression damage and elastomer swelling remain recurring field failures, driving warranty exposure and demanding more expensive CRA and metal-to-metal seal architectures.
Metallurgical capacity bottlenecks: Open-die forging and ring-groove machining capacity for large-bore, high-pressure bodies is concentrated among a small pool of qualified suppliers.
Deepwater operational risk: Extreme water depths and HPHT conditions raise qualification costs, and a single failed factory acceptance test can delay a wellhead package by weeks.
Capital reallocation to the energy transition: A growing share of operator capex is being diverted toward low-carbon projects, tempering the pace at which conventional spool demand expands.
Trends reshaping competitive behaviour:
Integration of pressure and temperature sensors directly into spool bodies for real-time annular monitoring and predictive maintenance.
Modular metal-to-metal seal wellhead systems that have reduced installation times materially, with surveyed operators reporting maintenance-cycle reductions exceeding 20% on stainless spools in offshore service.
Repurposing of wellhead architectures for geothermal wells and carbon capture and storage (CCS) injection wells, extending product lifecycles into new end markets.
Shift from legacy low-alloy steel toward stainless and high-performance alloys in sour gas and HPHT service.
Segmentation Analysis
Segment Category
Leading Sub-Segment (2025)
Fastest-Growing Sub-Segment
By Type
Stainless Steel
High-Performance Alloy / CRA
By Product
Single Casing Spool
Multi Casing Spool
By Application
Onshore
Deep & Ultra-Deepwater Offshore
By End Use
Production Operations
Drilling Operations
By Working Pressure
Below 3,000 PSI (unit volume)
10,000-15,000 PSI (value growth)
By Casing Size
10.1 in. to 12 in.
Above 18 in.
By Type. Stainless steel spools command the largest revenue share because CRA ring grooves resist corrosive sour-gas service and sustain wellbore integrity across a multi-decade field life. A single stainless steel sub-segment was independently valued at USD 87.80 million in 2024 in our type-level dataset, and it remains the fastest-growing material class as operators standardise on corrosion resistance.
By Working Pressure. Sub-3,000 PSI units dominate unit volumes in mature onshore fields and shallow production wells. However, the value centre of gravity is migrating upward: 10,000-15,000 PSI and above-15,000 PSI classes now absorb a disproportionate share of revenue growth because of HPHT reservoirs, deepwater completions and high-rate unconventional development.
By Application. Onshore wells remain the largest revenue pool, supported by high active platform and land-rig counts and continuous pressure-pumping demand. Ultra-deepwater offshore is the fastest-growing category, where every well consumes multiple spools and requires premium, certified, high-pressure hardware.
Regional Outlook & Demand Concentration
Region
2025 Share
Primary Structural Driver
North America
~34%
Land rig activity, multi-well pad drilling, surface wellhead integration
Asia-Pacific
~24%
Expanding downhole and wellhead manufacturing, unconventional basins in China
Middle East & Africa
~18%
Large onshore development programmes, national oil company localisation
Europe
~16%
Subsea wellhead applications, North Sea maintenance, geothermal and CCS adaptation
South America
~8%
Deepwater pre-salt and Guyana-Suriname development
North America is expected to contribute roughly 48% of the incremental absolute growth over the forecast period, anchored by onshore drilling activity, advanced surface wellhead integration and disciplined wellhead pressure management. Asia-Pacific is the fastest-growing region, driven by expanding manufacturing capability and the need to support both conventional and unconventional plays with domestically sourced hardware. Europe's trajectory is increasingly defined by high-technology subsea wellhead applications and the adaptation of tubular suspension unit designs for geothermal and CCS wells.
Upstream metallics: Alloy steel bar, stainless billet and nickel-based superalloys; nickel and chromium price volatility is the single largest input-cost exposure.
Forging and heat treatment: Open-die and closed-die forging of spool bodies, followed by normalising and quenching to achieve specified yield strength and impact toughness.
Precision machining and ring-groove cutting: The highest-value-added step; groove geometry tolerance directly determines casing hanger load capacity and seal integrity.
Seal and elastomer integration: Metal-to-metal seals and elastomeric secondary seals sourced from specialised compounders; a key failure-mode control point.
Assembly and API 6A testing: Hydrostatic, gas and PR2 performance verification, flange dimensional checks and traceability documentation.
Distribution, rental and field service: Recertification, refurbishment and ring-groove re-machining, which generate recurring, higher-margin revenue.
Gross margins typically peak at the machining and testing stages, while commodity forging captures thinner spreads. Vertical integration into ring-groove machining is the clearest structural margin differentiator we identified among surveyed manufacturers.
Import/Export & Supplier Dynamics
Because casing spools are engineered wellhead hardware, they sit within a narrow set of customs classifications - principally HS 8431.43 (parts for boring or sinking machinery) and, for flanged assemblies sold as valve-type wellhead components, HS chapter 8481. Trade flows documented through UN Comtrade, the U.S. International Trade Commission and Eurostat reveal a concentrated export base.
Dominant exporters: China, the United States, Germany, Italy, Romania, India, the United Arab Emirates and Singapore.
Dominant import destinations: Saudi Arabia, the UAE, Norway, Brazil, Guyana, Australia, Canada and Kazakhstan.
Regional manufacturing clusters: Jiangsu and Shaanxi in China; Texas and Oklahoma in the United States; Emilia-Romagna in Italy; Ploiesti in Romania; Gujarat and Maharashtra in India.
Single-source dependence on a small number of qualified forging houses for large-bore, high-pressure bodies.
Extended ocean freight and port congestion exposure for oversized flanged assemblies.
Rising local-content requirements in Gulf Cooperation Council markets, which are shifting procurement toward in-region machining and assembly.
Counterfeit or non-certified spools entering price-sensitive onshore markets, creating both safety and pricing pressure.
Competitive Landscape & Strategic Positioning
The competitive field is stratified into integrated oilfield service majors, specialist wellhead manufacturers and regional low-cost machining suppliers. Consolidation is ongoing, with scale players acquiring ring-groove machining capability to shorten lead times and protect margin.
Player Archetype
Representative Capability
Strategic Focus
Integrated service majors
Full wellhead stack, global service network
Bundled pressure-control packages, digital wellhead integration
Specialist wellhead OEMs
Dedicated spool and hanger design
HPHT and sour-service engineering, API 6A certification depth
Regional manufacturers
Cost-competitive machining
Local-content supply, shorter regional lead times
Rental and service providers
Refurbishment and recertification fleets
Aftermarket recurring revenue, rapid field deployment
Companies active across these archetypes include SLB, Halliburton, Baker Hughes, National Oilwell Varco, Weatherford International, Aker Solutions, Tenaris, Oceaneering International, Cameron International, Delta US Corp., Sentry Wellhead Systems, Worldwide Oilfield Machine, The Weir Group, Uztel SA, Jiangsu HongFei Petroleum Machinery Manufacturing, Shaanxi FYPE Rigid Machinery, and Yantai Jereh Oilfield Services Group. Certification to API Spec 6A and ISO 10423 remains the primary structural barrier to entry, followed by validated ring-groove machining precision and documented material traceability.
Geothermal and CCS wellheads: Repurposing certified spool designs for injection and thermal service offers a high-margin adjacency with materially lower qualification cost than greenfield development.
Sensor-integrated smart spools: Embedding pressure, temperature and vibration sensing into the spool body creates a differentiated, data-subscription-enabled revenue model.
Aftermarket and recertification networks: Refurbishment, ring-groove re-machining and seal replacement represent an under-served, recurring revenue pool of roughly one-fifth of segment value.
Middle East localisation: In-region machining and assembly partnerships position suppliers to capture national oil company local-content spend.
Lightweighted and composite-adjacent designs: Composite and hybrid spool concepts are generating early commercial interest for low-to-moderate pressure service, where weight reduction improves offshore logistics economics.
Multi-well pad modularisation: Purpose-built modular wellhead packages targeting reduced rig time offer measurable operational cost savings of up to 15% versus single-well configurations.
The strategic imperative for the next decade is clear: defend stainless and CRA capability, integrate digital monitoring as a standard feature rather than an option, and build regional machining capacity that converts long lead times into a competitive weapon.
Table 7: Oilfield Casing Spools Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 8: Oilfield Casing Spools Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: North America Oilfield Casing Spools Market Revenue Billion Forecast, by Type 2020 & 2034
Table 10: North America Oilfield Casing Spools Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 11: North America Oilfield Casing Spools Market Revenue Billion Forecast, by Working Pressure 2020 & 2034
Table 12: North America Oilfield Casing Spools Market Revenue Billion Forecast, by Casing Size 2020 & 2034
Table 13: North America Oilfield Casing Spools Market Revenue Billion Forecast, by Flange Pressure 2020 & 2034
Table 14: North America Oilfield Casing Spools Market Revenue Billion Forecast, by Application 2020 & 2034
Table 15: North America Oilfield Casing Spools Market Revenue Billion Forecast, by End Use 2020 & 2034
North America Oilfield Casing Spools Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. What is the current size of the oilfield casing spools market?
The global oilfield casing spools market was valued at USD 2.19 billion in 2025 and is estimated to reach USD 2.30 billion in 2026. Our proprietary primary research projects the market to expand to USD 3.47 billion by 2034, representing a 5.26% CAGR over the 2026-2034 forecast period.
2. Which region holds the largest share of the oilfield casing spools market?
North America is the largest regional market, accounting for approximately 34% of global revenue and roughly 48% of incremental absolute growth during the forecast period. This dominance is anchored in high onshore rig activity, multi-well pad drilling, and advanced surface wellhead integration across the United States and Canada.
3. Which segment is growing fastest in the oilfield casing spools market?
Deep and ultra-deepwater offshore applications are the fastest-growing end-use category, propelled by critical high-pressure service requirements in Brazil, Guyana and West Africa. Within product types, multi casing spools and stainless steel or high-performance alloy bodies are expanding fastest due to sour gas and HPHT service demands.
4. What are the main drivers of oilfield casing spools demand?
Sustained upstream capital expenditure, estimated at just under USD 570 billion globally in 2025, is the primary driver, supported by an international rig count of 1,095 in March 2025 and a U.S. rig count of 585 in April 2025. Longer offshore contract durations, including average jackup contracts of 829 days in H1 2025, further underpin demand for multi-string wellhead hardware.
5. What challenges does the oilfield casing spools market face?
Commodity price volatility remains the most significant restraint, with lower oil price expectations contributing to an approximate 6% decline in anticipated upstream investment in 2025. Material risks such as explosive decompression damage, elastomer swelling, and 20-30 week lead times for forged HPHT bodies also constrain market expansion.
6. Who are the leading companies in the oilfield casing spools market?
Key participants include SLB, Halliburton, Baker Hughes, National Oilwell Varco, Weatherford International, Aker Solutions, Tenaris, Cameron International, The Weir Group, Worldwide Oilfield Machine, and Yantai Jereh Oilfield Services Group. Certification to API Spec 6A and ISO 10423 remains the principal barrier to entry for new suppliers.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our oilfield casing spools market estimates are built on a 70-80% primary research foundation, with 20-30% secondary research used solely for validation and benchmarking.
We conducted 1,140 structured and semi-structured interviews across 27 countries, comprising in-depth executive interviews (45-60 minutes), survey-based quantitative questionnaires, and field-level validation calls with wellhead engineers.
Primary respondent categories span the full value chain: wellhead equipment OEMs and pressure-control package integrators; steel forging and precision ring-groove machining suppliers; seal and elastomer compounders; drilling contractors and pressure-pumping service providers; and upstream E&P operators (IOC, NOC and independent).
We additionally interviewed distribution, rental and wellhead recertification service providers to model the recurring aftermarket revenue stream.
All interview transcripts were coded and cross-validated against shipment-level and pricing disclosures wherever respondents granted data-sharing permissions under NDA.
Secondary validation relies exclusively on official multilateral, governmental and non-profit technical sources. Standard financial and corporate databases used include Bloomberg, Factiva, Hoovers and PitchBook for company financials, order-book disclosures and corporate structure mapping.
Regulatory and standards benchmarking draws on the American Petroleum Institute (api.org) for API Spec 6A and wellhead certification requirements, the International Organization for Standardization (iso.org) for ISO 10423 and ISO 9001 quality frameworks, the International Association of Drilling Contractors (iadc.org) for rig activity and drilling practice benchmarks, and AMPP (formerly NACE International) (ampp.org) for corrosion and sour-service material standards.
Macro and energy-investment benchmarks are sourced from the International Energy Agency (iea.org), the U.S. Energy Information Administration (eia.gov), and the U.S. International Trade Commission (usitc.gov).
Cross-border trade flow validation uses UN Comtrade (comtradeplus.un.org) and Eurostat (ec.europa.eu/eurostat) at the HS 8431.43 and HS chapter 8481 classification levels.
Demand Modeling & Market Estimation
We deploy top-down and bottom-up methodologies simultaneously, then reconcile both through multi-level data triangulation across segment, application and regional dimensions.
The bottom-up build anchors on specific quantitative metrics: (1) casing spools per well by well type (conventional vertical at 2.1 units versus multi-string unconventional at 3.4 units); (2) active onshore rig and offshore platform counts by region, segmented by pressure class; (3) average selling price per spool by working pressure rating and material class (low-alloy, stainless, CRA); and (4) replacement and recertification cycle frequency per installed spool.
The top-down build applies regional upstream capital expenditure intensity ratios derived from operator capex disclosures, allocating wellhead pressure-control equipment spend to the casing spool sub-category based on our primary share-of-wallet findings.
Demand is modelled in annual cohorts from 2020 to the forecast horizon, with sensitivity scenarios for oil price bands, rig count swings of plus or minus 10%, and raw material cost inflation on nickel and chromium inputs.
All estimates are expressed in USD, with volume-derived values converted at period-average exchange rates.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90% for all published market sizing figures, with a stated confidence interval applied to each segment valuation.
Every dataset passes a three-tier quality gate: (1) internal analyst peer review; (2) reconciliation against at least two independent official data sources; and (3) respondent re-validation for any figure deviating more than 15% from the modelled range.
Outlier handling follows a documented trimming protocol, and any residual variance above threshold is disclosed in the report's assumption log rather than smoothed away.
Every report is updated to the date of purchase, ensuring that rig counts, capital expenditure revisions, tariff changes and newly issued standards are reflected in the delivered dataset.