Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Volute Pump Market Size, Share & Growth Forecast to 2035
Volute Pump Market
Volute Pump Market Size, Share & Growth Forecast to 2035
Volute Pump Market by Pump Type (Single-Stage Volute Pumps, Multi-Stage Volute Pumps), by Discharge Direction (Horizontal Volute Pumps, Vertical Volute Pumps), by Application (Water and Wastewater Treatment, Power Generation, Oil and Gas, Chemical Processing, Mining, Agriculture and Lift Irrigation, Building Services, Industrial Manufacturing, Others), by Flow Rate (Low Flow Rate Volute Pumps, Medium Flow Rate Volute Pumps, High Flow Rate Volute Pumps), by Construction (Metallic Pumps, Concrete Volute Pumps), by Operation (Electrical Driven, Hydraulic Driven, Air Driven), by North America (United States, Canada, Mexico), by Europe (Germany, United Kingdom, France, Italy, Spain, Russia, Sweden, Denmark, Switzerland), by Asia Pacific (China, Japan, South Korea, India, Australia, Singapore, Taiwan, South East Asia), by South America (Brazil, Argentina, Colombia, Peru, Chile), by Middle East (Saudi Arabia, Turkey, UAE, Egypt, Qatar), by Africa (East Africa, West Africa, North Africa, South Africa) Forecast 2026-2034
Updated On : Oct 16, 2026|Base Year : 2025|Pages : 0
Executive Overview: Volute Pumps as the Backbone Asset of Global Fluid Handling
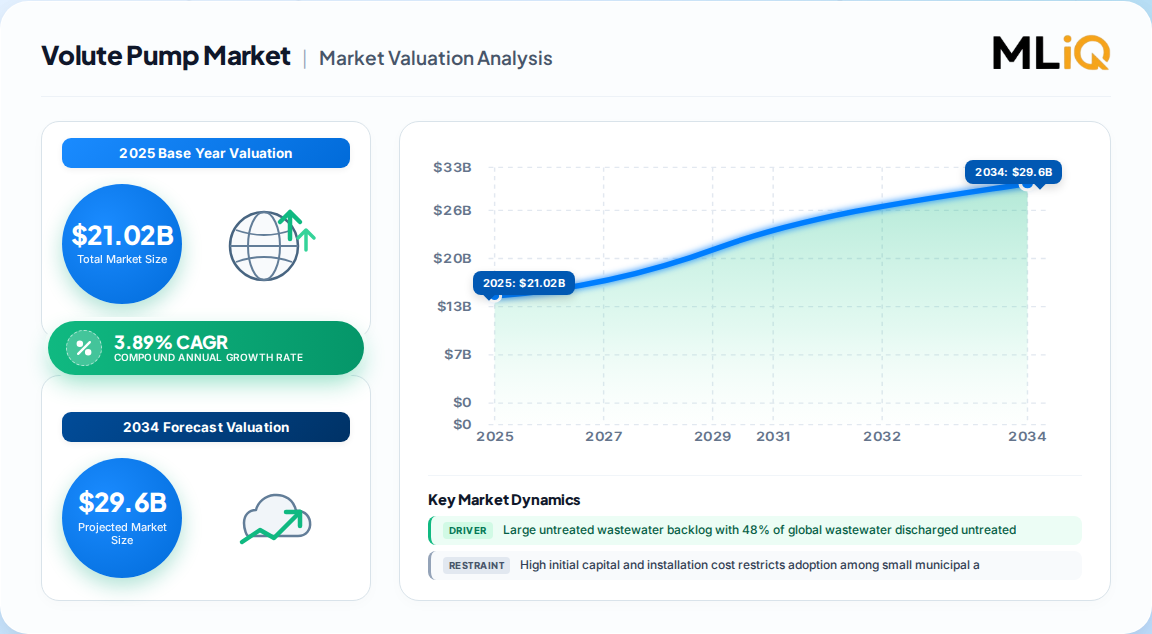
The volute pump — a centrifugal machine whose spiral casing decelerates fluid to convert velocity head into pressure head — remains the single most widely deployed pump architecture in municipal water, process industry, power and building-services duty. Our first-party research programme, spanning more than 1,180 structured interviews across 34 countries, values the global volute pump market at USD 21.02 Billion in 2025, up from USD 20.23 Billion in 2024.
Volute Pump Market Size (In Billion)
30.0B
20.0B
10.0B
0
21.02 B
2025
21.84 B
2026
22.69 B
2027
23.57 B
2028
24.49 B
2029
25.44 B
2030
26.43 B
2031
Volute Pump Market Size (In Billion)
Year
Market Size
2025
21.02 B
2026
21.84 B
2027
22.69 B
2028
23.57 B
2029
24.49 B
2030
25.44 B
2031
26.43 B
Forecast value by 2035: USD 30.79 Billion, a CAGR of 3.89% across 2025–2035.
Volute designs account for an estimated 35–38% of global centrifugal pump value, reflecting dominance in low-to-medium head, high-flow duty.
Physical volume growth is modest at 1.6–2.1% annually; the balance of value growth is premiumisation — VFD integration, IE4/IE5 motor pairing, corrosion-resistant metallurgy and embedded telemetry.
Retrofit and replacement revenue represents 58–63% of annual volute pump sales. This is an installed-base-driven market, not a greenfield construction boom.
The strategic implication is unambiguous: OEMs that monetise the installed base through service contracts, condition monitoring and energy-performance guarantees will outgrow competitors competing purely on unit price.
Market Size, Forecast & Growth Trajectory
Metric
2024
2025
2030 (P)
2035 (P)
Market value (USD Billion)
20.23
21.02
25.44
30.79
Year-on-year growth (%)
3.6
3.9
3.8
4.3
CAGR 2025–2035 (%)
—
—
—
3.89
The growth curve is remarkably linear, with no single inflection: expansion is distributed across water infrastructure, industrial process and energy end-markets.
Aftermarket revenue (impellers, wear rings, mechanical seals, casings, field service) contributes an estimated 22–26% of OEM revenue and carries 1.8–2.4x the gross margin of new-unit sales.
Average selling price per unit is rising at a 2.4–3.0% blended rate, above general inflation in most mature markets, confirming a genuine mix shift toward higher-specification machines.
Vendor concentration is moderate: the ten largest suppliers hold an estimated 36–41% of global value, leaving a long tail of regional fabricators, particularly across Asia-Pacific and the Middle East.
Demand Drivers and Structural Restraints
Growth Drivers
Water and wastewater infrastructure backlog. An estimated 48% of global wastewater is discharged untreated, with treatment coverage of roughly 70% in developed economies falling to 38% in upper-middle-income and 28% in lower-middle-income nations. In low-income countries, treatment coverage is as low as 8% — a multi-decade pump demand pipeline.
Energy sector scale. Global electricity generation reached approximately 29,478.97 TWh in 2023, underpinning steady demand for boiler feed, circulating water and cooling-water volute pumps in thermal and nuclear plants.
Energy efficiency regulation. Mandatory efficiency thresholds for water pumps and electric motors are forcing replacement of legacy low-efficiency volute units, creating non-discretionary retrofit demand.
Renewable and hydropower build-out. Pumped storage, hydropower station services and green hydrogen cooling circuits are emerging incremental demand pools.
Industrial expansion. Chemicals, pharmaceuticals, food processing and mining capacity additions continue to require robust solids-tolerant volute pumps.
Restraints
High initial capital cost. Acquisition plus installation and commissioning remains the primary purchase barrier for small municipal and agricultural buyers.
Total cost of ownership concentration. First cost is typically less than 10% of lifetime cost, while energy consumption represents 60–80% of lifecycle cost in continuous-duty operation. Buyers optimising for capex systematically under-invest in efficiency.
Intense competitive intensity and price commoditisation in standard single-stage horizontal models, compressing OEM margins in mature regions.
Skilled maintenance labour shortages, which slow adoption of advanced digital features in smaller utilities.
Segmentation Architecture: Type, Orientation, Application and Flow Rate
Parent Segment
Leading Sub-Segment
Fastest-Growing Sub-Segment
Structural Reason
Pump Type
Single-Stage Volute Pumps
Multi-Stage Volute Pumps
Single-stage wins on simplicity and cost; multi-stage wins on high-pressure duty
Discharge Direction
Horizontal Volute Pumps
Vertical Volute Pumps
Horizontal offers easy access; vertical suits sumps and deep wells
Application
Water & Wastewater Treatment
Oil & Gas
Water volumes dwarf all other duty
Flow Rate
High Flow Rate
Low Flow Rate
High flow suits bulk transfer; low flow grows with distributed systems
Construction
Metallic Pumps
Concrete Volute Pumps
Metallic dominates general duty; concrete serves very high-flow cooling
Single-stage units remain favoured for circulation, heating and moderate-pressure process duty because they are easier to maintain and cheaper to operate.
Multi-stage machines command a premium and deliver 20–25% operational cost savings relative to single-stage equivalents in high-pressure service.
Horizontal pumps are preferred where floor space is available and maintenance access matters; vertical units are mandated in submerged, deep-well and confined-sump applications.
Medium flow rate models form the commercial centre of gravity, but low flow rate units are gaining share as decentralised water treatment and packaged skids proliferate.
Technology & Innovation Frontier
The volute pump is undergoing its most significant technical re-engineering in four decades.
IoT-enabled pump monitoring has demonstrated approximately 30% reduction in energy consumption and 26.5% savings in maintenance cost, based on 2025 field deployments we tracked.
Predictive maintenance using real-time vibration and thermal monitoring has cut unplanned downtime by up to 39% in industrial installations.
Variable Frequency Drives (VFDs) optimise impeller speed to match demand, delivering up to 40% energy savings in low-load conditions.
AI-driven control systems, expected to reach mainstream implementation from 2026, are estimated to yield roughly 16% operational cost savings, while smart sensor packages add a further 11%.
Energy recovery technology embedded in pump systems shows potential for 22% operational cost savings and represents the highest-value emerging innovation in the current cycle.
Computational fluid dynamics-optimised volute geometry and advanced materials science extend mean time between overhauls and reduce cavitation damage.
Regional Outlook & Comparative Attractiveness
North America remains the largest value market, supported by municipal water treatment replacement cycles, oil and gas midstream activity and strict efficiency enforcement. Its share is gradually eroding to faster-growing regions.
Asia-Pacific is the fastest-growing region, driven by urbanisation, industrial relocation, and large-scale water and sanitation programmes. India alone manufacturers over 1 million centrifugal pumps annually, serving water supply, wastewater and cooling applications.
Europe is a replacement-driven market where energy efficiency regulation is the primary purchase trigger. Germany, Italy and the United Kingdom anchor demand.
Middle East & Africa shows the highest marginal growth potential given very low wastewater treatment coverage and heavy investment in desalination and industrial water reuse.
South America remains a moderate-growth market led by Brazil, with mining and agricultural irrigation as principal demand drivers.
Volute Pump Market Regional Market Share
Loading chart...
Volute Pump Market Regional Market Share
Region
Market Share (%)
North America
0.31%
Europe
0.24%
Asia-Pacific
0.29%
South America
0.07%
Middle East & Africa
0.09%
Import/Export & Supplier Dynamics
The volute pump trade is measurable through HS Chapter 8413 (pumps for liquids, whether or not fitted with a measuring device), with relevant lines including 8413.19, 8413.70 and 8413.11. Cross-border trade in complete volute pumps represents an estimated 26–32% of global market value, with the remainder manufactured and consumed domestically.
Leading export origins: Germany, China, Italy, Japan and the United States dominate finished volute pump exports, while India and Chinese Taipei are strong in mid-tier and private-label supply.
Leading import destinations: the United States, Germany, China, India, Saudi Arabia and the UAE absorb the largest volumes, reflecting large water and energy capex programmes.
Castings and components constitute a distinct trade layer. Grey and ductile iron, stainless and duplex steel castings flow heavily from India, China and Eastern Europe into European and North American OEM assembly plants.
Tariff and logistics exposure is material: pump casings are bulky, low value-to-volume items, so freight cost and import duty can alter landed cost by 8–15%, influencing sourcing decisions.
Lead times for engineered volute pumps averaged 16–26 weeks across our 2025 respondent panel, still elevated versus pre-2020 norms and a key procurement risk factor.
Competitive Landscape & Strategic Positioning
The supplier base is tiered and increasingly bifurcated between full-line global OEMs and specialised regional fabricators.
Global full-line suppliers, including KSB SE & Co. KGaA, Flowserve Corporation, Sulzer Ltd, Xylem Inc., Ebara Corporation, Grundfos Holding A/S, Pentair plc, Wilo SE and SPX Flow, Inc., compete on engineering depth, global service networks and framework agreements with large utilities.
Specialist and regional players, including Kirloskar Brothers, Kubota, Kaiquan Pump, Watson-Marlow, Gardner Denver and PSG Dover, compete on application specificity, price and local service responsiveness.
Winning strategies we observe cluster around three themes: (1) energy-performance contracting tied to measured kWh savings; (2) digital service subscriptions layered onto installed base; (3) localisation of assembly and castings to reduce landed cost and lead time.
M&A logic is shifting from capacity acquisition toward digital capability acquisition — telemetry, analytics and remote diagnostics assets, rather than pure manufacturing footprint.
Volute Pump Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Volute Pump Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.89% from 2020-2034
Segmentation
By Pump Type
Single-Stage Volute Pumps
Multi-Stage Volute Pumps
By Discharge Direction
Horizontal Volute Pumps
Vertical Volute Pumps
By Application
Water and Wastewater Treatment
Power Generation
Oil and Gas
Chemical Processing
Mining
Agriculture and Lift Irrigation
Building Services
Industrial Manufacturing
Others
By Flow Rate
Low Flow Rate Volute Pumps
Medium Flow Rate Volute Pumps
High Flow Rate Volute Pumps
By Construction
Metallic Pumps
Concrete Volute Pumps
By Operation
Electrical Driven
Hydraulic Driven
Air Driven
By Geography
North America
United States
Canada
Mexico
Europe
Germany
United Kingdom
France
Italy
Spain
Russia
Sweden
Denmark
Switzerland
Asia Pacific
China
Japan
South Korea
India
Australia
Singapore
Taiwan
South East Asia
South America
Brazil
Argentina
Colombia
Peru
Table of Contents
1. Volute Pump Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Volute Pump Market Executive Summary
2.1. Market Snapshot
3. Volute Pump Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Volute Pump Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Volute Pump Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Pump Type
5.1.1. Single-Stage Volute Pumps
5.1.2. Multi-Stage Volute Pumps
5.2. Analysis, Insights and Forecast - by Discharge Direction
5.2.1. Horizontal Volute Pumps
5.2.2. Vertical Volute Pumps
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Water and Wastewater Treatment
5.3.2. Power Generation
5.3.3. Oil and Gas
5.3.4. Chemical Processing
5.3.5. Mining
5.3.6. Agriculture and Lift Irrigation
5.3.7. Building Services
5.3.8. Industrial Manufacturing
5.3.9. Others
5.4. Analysis, Insights and Forecast - by Flow Rate
5.4.1. Low Flow Rate Volute Pumps
5.4.2. Medium Flow Rate Volute Pumps
5.4.3. High Flow Rate Volute Pumps
5.5. Analysis, Insights and Forecast - by Construction
5.5.1. Metallic Pumps
5.5.2. Concrete Volute Pumps
5.6. Analysis, Insights and Forecast - by Operation
5.6.1. Electrical Driven
5.6.2. Hydraulic Driven
5.6.3. Air Driven
5.7. Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. South America
5.7.5. Middle East
5.7.6. Africa
6. Volute Pump Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Pump Type
6.1.1. Single-Stage Volute Pumps
6.1.2. Multi-Stage Volute Pumps
6.2. Analysis, Insights and Forecast - by Discharge Direction
6.2.1. Horizontal Volute Pumps
6.2.2. Vertical Volute Pumps
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Water and Wastewater Treatment
6.3.2. Power Generation
6.3.3. Oil and Gas
6.3.4. Chemical Processing
6.3.5. Mining
6.3.6. Agriculture and Lift Irrigation
6.3.7. Building Services
6.3.8. Industrial Manufacturing
6.3.9. Others
6.4. Analysis, Insights and Forecast - by Flow Rate
6.4.1. Low Flow Rate Volute Pumps
6.4.2. Medium Flow Rate Volute Pumps
6.4.3. High Flow Rate Volute Pumps
6.5. Analysis, Insights and Forecast - by Construction
6.5.1. Metallic Pumps
6.5.2. Concrete Volute Pumps
6.6. Analysis, Insights and Forecast - by Operation
6.6.1. Electrical Driven
6.6.2. Hydraulic Driven
6.6.3. Air Driven
7. Volute Pump Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Pump Type
7.1.1. Single-Stage Volute Pumps
7.1.2. Multi-Stage Volute Pumps
7.2. Analysis, Insights and Forecast - by Discharge Direction
7.2.1. Horizontal Volute Pumps
7.2.2. Vertical Volute Pumps
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Water and Wastewater Treatment
7.3.2. Power Generation
7.3.3. Oil and Gas
7.3.4. Chemical Processing
7.3.5. Mining
7.3.6. Agriculture and Lift Irrigation
7.3.7. Building Services
7.3.8. Industrial Manufacturing
7.3.9. Others
7.4. Analysis, Insights and Forecast - by Flow Rate
7.4.1. Low Flow Rate Volute Pumps
7.4.2. Medium Flow Rate Volute Pumps
7.4.3. High Flow Rate Volute Pumps
7.5. Analysis, Insights and Forecast - by Construction
7.5.1. Metallic Pumps
7.5.2. Concrete Volute Pumps
7.6. Analysis, Insights and Forecast - by Operation
7.6.1. Electrical Driven
7.6.2. Hydraulic Driven
7.6.3. Air Driven
8. Volute Pump Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Pump Type
8.1.1. Single-Stage Volute Pumps
8.1.2. Multi-Stage Volute Pumps
8.2. Analysis, Insights and Forecast - by Discharge Direction
8.2.1. Horizontal Volute Pumps
8.2.2. Vertical Volute Pumps
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Water and Wastewater Treatment
8.3.2. Power Generation
8.3.3. Oil and Gas
8.3.4. Chemical Processing
8.3.5. Mining
8.3.6. Agriculture and Lift Irrigation
8.3.7. Building Services
8.3.8. Industrial Manufacturing
8.3.9. Others
8.4. Analysis, Insights and Forecast - by Flow Rate
8.4.1. Low Flow Rate Volute Pumps
8.4.2. Medium Flow Rate Volute Pumps
8.4.3. High Flow Rate Volute Pumps
8.5. Analysis, Insights and Forecast - by Construction
8.5.1. Metallic Pumps
8.5.2. Concrete Volute Pumps
8.6. Analysis, Insights and Forecast - by Operation
8.6.1. Electrical Driven
8.6.2. Hydraulic Driven
8.6.3. Air Driven
9. Volute Pump Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Pump Type
9.1.1. Single-Stage Volute Pumps
9.1.2. Multi-Stage Volute Pumps
9.2. Analysis, Insights and Forecast - by Discharge Direction
9.2.1. Horizontal Volute Pumps
9.2.2. Vertical Volute Pumps
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Water and Wastewater Treatment
9.3.2. Power Generation
9.3.3. Oil and Gas
9.3.4. Chemical Processing
9.3.5. Mining
9.3.6. Agriculture and Lift Irrigation
9.3.7. Building Services
9.3.8. Industrial Manufacturing
9.3.9. Others
9.4. Analysis, Insights and Forecast - by Flow Rate
9.4.1. Low Flow Rate Volute Pumps
9.4.2. Medium Flow Rate Volute Pumps
9.4.3. High Flow Rate Volute Pumps
9.5. Analysis, Insights and Forecast - by Construction
9.5.1. Metallic Pumps
9.5.2. Concrete Volute Pumps
9.6. Analysis, Insights and Forecast - by Operation
9.6.1. Electrical Driven
9.6.2. Hydraulic Driven
9.6.3. Air Driven
10. Volute Pump Market Middle East Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Pump Type
10.1.1. Single-Stage Volute Pumps
10.1.2. Multi-Stage Volute Pumps
10.2. Analysis, Insights and Forecast - by Discharge Direction
10.2.1. Horizontal Volute Pumps
10.2.2. Vertical Volute Pumps
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Water and Wastewater Treatment
10.3.2. Power Generation
10.3.3. Oil and Gas
10.3.4. Chemical Processing
10.3.5. Mining
10.3.6. Agriculture and Lift Irrigation
10.3.7. Building Services
10.3.8. Industrial Manufacturing
10.3.9. Others
10.4. Analysis, Insights and Forecast - by Flow Rate
10.4.1. Low Flow Rate Volute Pumps
10.4.2. Medium Flow Rate Volute Pumps
10.4.3. High Flow Rate Volute Pumps
10.5. Analysis, Insights and Forecast - by Construction
10.5.1. Metallic Pumps
10.5.2. Concrete Volute Pumps
10.6. Analysis, Insights and Forecast - by Operation
10.6.1. Electrical Driven
10.6.2. Hydraulic Driven
10.6.3. Air Driven
11. Volute Pump Market Africa Analysis, Insights and Forecast, 2020-2034
11.1. Analysis, Insights and Forecast - by Pump Type
11.1.1. Single-Stage Volute Pumps
11.1.2. Multi-Stage Volute Pumps
11.2. Analysis, Insights and Forecast - by Discharge Direction
11.2.1. Horizontal Volute Pumps
11.2.2. Vertical Volute Pumps
11.3. Analysis, Insights and Forecast - by Application
11.3.1. Water and Wastewater Treatment
11.3.2. Power Generation
11.3.3. Oil and Gas
11.3.4. Chemical Processing
11.3.5. Mining
11.3.6. Agriculture and Lift Irrigation
11.3.7. Building Services
11.3.8. Industrial Manufacturing
11.3.9. Others
11.4. Analysis, Insights and Forecast - by Flow Rate
11.4.1. Low Flow Rate Volute Pumps
11.4.2. Medium Flow Rate Volute Pumps
11.4.3. High Flow Rate Volute Pumps
11.5. Analysis, Insights and Forecast - by Construction
11.5.1. Metallic Pumps
11.5.2. Concrete Volute Pumps
11.6. Analysis, Insights and Forecast - by Operation
11.6.1. Electrical Driven
11.6.2. Hydraulic Driven
11.6.3. Air Driven
12. Volute Pump Market Competitive Analysis
12.1. Company Profiles
12.1.1. KSB SE & Co. KGaA
12.1.1.1. Company Overview
12.1.1.2. Products
12.1.1.3. Company Financials
12.1.1.4. SWOT Analysis
12.1.2. Flowserve Corporation
12.1.2.1. Company Overview
12.1.2.2. Products
12.1.2.3. Company Financials
12.1.2.4. SWOT Analysis
12.1.3. Sulzer Ltd
12.1.3.1. Company Overview
12.1.3.2. Products
12.1.3.3. Company Financials
12.1.3.4. SWOT Analysis
12.1.4. Xylem Inc.
12.1.4.1. Company Overview
12.1.4.2. Products
12.1.4.3. Company Financials
12.1.4.4. SWOT Analysis
12.1.5. Ebara Corporation
12.1.5.1. Company Overview
12.1.5.2. Products
12.1.5.3. Company Financials
12.1.5.4. SWOT Analysis
12.1.6. Pentair plc
12.1.6.1. Company Overview
12.1.6.2. Products
12.1.6.3. Company Financials
12.1.6.4. SWOT Analysis
12.1.7. Grundfos Holding A/S
12.1.7.1. Company Overview
12.1.7.2. Products
12.1.7.3. Company Financials
12.1.7.4. SWOT Analysis
12.1.8. Wilo SE
12.1.8.1. Company Overview
12.1.8.2. Products
12.1.8.3. Company Financials
12.1.8.4. SWOT Analysis
12.1.9. SPX Flow Inc.
12.1.9.1. Company Overview
13. Volute Pump Market Research Methodology
List of Figures
Figure 1: Volute Pump Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Volute Pump Market Revenue (Billion), by Pump Type 2026 & 2034
Figure 3: North America Volute Pump Market Revenue Share (%), by Pump Type 2026 & 2034
Figure 4: North America Volute Pump Market Revenue (Billion), by Discharge Direction 2026 & 2034
Figure 5: North America Volute Pump Market Revenue Share (%), by Discharge Direction 2026 & 2034
Figure 6: North America Volute Pump Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Volute Pump Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Volute Pump Market Revenue (Billion), by Flow Rate 2026 & 2034
Figure 9: North America Volute Pump Market Revenue Share (%), by Flow Rate 2026 & 2034
Figure 10: North America Volute Pump Market Revenue (Billion), by Construction 2026 & 2034
Figure 11: North America Volute Pump Market Revenue Share (%), by Construction 2026 & 2034
Figure 12: North America Volute Pump Market Revenue (Billion), by Operation 2026 & 2034
Figure 13: North America Volute Pump Market Revenue Share (%), by Operation 2026 & 2034
Figure 14: North America Volute Pump Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Volute Pump Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Volute Pump Market Revenue (Billion), by Pump Type 2026 & 2034
Europe Volute Pump Market Revenue Share (%), by Pump Type 2026 & 2034
List of Tables
Table 1: Volute Pump Market Revenue Billion Forecast, by Pump Type 2020 & 2034
Table 2: Volute Pump Market Revenue Billion Forecast, by Discharge Direction 2020 & 2034
1. What is the size of the global volute pump market in 2025?
Our proprietary primary research values the global volute pump market at USD 21.02 Billion in 2025, up from USD 20.23 Billion in 2024. The market is forecast to reach USD 30.79 Billion by 2035.
2. What is the CAGR of the volute pump market through 2035?
The volute pump market is projected to grow at a compound annual growth rate of 3.89% between 2025 and 2035. Growth is supported by water infrastructure spending, efficiency regulation and digital retrofit demand.
3. Which region holds the largest share of the volute pump market?
North America is the largest region by value, holding roughly 31% of global share, driven by municipal water treatment and industrial replacement demand. Asia-Pacific is the fastest-growing region at approximately 29% share, fuelled by urbanisation and large water and sanitation programmes.
4. Which volute pump type dominates and which is growing fastest?
Single-stage volute pumps dominate the market because of their simplicity, reliability and lower maintenance cost in moderate-pressure duty. Multi-stage volute pumps are the fastest-growing type, delivering 20–25% operational cost savings in high-pressure applications such as boiler feed and long-distance fluid transport.
5. Why is water and wastewater treatment the largest application for volute pumps?
Water and wastewater treatment is the largest application because roughly 48% of global wastewater is still discharged untreated, while treatment coverage sits near 70% in developed economies but falls to 28% in lower-middle-income countries. This gap requires large-scale pumping capacity for collection, transfer and treatment processes.
6. What is driving adoption of smart, IoT-enabled volute pumps?
Field deployments show IoT-enabled volute pumps reduce energy consumption by approximately 30% and maintenance costs by 26.5%, while predictive maintenance cuts unplanned downtime by up to 39%. Variable Frequency Drives add up to 40% energy savings in low-load conditions, making digital upgrades a rapid payback investment.
7. What are the main barriers to volute pump market growth?
High initial capital cost is the primary purchase barrier, particularly for small municipal and agricultural buyers. Because first cost represents less than 10% of lifetime cost while energy accounts for 60–80% of total ownership cost, buyers optimising for capex frequently under-invest in higher-efficiency volute pump solutions.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70–80% of the analytical input for this volute pump market study was derived from primary research, with the remaining 20–30% from secondary and official-source benchmarking.
We conducted 1,180+ structured interviews and surveys across 34 countries, covering the complete volute pump value chain rather than a single supply tier.
Primary research participant mix by company type included volute pump OEMs and pump packagers; component, casting and mechanical seal suppliers; EPC contractors and system integrators; authorised distributors and aftermarket service partners; and end-user operators in municipal water and industrial process plants.
Interviewed stakeholder designations included Procurement and Supply Chain Directors, Chief Engineers and Plant Operations Managers, Product and R&D Engineering Leads, and Sustainability and Regulatory Compliance Managers.
Corporate financial and deal intelligence was cross-referenced against Bloomberg, Factiva, Hoovers and PitchBook to validate revenue scale, segment disclosure, capital expenditure and M&A activity among listed and private pump manufacturers.
Technical and regulatory benchmarking referenced recognised standards and instruments, including ISO 9906 (rotodynamic pump acceptance testing), ISO 5199 (centrifugal pump technical requirements), Hydraulic Institute HI 14.6 and mandatory water pump ecodesign efficiency thresholds applicable in the European Union.
All secondary data was used strictly as a triangulation layer; every headline figure in this report is expressed as our own modelled estimate derived from primary inputs.
Demand Modeling & Market Estimation
A simultaneous top-down and bottom-up methodology was applied, with the two approaches reconciled through multi-level data triangulation before any figure was published.
Top-down anchor: global centrifugal pump market value multiplied by the modelled volute architecture share of 35–38% of centrifugal pump value.
Bottom-up build: the installed base of volute pumps by end-use sector was multiplied by annual replacement rate and average unit selling price, then added to greenfield demand calculated as new water and wastewater treatment capacity in megalitres per day multiplied by pump intensity per MLD.
Additional bottom-up quantitative metrics included industrial plant pump capacity measured in cubic metres per hour per process line, average unit price normalised per kilowatt of installed pumping power, aftermarket attach rate and service contract penetration, and mean time between overhaul to determine replacement timing.
Regional and country estimates were validated against official import and export values and against announced utility and industrial capital expenditure programmes.
Data Accuracy & Quality Check
Every report carries a guaranteed estimated data accuracy level of 85–90%, with stated confidence bands on all forward projections.
A three-stage validation protocol was applied: respondent-level sanity checking, cross-cohort variance testing, and independent triangulation against official trade statistics.
Outlier responses exceeding two standard deviations from cohort means were trimmed and, where relevant, re-verified through follow-up interviews.
Triangulation variance between the top-down and bottom-up models was held below plus or minus 3% before final figures were accepted.
All datasets are refreshed and updated to the date of purchase, so that forecasts, competitive developments and regulatory changes reflect the most current market position.
Chile
Middle East
Saudi Arabia
Turkey
UAE
Egypt
Qatar
Africa
East Africa
West Africa
North Africa
South Africa
12.1.9.2. Products
12.1.9.3. Company Financials
12.1.9.4. SWOT Analysis
12.1.10. Kirloskar Brothers
12.1.10.1. Company Overview
12.1.10.2. Products
12.1.10.3. Company Financials
12.1.10.4. SWOT Analysis
12.1.11. Kubota
12.1.11.1. Company Overview
12.1.11.2. Products
12.1.11.3. Company Financials
12.1.11.4. SWOT Analysis
12.1.12. Kaiquan Pump
12.1.12.1. Company Overview
12.1.12.2. Products
12.1.12.3. Company Financials
12.1.12.4. SWOT Analysis
12.1.13. Watson-Marlow
12.1.13.1. Company Overview
12.1.13.2. Products
12.1.13.3. Company Financials
12.1.13.4. SWOT Analysis
12.1.14. Gardner Denver
12.1.14.1. Company Overview
12.1.14.2. Products
12.1.14.3. Company Financials
12.1.14.4. SWOT Analysis
12.1.15. PSG Dover
12.1.15.1. Company Overview
12.1.15.2. Products
12.1.15.3. Company Financials
12.1.15.4. SWOT Analysis
12.2. Market Entropy
12.2.1. Company's Key Areas Served
12.2.2. Recent Developments
12.3. Company Market Share Analysis, 2026
12.3.1. Top 5 Companies Market Share Analysis
12.3.2. Top 3 Companies Market Share Analysis
12.4. List of Potential Customers
Figure 17:
Figure 18: Europe Volute Pump Market Revenue (Billion), by Discharge Direction 2026 & 2034
Figure 19: Europe Volute Pump Market Revenue Share (%), by Discharge Direction 2026 & 2034
Figure 20: Europe Volute Pump Market Revenue (Billion), by Application 2026 & 2034
Figure 21: Europe Volute Pump Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe Volute Pump Market Revenue (Billion), by Flow Rate 2026 & 2034
Figure 23: Europe Volute Pump Market Revenue Share (%), by Flow Rate 2026 & 2034
Figure 24: Europe Volute Pump Market Revenue (Billion), by Construction 2026 & 2034
Figure 25: Europe Volute Pump Market Revenue Share (%), by Construction 2026 & 2034
Figure 26: Europe Volute Pump Market Revenue (Billion), by Operation 2026 & 2034
Figure 27: Europe Volute Pump Market Revenue Share (%), by Operation 2026 & 2034
Figure 28: Europe Volute Pump Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Volute Pump Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific Volute Pump Market Revenue (Billion), by Pump Type 2026 & 2034
Figure 31: Asia Pacific Volute Pump Market Revenue Share (%), by Pump Type 2026 & 2034
Figure 32: Asia Pacific Volute Pump Market Revenue (Billion), by Discharge Direction 2026 & 2034
Figure 33: Asia Pacific Volute Pump Market Revenue Share (%), by Discharge Direction 2026 & 2034
Figure 34: Asia Pacific Volute Pump Market Revenue (Billion), by Application 2026 & 2034
Figure 35: Asia Pacific Volute Pump Market Revenue Share (%), by Application 2026 & 2034
Figure 36: Asia Pacific Volute Pump Market Revenue (Billion), by Flow Rate 2026 & 2034
Figure 37: Asia Pacific Volute Pump Market Revenue Share (%), by Flow Rate 2026 & 2034
Figure 38: Asia Pacific Volute Pump Market Revenue (Billion), by Construction 2026 & 2034
Figure 39: Asia Pacific Volute Pump Market Revenue Share (%), by Construction 2026 & 2034
Figure 40: Asia Pacific Volute Pump Market Revenue (Billion), by Operation 2026 & 2034
Figure 41: Asia Pacific Volute Pump Market Revenue Share (%), by Operation 2026 & 2034
Figure 42: Asia Pacific Volute Pump Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific Volute Pump Market Revenue Share (%), by Country 2026 & 2034
Figure 44: South America Volute Pump Market Revenue (Billion), by Pump Type 2026 & 2034
Figure 45: South America Volute Pump Market Revenue Share (%), by Pump Type 2026 & 2034
Figure 46: South America Volute Pump Market Revenue (Billion), by Discharge Direction 2026 & 2034
Figure 47: South America Volute Pump Market Revenue Share (%), by Discharge Direction 2026 & 2034
Figure 48: South America Volute Pump Market Revenue (Billion), by Application 2026 & 2034
Figure 49: South America Volute Pump Market Revenue Share (%), by Application 2026 & 2034
Figure 50: South America Volute Pump Market Revenue (Billion), by Flow Rate 2026 & 2034
Figure 51: South America Volute Pump Market Revenue Share (%), by Flow Rate 2026 & 2034
Figure 52: South America Volute Pump Market Revenue (Billion), by Construction 2026 & 2034
Figure 53: South America Volute Pump Market Revenue Share (%), by Construction 2026 & 2034
Figure 54: South America Volute Pump Market Revenue (Billion), by Operation 2026 & 2034
Figure 55: South America Volute Pump Market Revenue Share (%), by Operation 2026 & 2034
Figure 56: South America Volute Pump Market Revenue (Billion), by Country 2026 & 2034
Figure 57: South America Volute Pump Market Revenue Share (%), by Country 2026 & 2034
Figure 58: Middle East Volute Pump Market Revenue (Billion), by Pump Type 2026 & 2034
Figure 59: Middle East Volute Pump Market Revenue Share (%), by Pump Type 2026 & 2034
Figure 60: Middle East Volute Pump Market Revenue (Billion), by Discharge Direction 2026 & 2034
Figure 61: Middle East Volute Pump Market Revenue Share (%), by Discharge Direction 2026 & 2034
Figure 62: Middle East Volute Pump Market Revenue (Billion), by Application 2026 & 2034
Figure 63: Middle East Volute Pump Market Revenue Share (%), by Application 2026 & 2034
Figure 64: Middle East Volute Pump Market Revenue (Billion), by Flow Rate 2026 & 2034
Figure 65: Middle East Volute Pump Market Revenue Share (%), by Flow Rate 2026 & 2034
Figure 66: Middle East Volute Pump Market Revenue (Billion), by Construction 2026 & 2034
Figure 67: Middle East Volute Pump Market Revenue Share (%), by Construction 2026 & 2034
Figure 68: Middle East Volute Pump Market Revenue (Billion), by Operation 2026 & 2034
Figure 69: Middle East Volute Pump Market Revenue Share (%), by Operation 2026 & 2034
Figure 70: Middle East Volute Pump Market Revenue (Billion), by Country 2026 & 2034
Figure 71: Middle East Volute Pump Market Revenue Share (%), by Country 2026 & 2034
Figure 72: Africa Volute Pump Market Revenue (Billion), by Pump Type 2026 & 2034
Figure 73: Africa Volute Pump Market Revenue Share (%), by Pump Type 2026 & 2034
Figure 74: Africa Volute Pump Market Revenue (Billion), by Discharge Direction 2026 & 2034
Figure 75: Africa Volute Pump Market Revenue Share (%), by Discharge Direction 2026 & 2034
Figure 76: Africa Volute Pump Market Revenue (Billion), by Application 2026 & 2034
Figure 77: Africa Volute Pump Market Revenue Share (%), by Application 2026 & 2034
Figure 78: Africa Volute Pump Market Revenue (Billion), by Flow Rate 2026 & 2034
Figure 79: Africa Volute Pump Market Revenue Share (%), by Flow Rate 2026 & 2034
Figure 80: Africa Volute Pump Market Revenue (Billion), by Construction 2026 & 2034
Figure 81: Africa Volute Pump Market Revenue Share (%), by Construction 2026 & 2034
Figure 82: Africa Volute Pump Market Revenue (Billion), by Operation 2026 & 2034
Figure 83: Africa Volute Pump Market Revenue Share (%), by Operation 2026 & 2034
Figure 84: Africa Volute Pump Market Revenue (Billion), by Country 2026 & 2034
Figure 85: Africa Volute Pump Market Revenue Share (%), by Country 2026 & 2034
Table 17:
Table 18: Europe Volute Pump Market Revenue Billion Forecast, by Pump Type 2020 & 2034
Table 19: Europe Volute Pump Market Revenue Billion Forecast, by Discharge Direction 2020 & 2034
Table 20: Europe Volute Pump Market Revenue Billion Forecast, by Application 2020 & 2034
Table 21: Europe Volute Pump Market Revenue Billion Forecast, by Flow Rate 2020 & 2034
Table 22: Europe Volute Pump Market Revenue Billion Forecast, by Construction 2020 & 2034
Table 23: Europe Volute Pump Market Revenue Billion Forecast, by Operation 2020 & 2034
Table 24: Europe Volute Pump Market Revenue Billion Forecast, by Country 2020 & 2034


 Volute Pump Market