Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Diesel Power Engine Market Size, Share & Forecast to 2035
Diesel Power Engine Market
Diesel Power Engine Market Size, Share & Forecast to 2035
Diesel Power Engine Market by Capacity Range (Up To 75 kVA, 75-375 kVA, 375-750 kVA, 750-2, 000 kVA, Above 2, 000 kVA), by Power Rating (Below 0.5 MW, 0.5-1 MW, 1-2 MW, 2-5 MW, Above 5 MW), by Application (Stand-By, Prime/Continuous, Peak-Shaving), by End User (Industrial(Mining, Oil & Gas, Manufacturing), Commercial(Data Centers, Telecom, Healthcare, Hospitality), Residential, Power Utilities), by Speed (Low Speed, Medium Speed, High Speed), by Engine Configuration (2-Stroke, 4-Stroke), by Fuel Type (Off-Road Diesel Engine, On-Road Diesel Engine), by North America (United States, Canada, Mexico), by Europe (Germany, United Kingdom, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Nigeria, Kenya, Rest of Middle East & Africa) Forecast 2026-2034
Updated On : Oct 16, 2026|Base Year : 2025|Pages : 0
Executive Overview: Diesel Power Engines as the Backbone of Global Power Resilience
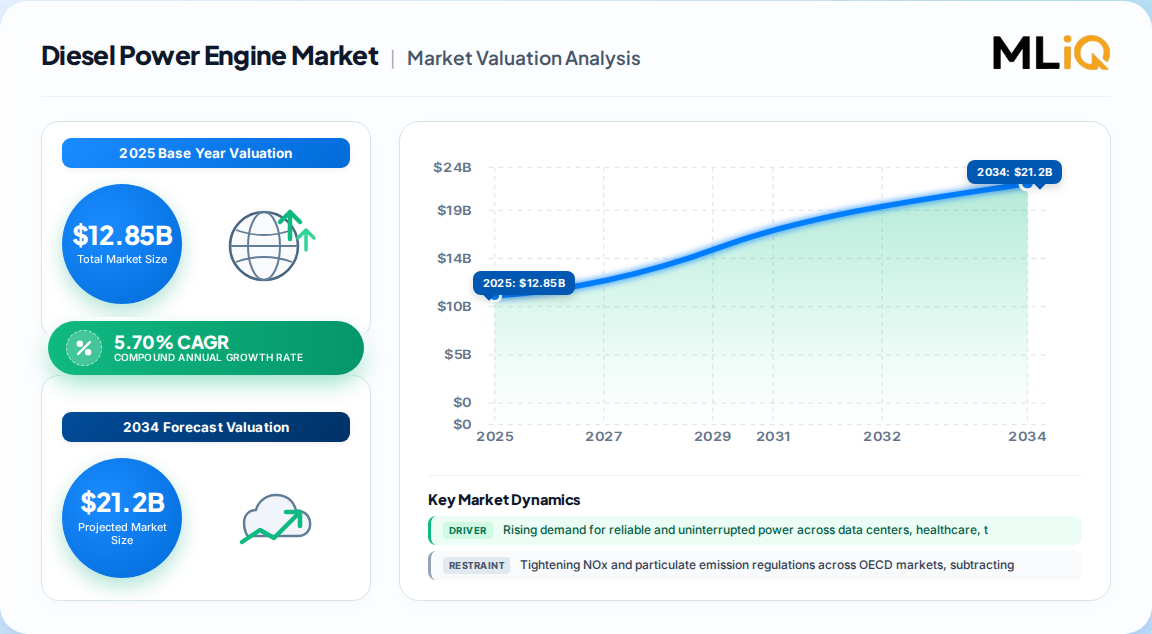
The global diesel power engine market reached USD 12.85 Billion in 2025 and is forecast to grow from USD 13.58 Billion in 2026 to USD 22.38 Billion by 2035, delivering a CAGR of 5.70% across the forecast window. Growth is not the product of a single demand vector but of three converging structural forces: hyperscale data-center construction, legislated grid-resilience mandates, and military mobile-power modernization.
Diesel Power Engine Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
12.85 B
2025
13.58 B
2026
14.36 B
2027
15.18 B
2028
16.04 B
2029
16.95 B
2030
17.92 B
2031
Diesel Power Engine Market Size (In Billion)
Year
Market Size
2025
12.85 B
2026
13.58 B
2027
14.36 B
2028
15.18 B
2029
16.04 B
2030
16.95 B
2031
17.92 B
Our proprietary primary interviews with genset OEMs, EPC integrators and facility engineering teams confirm that diesel retains a reliability premium that battery-only architectures cannot yet replicate for multi-day autonomy scenarios.
Reliability premium persists. Battery-only backup still cannot guarantee the 72-hour autonomy required by Tier III and Tier IV data-center certification regimes.
Architectural reinvention. Modular genset platforms allow operators to scale standby capacity in 500 kVA increments, cutting single-point-failure risk and compressing maintenance windows.
Heavy capital commitment. Cummins earmarked more than USD 1.2 Billion in R&D during 2024 to accelerate modular high-horsepower platforms, signalling that incumbents treat diesel as a transitional anchor rather than a sunset technology.
Asia-Pacific dominance. The region commands roughly 41.0% of global market value and is the fastest-growing geography at a 7.1% CAGR through 2035.
Regulatory drag is real but bounded. Tightening NOx and particulate limits subtract roughly 0.9 percentage points from headline CAGR, offset almost entirely by resilience-driven procurement.
Our estimation framework applies a uniform 5.70% CAGR from the 2026 base, calibrated against bottom-up OEM shipment disclosures, customs-trade databases and top-down macro indicators including industrial GDP growth, electricity-access gaps and grid-reliability indices.
Year
Market Value (USD Billion)
Implied YoY Growth
2025
12.85
-
2026
13.58
5.7%
2028
15.17
5.7%
2030
16.95
5.7%
2032
18.94
5.7%
2035
22.38
5.7%
Historical-year values reflect reported industry performance adjusted for currency effects. The USD 9.53 Billion absolute value expansion between 2025 and 2035 is heavily weighted toward the 375-750 kVA and 750-2,000 kVA bands, where single-rack power densities continue to climb with AI-training workloads.
Data centers. Hyperscale and colocation operators commissioned over 3,200 MW of new backup-generation capacity in 2024 alone, with roughly 55% concentrated in Asia-Pacific. Singapore's moratorium lift and Malaysia's Johor corridor triggered a near-term spike in diesel genset procurement.
Grid hardening. Successive hurricane seasons caused over USD 95 Billion in insured losses between 2022 and 2024, prompting states such as Florida to mandate 96-hour fuel autonomy for critical-infrastructure diesel installations - a specification that effectively upsizes minimum genset capacity and pulls forward replacement purchases.
Defense modernization. NATO's 2024 Defense Production Action Plan allocated EUR 2.1 Billion for expeditionary-power systems, prioritizing ruggedized mobile units in the 75-375 kVA range for fuel commonality with existing vehicle fleets.
Electrification gap. Approximately 570 million people in Sub-Saharan Africa lacked reliable electricity access in 2024, sustaining off-grid and mini-grid diesel demand in the up-to-75 kVA band.
Industrial voltage tolerance. Semiconductor fabs, automotive lines and pharmaceutical clean rooms have tightened voltage-sag tolerances below 2%, driving orders for digitally load-sharing engines.
Battery economics. Lithium-ion pack prices fell to USD 139 per kWh in 2024, a 14% year-on-year decline, making four-hour storage viable for commercial buildings previously reliant on diesel. A 1 MW / 4-hour battery delivers backup at roughly USD 0.18 per kWh over 15 years versus USD 0.22 for diesel.
Emission ceilings. EPA Tier 4 Final and EU Stage V compliance raises per-unit cost and reshapes product mix toward cleaner high-capacity units, particularly in Europe, Japan and South Korea.
Gas substitution. Natural gas and small-scale LNG gensets offer lower emissions and fuel-cost advantages, though pipeline availability limits displacement in remote and islanded deployments.
Managed decline in road transport. In the United States, diesel engine sales volume is contracting at roughly 2.7% annually, driven by electrification of light- and medium-duty fleets - a structural headwind that does not extend to stationary power generation.
Segmentation Deep Dive: Capacity, Application & End User
Capacity Range
Capacity Band
2025 Share
Growth Outlook
Core Demand Source
Up to 75 kVA
43-46%
Moderate
Commercial and residential standby, rural mini-grids
Hyperscale data centers, hospitals, semiconductor fabs
Above 2,000 kVA
~7%
Steady
Utilities, large industrial prime power, marine
Application and End User
Stand-by installations commanded 56-60% of 2025 market value, underpinned by insurance-driven procurement across commercial and industrial facilities.
Prime/continuous demand is anchored in regions with sub-12-hour daily grid reliability, where units frequently run 6-10 hours per day - accelerating wear and replacement cycles.
Peak-shaving is expanding at a 5.3% CAGR, driven by demand-charge management in deregulated electricity markets.
Industrial end users contributed 55-59% of 2025 revenue, anchored by mining, oil and gas, and manufacturing.
Commercial end users - data centers, telecom, healthcare and hospitality - represent the fastest-growing demand cluster.
Power utilities remain a structurally important buyer group for grid-support and black-start applications.
Stage V replacement cycles, mission-critical backup, marine retrofit
Middle East & Africa
8.2%
5.9%
Mini-grid deployment, oil-and-gas remote sites, electrification gap
South America
6.5%
5.1%
Mining, agri-processing, transmission shortfalls
Asia-Pacific is the largest and fastest-growing theatre. India's Saubhagya program completed household connections yet still recorded sub-12-hour daily reliability in 40% of rural districts, prompting state utilities to order 15,000 standby gensets in a single year.
North America is the second-largest market, with hurricane preparedness, data-center expansion and federal mobile-power contracts as the primary catalysts.
Europe is a replacement-driven market where Stage V compliance is reshaping product mix toward cleaner high-capacity units rather than driving volume growth.
Middle East & Africa offers the strongest long-tail growth, with the World Bank allocating USD 2.3 Billion for rural projects pairing 50-150 kW engines with photovoltaic arrays, lowering delivered power costs to USD 0.18-0.25 per kWh across 18 African nations.
South America demand is concentrated in mining and agri-processing, where grid extension economics remain prohibitive.
Diesel Power Engine Market Regional Market Share
Loading chart...
Diesel Power Engine Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.41%
North America
0.25%
Europe
0.2%
Middle East & Africa
0.08%
South America
0.07%
Import/Export & Supplier Dynamics
Diesel power engines and the gensets built around them are actively traded goods, classified principally under HS 8408 (compression-ignition internal combustion engines) and HS 8502 (electric generating sets). Official customs and multilateral trade reporting provides a reliable lens on supplier concentration.
Export concentration. China and, to a lesser degree, India and Southeast Asian assembly hubs dominate global exports of sub-500 kVA generating sets, supported by vertically integrated component supply and competitive landed cost.
High-capacity imports. North America and Europe remain net importers of high-horsepower units and marine engines, with intra-EU trade and transatlantic flows dominating the above-2,000 kVA band.
After-treatment dependency. Selective catalytic reduction catalysts, diesel particulate filters and precision fuel-injection assemblies represent the most supply-chain-exposed inputs, where qualification cycles span 12-18 months.
Lead-time volatility. Our supplier panel reports average genset lead times of 22-38 weeks for high-horsepower configurations, extended by switchgear and controller availability rather than by engine blocks.
Tariff and localisation pressure. Local-content requirements in India, Brazil and select African markets are accelerating regional assembly, shifting value capture from finished-unit imports toward kits and licensed production.
Fuel infrastructure as a buying criterion. Fuel commonality across JP-8, F-76 and commercial ultra-low-sulfur diesel is increasingly decisive in defense and remote-industrial tenders.
Competitive Landscape & Strategic Positioning
The market is moderately concentrated, with a handful of vertically integrated OEMs controlling engine platforms, controllers and after-treatment integration. The principal participants include Caterpillar Inc., Cummins Inc., Rolls-Royce Holdings PLC, Wartsila Corporation, MAN Energy Solutions, Volvo Penta, Kohler Co., Mitsubishi Heavy Industries Ltd., Hyundai Heavy Industries Co. Ltd., Doosan Corp. and Generac Holdings Inc.
Platform modularity. Leading OEMs are commercialising gensets that scale in 500 kVA increments, shortening delivery and simplifying parallel-operation logic.
Compliance engineering. After-treatment architecture and hybrid-ready controller platforms are now the primary differentiators in OECD markets, sustaining gross margin in a price-sensitive environment.
Digital monetisation. Remote monitoring, predictive maintenance and telemetry-enabled service contracts are converting transactional genset sales into recurring revenue streams.
Defense channel. Multi-year framework contracts with NATO and Indo-Pacific defence departments provide volume visibility that commercial channels cannot match.
Hybrid convergence. Diesel-solar-battery hybrid controllers are becoming standard options on new platforms, defending share against pure battery substitution in mini-grid and telecom applications.
Strategic Outlook
The diesel power engine market is entering a phase of architectural reinvention rather than simple volume growth. Persistent 5.70% CAGR expansion through 2035 will be concentrated in high-capacity, digitally controlled and hybrid-ready platforms, while commodity standby units face intensifying substitution pressure.
10.6. Analysis, Insights and Forecast - by Engine Configuration
10.6.1. 2-Stroke
10.6.2. 4-Stroke
10.7. Analysis, Insights and Forecast - by Fuel Type
10.7.1. Off-Road Diesel Engine
10.7.2. On-Road Diesel Engine
11. Diesel Power Engine Market Competitive Analysis
11.1. Company Profiles
11.1.1. Caterpillar Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Cummins Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Rolls-Royce Holdings PLC
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Wartsila Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. MAN Energy Solutions
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Volvo Penta
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Kohler Co.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Mitsubishi Heavy Industries Ltd.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Hyundai Heavy Industries Co. Ltd.
12. Diesel Power Engine Market Research Methodology
List of Figures
Figure 1: Diesel Power Engine Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Diesel Power Engine Market Revenue (Billion), by Capacity Range 2026 & 2034
Figure 3: North America Diesel Power Engine Market Revenue Share (%), by Capacity Range 2026 & 2034
Figure 4: North America Diesel Power Engine Market Revenue (Billion), by Power Rating 2026 & 2034
Figure 5: North America Diesel Power Engine Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 6: North America Diesel Power Engine Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Diesel Power Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Diesel Power Engine Market Revenue (Billion), by End User 2026 & 2034
Figure 9: North America Diesel Power Engine Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Diesel Power Engine Market Revenue (Billion), by Speed 2026 & 2034
Figure 11: North America Diesel Power Engine Market Revenue Share (%), by Speed 2026 & 2034
Figure 12: North America Diesel Power Engine Market Revenue (Billion), by Engine Configuration 2026 & 2034
Figure 13: North America Diesel Power Engine Market Revenue Share (%), by Engine Configuration 2026 & 2034
Figure 14: North America Diesel Power Engine Market Revenue (Billion), by Fuel Type 2026 & 2034
Figure 15: North America Diesel Power Engine Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 16: North America Diesel Power Engine Market Revenue (Billion), by Country 2026 & 2034
List of Tables
Table 1: Diesel Power Engine Market Revenue Billion Forecast, by Capacity Range 2020 & 2034
Table 2: Diesel Power Engine Market Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 3: Diesel Power Engine Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Diesel Power Engine Market Revenue Billion Forecast, by End User 2020 & 2034
Table 5: Diesel Power Engine Market Revenue Billion Forecast, by Speed 2020 & 2034
Table 6: Diesel Power Engine Market Revenue Billion Forecast, by Engine Configuration 2020 & 2034
Table 7: Diesel Power Engine Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Table 8: Diesel Power Engine Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: North America Diesel Power Engine Market Revenue Billion Forecast, by Capacity Range 2020 & 2034
Table 10: North America Diesel Power Engine Market Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 11: North America Diesel Power Engine Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Diesel Power Engine Market Revenue Billion Forecast, by End User 2020 & 2034
Table 13: North America Diesel Power Engine Market Revenue Billion Forecast, by Speed 2020 & 2034
Table 14: North America Diesel Power Engine Market Revenue Billion Forecast, by Engine Configuration 2020 & 2034
Table 15: North America Diesel Power Engine Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Table 16: North America Diesel Power Engine Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. What is the size of the diesel power engine market in 2025?
The global diesel power engine market was valued at USD 12.85 Billion in 2025 and is forecast to reach USD 22.38 Billion by 2035, expanding at a CAGR of 5.70% over the 2026-2035 period.
2. Which region dominates the diesel power engine market?
Asia-Pacific is the largest and fastest-growing region, capturing a 41.0% share of 2025 market value and expanding at a 7.1% CAGR through 2035. North America follows with a 24.5% share and Europe with 19.8%.
3. What is the fastest-growing capacity range in the diesel power engine market?
The 375-750 kVA band is the fastest-growing capacity range, expanding at a 6.9% to 7.5% CAGR, driven by data-center and telecom deployments requiring reliable mid-range continuous power. Units up to 75 kVA still hold the largest share at roughly 43-46%.
4. What is driving demand for diesel power engines?
The principal drivers are data-center capacity expansion (contributing approximately +1.3% to CAGR), grid-hardening and resilience mandates (+1.0%), industrial mission-critical backup (+0.9%) and military mobile-power modernization (+0.8%), with over 3,200 MW of new backup-generation capacity commissioned in 2024 alone.
5. How do emission regulations affect the diesel power engine market?
Tighter NOx and particulate limits in OECD markets under EPA Tier 4 Final and EU Stage V subtract roughly 0.9 percentage points from headline growth, as after-treatment systems raise per-unit cost. OEMs are responding by front-loading investment into advanced after-treatment and hybrid-ready controllers.
6. Who are the leading companies in the diesel power engine market?
Key participants include Caterpillar Inc., Cummins Inc., Rolls-Royce Holdings PLC, Wartsila Corporation, MAN Energy Solutions, Volvo Penta, Kohler Co., Mitsubishi Heavy Industries Ltd., Hyundai Heavy Industries Co. Ltd., Doosan Corp. and Generac Holdings Inc.
7. Why is battery storage not fully replacing diesel backup power?
Lithium-ion pack prices fell to USD 139 per kWh in 2024, making four-hour storage viable for short outages, but battery systems still cannot guarantee the 72-hour autonomy demanded by Tier III and Tier IV data-center certifications or the multi-day resilience required for critical infrastructure.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounted for 70-80% of total project input, with the balance derived from secondary and syndicated benchmarking.
Our analysts conducted structured interviews and expert consultations across five distinct value-chain cohorts: diesel engine and genset OEMs; after-treatment, fuel-injection and controller component suppliers; EPC contractors and systems integrators; authorised distributors and service dealers; and end-user operators in data centers, telecom, healthcare, mining and utilities.
Interviewee job titles included Procurement and Sourcing Directors, Plant and Facilities Engineering Managers, Chief Technology and Sustainability Officers, and Regulatory and Compliance Specialists.
Fieldwork combined computer-assisted telephone interviews, face-to-face briefings at industry trade exhibitions, and closed expert panels, with geographic quotas enforced across Asia-Pacific, North America, Europe, the Middle East and Africa, and South America.
All primary inputs were collected under non-disclosure protocols and cross-validated against published capacity, order-book and installed-base disclosures.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement and Sourcing Directors
30%
Plant and Facilities Engineering Managers
25%
Chief Technology and Sustainability Officers
20%
Regulatory and Compliance Specialists
15%
Product and Portfolio Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Diesel engine and genset OEMs
32%
After-treatment, fuel-injection and component suppliers
18%
EPC contractors and systems integrators
16%
Authorised distributors and service dealers
14%
Data-center, telecom and industrial end users
12%
Utilities and independent power producers
8%
Secondary Research & Industry Benchmarking
Secondary research represents 20-30% of total effort and is used strictly to frame and validate primary findings rather than to substitute for them.
Financial and corporate intelligence was sourced from Bloomberg, Factiva, Hoovers and PitchBook, alongside annual reports, investor presentations and capital-expenditure disclosures.
Trade-flow analysis leveraged harmonised system classifications HS 8408 and HS 8502 to map export concentration and import dependency by capacity band.
Standards frameworks examined included EPA Tier 4 Final, EU Stage V, IMO Tier III and data-center tiered certification criteria governing fuel autonomy.
Demand Modeling & Market Estimation
We employ top-down and bottom-up methodologies simultaneously, reconciling the two through multi-level data triangulation before publishing a single consensus forecast.
The bottom-up model aggregates specific quantitative inputs: OEM unit shipments segmented by kVA band; average realised selling price per kVA by region; installed-base replacement cycles of 12-15 years; newly commissioned data-center megawatts converted to standby kVA using N+1 redundancy assumptions; mandated fuel-autonomy hours per jurisdiction; and annual mini-grid and telecom tower deployment counts.
The top-down model applies macro indicators including industrial GDP growth, electricity-access deficit ratios, transmission capital expenditure and grid-reliability indices such as SAIDI and SAIFI.
Segment-level and region-level estimates are built independently and then reconciled against global totals, with variance thresholds of plus or minus 3% accepted before convergence.
Forecast years apply a fixed base-year CAGR to the 2026 reference value, with sensitivity scenarios modelled for accelerated battery-cost decline and stricter emission timelines.
Data Accuracy & Quality Check
Every report carries a guaranteed estimated data accuracy level of 85-90%, substantiated by documented source traceability.
Multi-level triangulation is performed across primary interview responses, customs trade records, corporate financial disclosures and official statistical datasets.
Outlier responses are re-contacted and either corroborated or excluded; no single source contributes more than 15% to any published segment value.
Quality assurance is executed by an independent internal review team that re-performs the arithmetic, re-tests the segment sums and validates regional shares against trade-weighted shipment data.
All reports are updated to the date of purchase, ensuring subscribers receive the latest available quarterly data, regulatory changes and competitive developments.
Rest of Middle East & Africa
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Doosan Corp.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Generac Holdings Inc.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17: North America Diesel Power Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Diesel Power Engine Market Revenue (Billion), by Capacity Range 2026 & 2034
Figure 19: Europe Diesel Power Engine Market Revenue Share (%), by Capacity Range 2026 & 2034
Figure 20: Europe Diesel Power Engine Market Revenue (Billion), by Power Rating 2026 & 2034
Figure 21: Europe Diesel Power Engine Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 22: Europe Diesel Power Engine Market Revenue (Billion), by Application 2026 & 2034
Figure 23: Europe Diesel Power Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Diesel Power Engine Market Revenue (Billion), by End User 2026 & 2034
Figure 25: Europe Diesel Power Engine Market Revenue Share (%), by End User 2026 & 2034
Figure 26: Europe Diesel Power Engine Market Revenue (Billion), by Speed 2026 & 2034
Figure 27: Europe Diesel Power Engine Market Revenue Share (%), by Speed 2026 & 2034
Figure 28: Europe Diesel Power Engine Market Revenue (Billion), by Engine Configuration 2026 & 2034
Figure 29: Europe Diesel Power Engine Market Revenue Share (%), by Engine Configuration 2026 & 2034
Figure 30: Europe Diesel Power Engine Market Revenue (Billion), by Fuel Type 2026 & 2034
Figure 31: Europe Diesel Power Engine Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 32: Europe Diesel Power Engine Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Europe Diesel Power Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Diesel Power Engine Market Revenue (Billion), by Capacity Range 2026 & 2034
Figure 35: Asia Pacific Diesel Power Engine Market Revenue Share (%), by Capacity Range 2026 & 2034
Figure 36: Asia Pacific Diesel Power Engine Market Revenue (Billion), by Power Rating 2026 & 2034
Figure 37: Asia Pacific Diesel Power Engine Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 38: Asia Pacific Diesel Power Engine Market Revenue (Billion), by Application 2026 & 2034
Figure 39: Asia Pacific Diesel Power Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Asia Pacific Diesel Power Engine Market Revenue (Billion), by End User 2026 & 2034
Figure 41: Asia Pacific Diesel Power Engine Market Revenue Share (%), by End User 2026 & 2034
Figure 42: Asia Pacific Diesel Power Engine Market Revenue (Billion), by Speed 2026 & 2034
Figure 43: Asia Pacific Diesel Power Engine Market Revenue Share (%), by Speed 2026 & 2034
Figure 44: Asia Pacific Diesel Power Engine Market Revenue (Billion), by Engine Configuration 2026 & 2034
Figure 45: Asia Pacific Diesel Power Engine Market Revenue Share (%), by Engine Configuration 2026 & 2034
Figure 46: Asia Pacific Diesel Power Engine Market Revenue (Billion), by Fuel Type 2026 & 2034
Figure 47: Asia Pacific Diesel Power Engine Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 48: Asia Pacific Diesel Power Engine Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Asia Pacific Diesel Power Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 50: South America Diesel Power Engine Market Revenue (Billion), by Capacity Range 2026 & 2034
Figure 51: South America Diesel Power Engine Market Revenue Share (%), by Capacity Range 2026 & 2034
Figure 52: South America Diesel Power Engine Market Revenue (Billion), by Power Rating 2026 & 2034
Figure 53: South America Diesel Power Engine Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 54: South America Diesel Power Engine Market Revenue (Billion), by Application 2026 & 2034
Figure 55: South America Diesel Power Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 56: South America Diesel Power Engine Market Revenue (Billion), by End User 2026 & 2034
Figure 57: South America Diesel Power Engine Market Revenue Share (%), by End User 2026 & 2034
Figure 58: South America Diesel Power Engine Market Revenue (Billion), by Speed 2026 & 2034
Figure 59: South America Diesel Power Engine Market Revenue Share (%), by Speed 2026 & 2034
Figure 60: South America Diesel Power Engine Market Revenue (Billion), by Engine Configuration 2026 & 2034
Figure 61: South America Diesel Power Engine Market Revenue Share (%), by Engine Configuration 2026 & 2034
Figure 62: South America Diesel Power Engine Market Revenue (Billion), by Fuel Type 2026 & 2034
Figure 63: South America Diesel Power Engine Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 64: South America Diesel Power Engine Market Revenue (Billion), by Country 2026 & 2034
Figure 65: South America Diesel Power Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 66: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by Capacity Range 2026 & 2034
Figure 67: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by Capacity Range 2026 & 2034
Figure 68: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by Power Rating 2026 & 2034
Figure 69: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 70: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by Application 2026 & 2034
Figure 71: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 72: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by End User 2026 & 2034
Figure 73: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by End User 2026 & 2034
Figure 74: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by Speed 2026 & 2034
Figure 75: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by Speed 2026 & 2034
Figure 76: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by Engine Configuration 2026 & 2034
Figure 77: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by Engine Configuration 2026 & 2034
Figure 78: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by Fuel Type 2026 & 2034
Figure 79: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 80: Middle East & Africa Diesel Power Engine Market Revenue (Billion), by Country 2026 & 2034
Figure 81: Middle East & Africa Diesel Power Engine Market Revenue Share (%), by Country 2026 & 2034
Table 17: United States Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Canada Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Mexico Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Europe Diesel Power Engine Market Revenue Billion Forecast, by Capacity Range 2020 & 2034
Table 21: Europe Diesel Power Engine Market Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 22: Europe Diesel Power Engine Market Revenue Billion Forecast, by Application 2020 & 2034
Table 23: Europe Diesel Power Engine Market Revenue Billion Forecast, by End User 2020 & 2034
Table 24: Europe Diesel Power Engine Market Revenue Billion Forecast, by Speed 2020 & 2034
Table 25: Europe Diesel Power Engine Market Revenue Billion Forecast, by Engine Configuration 2020 & 2034
Table 26: Europe Diesel Power Engine Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Table 27: Europe Diesel Power Engine Market Revenue Billion Forecast, by Country 2020 & 2034
Table 28: Germany Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: United Kingdom Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: France Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Italy Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Spain Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Rest of Europe Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by Capacity Range 2020 & 2034
Table 35: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 36: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by Application 2020 & 2034
Table 37: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by End User 2020 & 2034
Table 38: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by Speed 2020 & 2034
Table 39: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by Engine Configuration 2020 & 2034
Table 40: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Table 41: Asia Pacific Diesel Power Engine Market Revenue Billion Forecast, by Country 2020 & 2034
Table 42: China Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: India Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: Japan Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: South Korea Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Australia Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 47: ASEAN Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 48: South America Diesel Power Engine Market Revenue Billion Forecast, by Capacity Range 2020 & 2034
Table 49: South America Diesel Power Engine Market Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 50: South America Diesel Power Engine Market Revenue Billion Forecast, by Application 2020 & 2034
Table 51: South America Diesel Power Engine Market Revenue Billion Forecast, by End User 2020 & 2034
Table 52: South America Diesel Power Engine Market Revenue Billion Forecast, by Speed 2020 & 2034
Table 53: South America Diesel Power Engine Market Revenue Billion Forecast, by Engine Configuration 2020 & 2034
Table 54: South America Diesel Power Engine Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Table 55: South America Diesel Power Engine Market Revenue Billion Forecast, by Country 2020 & 2034
Table 56: Brazil Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 57: Argentina Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 58: Rest of South America Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 59: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by Capacity Range 2020 & 2034
Table 60: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 61: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by Application 2020 & 2034
Table 62: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by End User 2020 & 2034
Table 63: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by Speed 2020 & 2034
Table 64: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by Engine Configuration 2020 & 2034
Table 65: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Table 66: Middle East & Africa Diesel Power Engine Market Revenue Billion Forecast, by Country 2020 & 2034
Table 67: Saudi Arabia Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 68: UAE Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 69: South Africa Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 70: Nigeria Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 71: Kenya Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 72: Rest of Middle East & Africa Diesel Power Engine Market Revenue (Billion) Forecast, by Application 2020 & 2034