Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Floating Storage Regasification Unit Market | 2025-2035
Floating Storage Regasification Unit Market
Floating Storage Regasification Unit Market | 2025-2035
Floating Storage Regasification Unit Market by Construction (Newly Built, Converted), by Storage Capacity (Small, Medium, Large), by End User (Power Generation, Industrial, Others), by Platform (Inshore Terminal, Offshore Terminal), by Design (Carrier Vessel-Based, Barge-Based), by North America (USA, Canada, Mexico), by Europe (Germany, Italy, France, UK), by Asia Pacific (China, India, Japan, South Korea), by Middle East & Africa (Saudi Arabia, Qatar, UAE), by South America (Brazil, Argentina) Forecast 2026-2034
Updated On : Oct 16, 2026|Base Year : 2025|Pages : 0
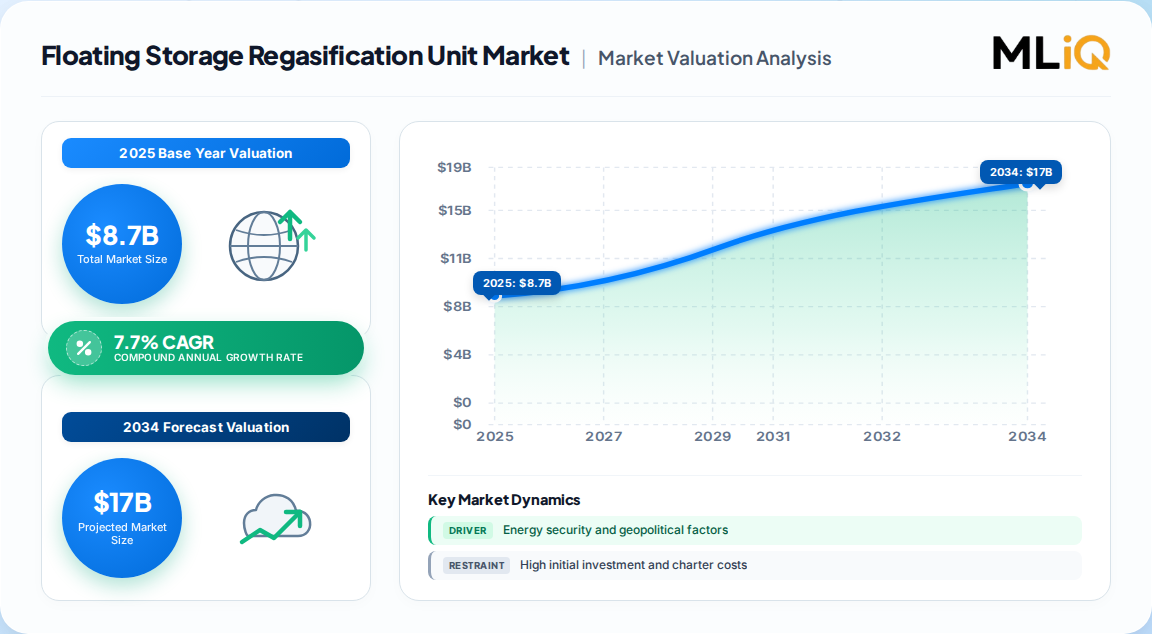
The global Floating Storage Regasification Unit (FSRU) market represents a pivotal segment of the LNG infrastructure landscape. In 2025, the market was valued at USD 8.7 Billion, and it is projected to reach USD 18.3 Billion by 2035, expanding at a CAGR of 7.7% during the forecast period. This growth is underpinned by the accelerating global demand for LNG as a transitional fuel, the need for rapid deployment of regasification capacity, and the strategic imperative for energy security diversification.
Floating Storage Regasification Unit Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.700 B
2025
9.370 B
2026
10.09 B
2027
10.87 B
2028
11.71 B
2029
12.61 B
2030
13.58 B
2031
Floating Storage Regasification Unit Market Size (In Billion)
Year
Market Size
2025
8.700 B
2026
9.370 B
2027
10.09 B
2028
10.87 B
2029
11.71 B
2030
12.61 B
2031
13.58 B
FSRUs serve as floating terminals that receive, store, and regasify LNG for injection into onshore gas grids or direct industrial use. Their modular, mobile nature allows for deployment in under 24 months, compared to multi-year timelines for onshore terminals, making them indispensable for emerging economies and import-dependent regions.
Market Size (2025): USD 8.7 Billion
Forecast (2035): USD 18.3 Billion
CAGR (2025-2035): 7.7%
Largest Region: Asia-Pacific
Fastest-Growing Segment (Construction): Converted
Largest End-User: Power Generation
Market Drivers & Restraints
Key Drivers
Energy Security & Geopolitical Factors: Nations are prioritizing energy independence, with FSRUs enabling diversified LNG sourcing. The EU's REPowerEU plan and the joint EU-US Task Force on Energy Security underscore the strategic role of FSRUs in displacing pipeline gas. The joint statement committed to securing at least 15 bcm of additional LNG for Europe in 2022.
Rising Demand for Clean Energy: LNG emits significantly less CO2 and pollutants than coal and oil, positioning it as a transition fuel. Global LNG trade exceeded 397 million tons in 2022, according to Shell's LNG Outlook, with FSRUs capturing a growing share of regasification capacity.
Infrastructure Cost & Time Advantages: FSRUs require lower capital expenditure and shorter lead times than onshore terminals. Over 80% of new regasification projects in import-dependent regions now favor FSRUs.
Technological Advancements: Innovations in regasification efficiency, closed-loop systems, and digital monitoring are enhancing operational performance and environmental compliance.
Market Restraints
High Initial Investment: The cost of new-build FSRUs remains substantial, ranging from $250-300 million, with conversions costing $100-150 million.
Vessel Scarcity: New-build shipyard slots are booked up to four years in advance, constraining rapid capacity additions.
Safety and Environmental Concerns: Offshore LNG storage poses risks of spills and explosions, necessitating advanced safety systems and stringent regulatory oversight.
Market Segmentation Analysis
The FSRU market is segmented by construction type, storage capacity, end-user, platform, and design.
Segment
Sub-Segment
Market Position
Key Insights
Construction
Newly Built
Largest Share
Preferred for long-term projects; operational lifespan >25 years
Converted
Fastest-Growing
Cost-effective, deployment up to 50% faster
Storage Capacity
Large (>5 MTPA)
Largest Share
Dominates high-volume import terminals
Medium (1-5 MTPA)
Fastest-Growing
Increasing demand from mid-sized markets
Small (<1 MTPA)
Emerging
Viable for island nations and remote areas
End-User
Power Generation
Largest Share (>72%)
Baseload and peak-shaving power, complementing renewables
Industrial
Second Largest
Feedstock and thermal processes; growing at ~15% slower than power
Others
Niche
Includes heating, cooling, and bunkering
Platform
Inshore Terminal
Dominant
Proximity to ports and established distribution
Offshore Terminal
Fastest-Growing
Deepwater configurations avoid port congestion
Design
Carrier Vessel-Based
Dominant
Large-scale LNG transport
Barge-Based
Fastest-Growing
Modular, small-scale regional importing
Regional Outlook & Growth Opportunities
Asia-Pacific is the epicenter of FSRU market growth, contributing 47.3% of incremental demand, expanding at 12.3% CAGR. China, India, and Japan are leading the coal-to-gas transition, with China focusing on high-capacity vessels for coastal manufacturing hubs.
Floating Storage Regasification Unit Market Regional Market Share
Loading chart...
Floating Storage Regasification Unit Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.45%
North America
0.25%
Europe
0.15%
Middle East & Africa
0.1%
South America
0.05%
Europe is rapidly deploying FSRUs to replace Russian pipeline gas, with Germany and Italy at the forefront. The region's focus on energy security has led to a surge in FSRU charters and terminal projects.
North America remains a mature market, with the U.S. leveraging its shale gas advantage to export LNG and develop FSRU-based import solutions. The region is projected to hold 36.1% revenue share by 2036.
The Middle East & Africa and Latin America are emerging hotspots, driven by new import terminals and energy diversification. Countries like Saudi Arabia, Qatar, Brazil, and Argentina are investing in FSRU infrastructure.
Competitive Landscape & Key Player Strategies
The FSRU market is characterized by a specialized and competitive landscape, dominated by leading vessel operators and engineering firms. Key players include:
Excelerate Energy (US)
Golar LNG (Norway)
Höegh LNG (Norway)
BW LPG Limited (Bermuda)
Exmar NV (Belgium)
FLEX LNG Management AS (Norway)
Mitsui & Co., Ltd. (Japan)
MOL Group (Hungary)
Qatargas (Qatar)
Shell (UK)
TotalEnergies (France)
Strategies focus on fleet expansion, long-term charters, and technological differentiation. Companies are investing in dual-fuel and low-emission FSRUs, and pursuing partnerships with national utilities to secure project pipelines.
Shipbuilding & Conversion: Shipyards in South Korea (Hyundai Heavy Industries, Samsung Heavy Industries), China (CSSC), and Singapore.
Operation & Leasing: FSRU owners/operators (Excelerate, Golar, Höegh) charter units to utilities.
LNG Supply & Trading: Oil majors (Shell, TotalEnergies) and national oil companies (Qatargas) supply LNG.
Port & Terminal Infrastructure: Port authorities, terminal operators, and pipeline networks.
Supply chain risks include shipyard capacity constraints, volatile steel prices, and geopolitical disruptions affecting LNG trade routes. The International Group of Liquefied Natural Gas Importers (GIIGNL) reported total regasification capacity of 1,143 MTPA in 2023, with floating units accounting for approximately 20%.
Recent Developments & Strategic Implications
2022: EU and US established a Task Force on Energy Security, aiming to secure 15 bcm of additional LNG for Europe, with FSRUs playing a critical role.
2022: Global LNG trade reached 397 million tons, a 16 million ton increase from 2021, per Shell.
2023: Total regasification capacity reached 1,143 MTPA, with floating units accounting for ~20%.
2024: FSRU Summit reported 49 FSRUs in operation, with 70 vessels ≤30,000 cubic meters (including LNGBVs and small-scale carriers).
2025: New-build FSRU orders surged, but shipyard slots are booked through 2029, creating a seller's market for available units.
Future Outlook & Strategic Recommendations
The FSRU market is poised for robust growth, driven by energy transition policies and the need for flexible LNG import capacity. Key strategic imperatives:
Diversify Supply Chains: Invest in multi-sourced LNG and flexible charter agreements.
Accelerate Technology Adoption: Deploy closed-loop regasification and digital twin monitoring.
Target High-Growth Regions: Asia-Pacific, Europe, and Latin America offer lucrative opportunities.
Secure Shipyard Capacity: Early booking and partnerships with shipyards are critical.
Engage in Policy Advocacy: Support regulatory frameworks that streamline FSRU permitting and deployment.
Floating Storage Regasification Unit Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Floating Storage Regasification Unit Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.7% from 2020-2034
Segmentation
By Construction
Newly Built
Converted
By Storage Capacity
Small
Medium
Large
By End User
Power Generation
Industrial
Others
By Platform
Inshore Terminal
Offshore Terminal
By Design
Carrier Vessel-Based
Barge-Based
By Geography
North America
USA
Canada
Mexico
Europe
Germany
Italy
France
UK
Asia Pacific
China
India
Japan
South Korea
Middle East & Africa
Saudi Arabia
Qatar
UAE
South America
Brazil
Argentina
Table of Contents
1. Floating Storage Regasification Unit Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Floating Storage Regasification Unit Market Executive Summary
2.1. Market Snapshot
3. Floating Storage Regasification Unit Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Floating Storage Regasification Unit Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Floating Storage Regasification Unit Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Construction
5.1.1. Newly Built
5.1.2. Converted
5.2. Analysis, Insights and Forecast - by Storage Capacity
5.2.1. Small
5.2.2. Medium
5.2.3. Large
5.3. Analysis, Insights and Forecast - by End User
5.3.1. Power Generation
5.3.2. Industrial
5.3.3. Others
5.4. Analysis, Insights and Forecast - by Platform
5.4.1. Inshore Terminal
5.4.2. Offshore Terminal
5.5. Analysis, Insights and Forecast - by Design
5.5.1. Carrier Vessel-Based
5.5.2. Barge-Based
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Middle East & Africa
5.6.5. South America
6. Floating Storage Regasification Unit Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Construction
6.1.1. Newly Built
6.1.2. Converted
6.2. Analysis, Insights and Forecast - by Storage Capacity
6.2.1. Small
6.2.2. Medium
6.2.3. Large
6.3. Analysis, Insights and Forecast - by End User
6.3.1. Power Generation
6.3.2. Industrial
6.3.3. Others
6.4. Analysis, Insights and Forecast - by Platform
6.4.1. Inshore Terminal
6.4.2. Offshore Terminal
6.5. Analysis, Insights and Forecast - by Design
6.5.1. Carrier Vessel-Based
6.5.2. Barge-Based
7. Floating Storage Regasification Unit Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Construction
7.1.1. Newly Built
7.1.2. Converted
7.2. Analysis, Insights and Forecast - by Storage Capacity
7.2.1. Small
7.2.2. Medium
7.2.3. Large
7.3. Analysis, Insights and Forecast - by End User
7.3.1. Power Generation
7.3.2. Industrial
7.3.3. Others
7.4. Analysis, Insights and Forecast - by Platform
7.4.1. Inshore Terminal
7.4.2. Offshore Terminal
7.5. Analysis, Insights and Forecast - by Design
7.5.1. Carrier Vessel-Based
7.5.2. Barge-Based
8. Floating Storage Regasification Unit Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Construction
8.1.1. Newly Built
8.1.2. Converted
8.2. Analysis, Insights and Forecast - by Storage Capacity
8.2.1. Small
8.2.2. Medium
8.2.3. Large
8.3. Analysis, Insights and Forecast - by End User
8.3.1. Power Generation
8.3.2. Industrial
8.3.3. Others
8.4. Analysis, Insights and Forecast - by Platform
8.4.1. Inshore Terminal
8.4.2. Offshore Terminal
8.5. Analysis, Insights and Forecast - by Design
8.5.1. Carrier Vessel-Based
8.5.2. Barge-Based
9. Floating Storage Regasification Unit Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Construction
9.1.1. Newly Built
9.1.2. Converted
9.2. Analysis, Insights and Forecast - by Storage Capacity
9.2.1. Small
9.2.2. Medium
9.2.3. Large
9.3. Analysis, Insights and Forecast - by End User
9.3.1. Power Generation
9.3.2. Industrial
9.3.3. Others
9.4. Analysis, Insights and Forecast - by Platform
9.4.1. Inshore Terminal
9.4.2. Offshore Terminal
9.5. Analysis, Insights and Forecast - by Design
9.5.1. Carrier Vessel-Based
9.5.2. Barge-Based
10. Floating Storage Regasification Unit Market South America Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Construction
10.1.1. Newly Built
10.1.2. Converted
10.2. Analysis, Insights and Forecast - by Storage Capacity
10.2.1. Small
10.2.2. Medium
10.2.3. Large
10.3. Analysis, Insights and Forecast - by End User
10.3.1. Power Generation
10.3.2. Industrial
10.3.3. Others
10.4. Analysis, Insights and Forecast - by Platform
10.4.1. Inshore Terminal
10.4.2. Offshore Terminal
10.5. Analysis, Insights and Forecast - by Design
10.5.1. Carrier Vessel-Based
10.5.2. Barge-Based
11. Floating Storage Regasification Unit Market Competitive Analysis
11.1. Company Profiles
11.1.1. Excelerate Energy
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Golar LNG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Höegh LNG
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. BW LPG Limited
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Exmar NV
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. FLEX LNG Management AS
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Mitsui & Co. Ltd.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. MOL Group
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Qatargas
11.1.9.1. Company Overview
12. Floating Storage Regasification Unit Market Research Methodology
List of Figures
Figure 1: Floating Storage Regasification Unit Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Floating Storage Regasification Unit Market Revenue (Billion), by Construction 2026 & 2034
Figure 3: North America Floating Storage Regasification Unit Market Revenue Share (%), by Construction 2026 & 2034
Figure 4: North America Floating Storage Regasification Unit Market Revenue (Billion), by Storage Capacity 2026 & 2034
Figure 5: North America Floating Storage Regasification Unit Market Revenue Share (%), by Storage Capacity 2026 & 2034
Figure 6: North America Floating Storage Regasification Unit Market Revenue (Billion), by End User 2026 & 2034
Figure 7: North America Floating Storage Regasification Unit Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Floating Storage Regasification Unit Market Revenue (Billion), by Platform 2026 & 2034
Figure 9: North America Floating Storage Regasification Unit Market Revenue Share (%), by Platform 2026 & 2034
Figure 10: North America Floating Storage Regasification Unit Market Revenue (Billion), by Design 2026 & 2034
Figure 11: North America Floating Storage Regasification Unit Market Revenue Share (%), by Design 2026 & 2034
Figure 12: North America Floating Storage Regasification Unit Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Floating Storage Regasification Unit Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Floating Storage Regasification Unit Market Revenue (Billion), by Construction 2026 & 2034
Figure 15: Europe Floating Storage Regasification Unit Market Revenue Share (%), by Construction 2026 & 2034
List of Tables
Table 1: Floating Storage Regasification Unit Market Revenue Billion Forecast, by Construction 2020 & 2034
Table 2: Floating Storage Regasification Unit Market Revenue Billion Forecast, by Storage Capacity 2020 & 2034
Table 3: Floating Storage Regasification Unit Market Revenue Billion Forecast, by End User 2020 & 2034
Table 4: Floating Storage Regasification Unit Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 5: Floating Storage Regasification Unit Market Revenue Billion Forecast, by Design 2020 & 2034
Table 6: Floating Storage Regasification Unit Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Floating Storage Regasification Unit Market Revenue Billion Forecast, by Construction 2020 & 2034
Table 8: North America Floating Storage Regasification Unit Market Revenue Billion Forecast, by Storage Capacity 2020 & 2034
Table 9: North America Floating Storage Regasification Unit Market Revenue Billion Forecast, by End User 2020 & 2034
Table 10: North America Floating Storage Regasification Unit Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 11: North America Floating Storage Regasification Unit Market Revenue Billion Forecast, by Design 2020 & 2034
Table 12: North America Floating Storage Regasification Unit Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Floating Storage Regasification Unit Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Floating Storage Regasification Unit Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Floating Storage Regasification Unit Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the market size of the Floating Storage Regasification Unit (FSRU) market?
The global FSRU market was valued at USD 8.7 Billion in 2025 and is projected to reach USD 18.3 Billion by 2035, growing at a CAGR of 7.7% during the forecast period.
2. Which region dominates the FSRU market?
Asia-Pacific dominates the FSRU market, contributing over 47% of incremental growth, driven by industrialization and coal-to-gas transition in China and India.
3. What are the key drivers of the FSRU market?
Key drivers include energy security, rising demand for clean energy, cost and time advantages over onshore terminals, and technological advancements. Over 80% of new regasification projects favor FSRUs.
4. What are the challenges faced by the FSRU market?
Challenges include high initial investment, vessel scarcity with shipyard slots booked four years in advance, safety concerns, and regulatory hurdles.
5. Who are the major players in the FSRU market?
Major players include Excelerate Energy, Golar LNG, Höegh LNG, BW LPG, Exmar, FLEX LNG, Mitsui & Co., MOL Group, Qatargas, Shell, and TotalEnergies.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of data is gathered through primary research, including in-depth interviews with FSRU owners/operators, shipyard executives, LNG traders, and port authorities.
We conduct 200+ interviews annually across the value chain, covering roles such as Procurement Director, Project Manager, Senior Engineer, and Business Development Manager.
Primary research includes surveys, expert calls, and on-site visits to FSRU terminals and shipyards.
Data is validated through triangulation with secondary sources.
 Floating Storage Regasification Unit Market