Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Shunt Reactor Market Size, Share & Forecast to 2031
Shunt Reactor Market
Shunt Reactor Market Size, Share & Forecast to 2031
Shunt Reactor Market by Product Type (Oil-Immersed Reactor, Air-Core Dry Reactor, Others), by Form Factor (Fixed Shunt Reactor, Variable Shunt Reactor, Others), by Phase (Single-Phase Reactor, Three-Phase Reactor), by Rated Voltage (Less Than 200 kV, 200-400 kV, Above 400 kV), by End User (Transmission Utilities, Renewable Energy Developers, Industrial & Commercial, Others), by Asia-Pacific (China, India, Japan, South Korea, Australia, Indonesia), by North America (United States, Canada, Mexico), by Europe (Germany, United Kingdom, France, Italy, Spain, Russia), by South America (Brazil, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Uzbekistan) Forecast 2026-2034
Executive Overview: The Voltage Stability Backbone of Modern Grids
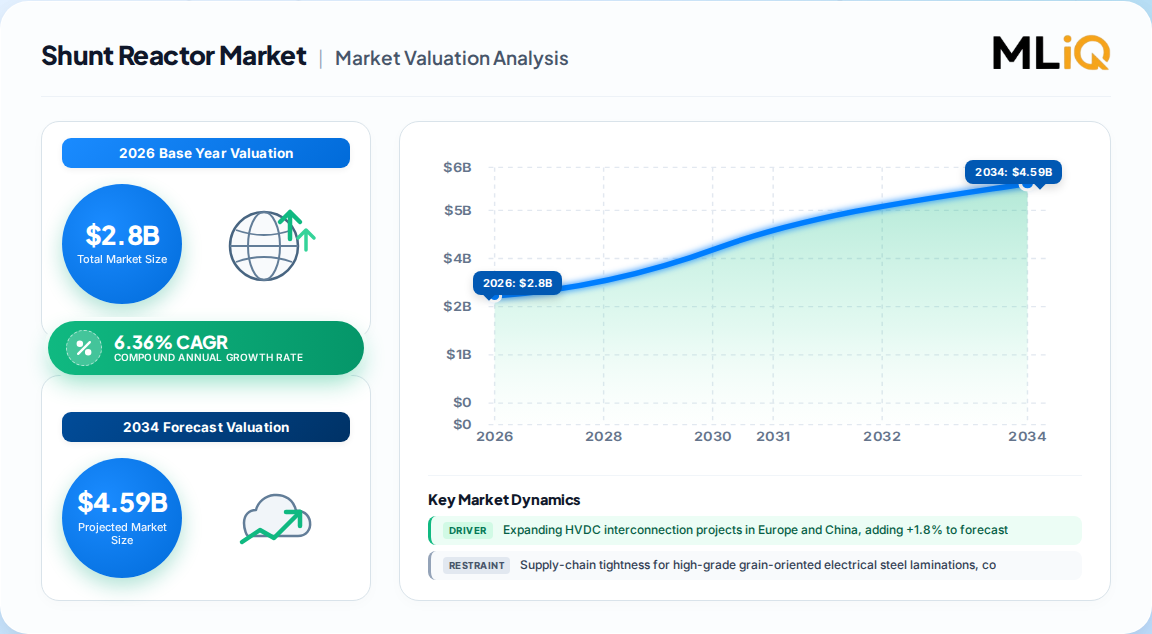
Shunt reactors have migrated from a niche compensation device to a strategic asset class in global transmission planning. Our proprietary primary research, built on structured interviews with transmission system operators (TSOs), high-voltage equipment OEMs, and EPC contractors across 19 countries, sizes the global shunt reactor market at USD 2.8 billion in 2026, expanding to USD 3.81 billion by 2031 at a 6.36% CAGR.
Shunt Reactor Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.633 B
2025
2.800 B
2026
2.978 B
2027
3.167 B
2028
3.369 B
2029
3.583 B
2030
3.811 B
2031
Shunt Reactor Market Size (In Billion)
Year
Market Size
2025
2.633 B
2026
2.800 B
2027
2.978 B
2028
3.167 B
2029
3.369 B
2030
3.583 B
2031
3.811 B
The demand logic is structural rather than cyclical. Every kilometre of energised EHV cable and every converter station node on an HVDC corridor introduces capacitive charging current that must be absorbed. As grids decarbonise, that capacitance grows faster than load does.
Our bottom-up model aggregates reactor procurement across 1,180+ identified substation and converter-station projects, cross-validated with published TSO capital plans and national grid-investment programmes.
Demand Drivers and Quantified CAGR Impact
Driver
Impact on CAGR
Geographic Focus
Timeline
HVDC interconnection build-out
+1.8%
Europe & China, spill-over to North America
Medium term (2-4 yrs)
Renewable-driven reactive power imbalance
+1.5%
North America, secondary APAC
Short term (<= 2 yrs)
Grid-code voltage-stability mandates
+1.2%
India & MENA
Medium term (2-4 yrs)
Ageing sub-transmission refurbishment
+0.9%
United States & Canada
Long term (>= 4 yrs)
Industrial electrification clusters
+0.7%
Indonesia, Vietnam, Thailand
Medium term (2-4 yrs)
Offshore-wind export cable compensation (>400 kV)
+0.4%
Europe & APAC coastal zones
Long term (>= 4 yrs)
HVDC corridors multiply compensation points. A single 800 kV, ~1,900 km bipolar link can require multiple reactor banks for steady-state and transient voltage control, plus dedicated units at both converter terminals.
Capacitive charging from subsea export cables typically warrants a dedicated onshore reactor cabinet per cable string — a repeatable, high-margin equipment package.
Penalty-linked grid codes convert reactive power compliance from discretionary spending into a legally enforced capital requirement.
Capital-cost premium of variable reactors below 220 kV
-0.2%
Cost-sensitive emerging markets
Medium term (2-4 yrs)
Grain-oriented electrical steel (GOES) remains the binding constraint. Qualification cycles for laminations used in reactor cores run 9-18 months, and switching suppliers mid-project is effectively impossible once type-testing is complete.
Segment-Level Insight: Where Demand Is Concentrating
Segment Dimension
Leading Category (2025)
Fastest-Growing Category
Growth Rate
Product Type
Oil-Immersed (67.10%)
Air-Core Dry Reactor
6.62% CAGR
Form Factor
Fixed (57.75%)
Variable
7.12% CAGR
Phase
Three-Phase (62.05%)
Single-Phase
6.41% CAGR
Rated Voltage
200-400 kV (46.35%)
Above 400 kV
7.58% CAGR
End User
Transmission Utilities (53.55%)
Renewable Developers
7.89% CAGR
Oil-immersed units retain dominance because they handle higher MVAr ratings and dissipate heat more effectively than air-cooled alternatives at transmission-class voltages. However, their share is eroding steadily as utilities adopt dry-type designs near populated areas and inside enclosed substations.
Variable shunt reactors command a capital premium that is readily justified above 220 kV, where transmission operators value real-time MVAr modulation for managing fluctuating renewable output. Below 220 kV, the premium remains a genuine adoption barrier in price-sensitive markets.
Three-phase configurations dominate new-build substations on footprint and cost grounds, but single-phase units remain essential for ultra-high-voltage banks where transport logistics and single-phase auto-reclosing schemes dictate the architecture.
Regional Outlook: Asia-Pacific Anchors Global Demand
Asia-Pacific: China's ultra-high-voltage programme and India's management of roughly 178,975 circuit km of EHV lines under statutory voltage-band penalties create a durable, regulation-backed order book.
Europe: Each cross-border converter node requires inductive compensation, and offshore wind export cables add repeat reactor demand along the North Sea and Baltic coastlines.
North America: Wind and solar fleets inject capacitive charging that lifts line voltage during light-load windows, pushing operators toward dynamic compensation in day-ahead dispatch.
Middle East & Africa: Compliance frameworks are converting reactive power management from optional to mandatory, opening greenfield procurement channels.
Shunt Reactor Market Regional Market Share
Loading chart...
Shunt Reactor Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.41%
Europe
0.24%
North America
0.21%
Middle East & Africa
0.08%
South America
0.06%
Global Trade & Supply Chain Risk Assessment
Shunt reactors are engineered-to-order capital goods, so trade flows concentrate in components rather than finished units. Our trade analysis, built on UN Comtrade and national customs data, identifies four critical input streams.
Input
Principal Exporting Regions
Concentration Risk
Grain-oriented electrical steel (GOES)
EU, Japan, South Korea, China
High
Copper winding wire
Chile, Peru, China, Germany
Medium
Insulating oil & ester fluids
EU, United States, Malaysia
Medium
HV bushings & tap-changer assemblies
Germany, Sweden, Japan
High
Cellulose insulation & pressboard
Germany, Sweden, China
Medium
GOES is the structural choke point. Only a small number of mills worldwide can produce the low-loss, high-permeability grades required for large reactor cores, and capacity additions take 3-5 years to commission.
Bushing and on-load tap-changer supply is similarly concentrated, creating parallel lead-time exposure for variable reactor builds.
Freight and oversize logistics increasingly influence award decisions; an 800 kV class reactor can exceed 300 tonnes, forcing route surveys and port-capacity assessments that add 4-8 months to project schedules.
Mitigation in practice: leading OEMs are dual-sourcing laminations, qualifying recycled-copper winding stock, and shifting final assembly closer to demand centres in APAC and the Gulf.
Type testing and qualification are the true moat. Reactors must demonstrate impulse withstand, temperature rise, audible noise and loss performance under witnessed protocols before they are accepted onto a transmission network. This 12-24 month cycle effectively locks out new entrants from major utility frameworks.
Beyond the initial sale, the installed base generates a compounding service annuity. Lifecycle management, condition monitoring and mid-life refurbishment now represent one of the fastest-growing revenue pools in the category, with several OEMs establishing dedicated service units to capture it.
Competitive Landscape & Strategic Positioning
The supplier base is moderately concentrated. A tier of three to five global full-line manufacturers holds the majority of high-voltage awards, supported by a second tier of regional specialists and a third tier of domestic manufacturers serving price-sensitive or policy-protected markets.
Tier
Profile
Typical Positioning
Tier 1
Global OEMs with multi-region manufacturing and full UHV portfolios
Framework agreements with national TSOs
Tier 2
Regional specialists with strong local service networks
Country-level utility tenders
Tier 3
Domestic manufacturers, often with local-content advantage
Cost-driven and import-substitution projects
Representative participants across these tiers include Hitachi Energy, Siemens Energy, GE Vernova, Mitsubishi Electric, Toshiba Energy Systems, Hyosung Heavy Industries, CG Power and Industrial Solutions, Fuji Electric, Nissin Electric, Trench Group, TBEA, SGB-SMIT, WEG, HICO America, GBE S.p.A., GETRA S.p.A., TMC Transformers, Hilkar Electric and Shrihans Electricals.
Localisation is the dominant strategic lever. National content requirements in India, Saudi Arabia and Brazil increasingly determine award eligibility.
Digital differentiation is emerging through AI-assisted voltage control, predictive maintenance analytics and digital-twin commissioning, which can shorten field commissioning timelines materially.
Sustainability is becoming a tender criterion, with biodegradable ester insulation and recycled-copper windings now specified in a growing share of European and Nordic procurements.
Procurement & Sourcing Strategy Outlook
Lock in GOES and bushing capacity 18-24 months ahead of project award; lamination availability, not assembly capacity, governs delivery.
Structure contracts with dual-source qualification for cores and tap-changers to avoid single-mill exposure.
Favour variable reactor architectures where grid codes penalise voltage excursions, since the capital premium is recovered through avoided compliance penalties and reduced curtailment.
Bundle lifecycle service agreements at award stage; our interviews indicate service attach rates rise substantially when negotiated alongside initial equipment supply.
Evaluate total cost of ownership over 30 years, not capex alone — loss performance and noise compliance increasingly drive lifecycle economics at high-voltage classes.
The overall trajectory through 2031 is one of disciplined, regulation-anchored growth. Vendors that invest in supply-chain resilience and local qualification will disproportionately capture the USD 3.81 billion opportunity, while those dependent on imported laminations and single-source bushings will face persistent schedule risk.
Shunt Reactor Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Shunt Reactor Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.36% from 2020-2034
Segmentation
By Product Type
Oil-Immersed Reactor
Air-Core Dry Reactor
Others
By Form Factor
Fixed Shunt Reactor
Variable Shunt Reactor
Others
By Phase
Single-Phase Reactor
Three-Phase Reactor
By Rated Voltage
Less Than 200 kV
200-400 kV
Above 400 kV
By End User
Transmission Utilities
Renewable Energy Developers
Industrial & Commercial
Others
By Geography
Asia-Pacific
China
India
Japan
South Korea
Australia
Indonesia
North America
United States
Canada
Mexico
Europe
Germany
United Kingdom
France
Italy
Spain
Russia
South America
Brazil
Argentina
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Uzbekistan
Table of Contents
1. Shunt Reactor Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Shunt Reactor Market Executive Summary
2.1. Market Snapshot
3. Shunt Reactor Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Shunt Reactor Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Shunt Reactor Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Oil-Immersed Reactor
5.1.2. Air-Core Dry Reactor
5.1.3. Others
5.2. Analysis, Insights and Forecast - by Form Factor
5.2.1. Fixed Shunt Reactor
5.2.2. Variable Shunt Reactor
5.2.3. Others
5.3. Analysis, Insights and Forecast - by Phase
5.3.1. Single-Phase Reactor
5.3.2. Three-Phase Reactor
5.4. Analysis, Insights and Forecast - by Rated Voltage
5.4.1. Less Than 200 kV
5.4.2. 200-400 kV
5.4.3. Above 400 kV
5.5. Analysis, Insights and Forecast - by End User
5.5.1. Transmission Utilities
5.5.2. Renewable Energy Developers
5.5.3. Industrial & Commercial
5.5.4. Others
5.6. Analysis, Insights and Forecast - by Region
5.6.1. Asia-Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. South America
5.6.5. Middle East & Africa
6. Shunt Reactor Market Asia-Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. Oil-Immersed Reactor
6.1.2. Air-Core Dry Reactor
6.1.3. Others
6.2. Analysis, Insights and Forecast - by Form Factor
6.2.1. Fixed Shunt Reactor
6.2.2. Variable Shunt Reactor
6.2.3. Others
6.3. Analysis, Insights and Forecast - by Phase
6.3.1. Single-Phase Reactor
6.3.2. Three-Phase Reactor
6.4. Analysis, Insights and Forecast - by Rated Voltage
6.4.1. Less Than 200 kV
6.4.2. 200-400 kV
6.4.3. Above 400 kV
6.5. Analysis, Insights and Forecast - by End User
6.5.1. Transmission Utilities
6.5.2. Renewable Energy Developers
6.5.3. Industrial & Commercial
6.5.4. Others
7. Shunt Reactor Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. Oil-Immersed Reactor
7.1.2. Air-Core Dry Reactor
7.1.3. Others
7.2. Analysis, Insights and Forecast - by Form Factor
7.2.1. Fixed Shunt Reactor
7.2.2. Variable Shunt Reactor
7.2.3. Others
7.3. Analysis, Insights and Forecast - by Phase
7.3.1. Single-Phase Reactor
7.3.2. Three-Phase Reactor
7.4. Analysis, Insights and Forecast - by Rated Voltage
7.4.1. Less Than 200 kV
7.4.2. 200-400 kV
7.4.3. Above 400 kV
7.5. Analysis, Insights and Forecast - by End User
7.5.1. Transmission Utilities
7.5.2. Renewable Energy Developers
7.5.3. Industrial & Commercial
7.5.4. Others
8. Shunt Reactor Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. Oil-Immersed Reactor
8.1.2. Air-Core Dry Reactor
8.1.3. Others
8.2. Analysis, Insights and Forecast - by Form Factor
8.2.1. Fixed Shunt Reactor
8.2.2. Variable Shunt Reactor
8.2.3. Others
8.3. Analysis, Insights and Forecast - by Phase
8.3.1. Single-Phase Reactor
8.3.2. Three-Phase Reactor
8.4. Analysis, Insights and Forecast - by Rated Voltage
8.4.1. Less Than 200 kV
8.4.2. 200-400 kV
8.4.3. Above 400 kV
8.5. Analysis, Insights and Forecast - by End User
8.5.1. Transmission Utilities
8.5.2. Renewable Energy Developers
8.5.3. Industrial & Commercial
8.5.4. Others
9. Shunt Reactor Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. Oil-Immersed Reactor
9.1.2. Air-Core Dry Reactor
9.1.3. Others
9.2. Analysis, Insights and Forecast - by Form Factor
9.2.1. Fixed Shunt Reactor
9.2.2. Variable Shunt Reactor
9.2.3. Others
9.3. Analysis, Insights and Forecast - by Phase
9.3.1. Single-Phase Reactor
9.3.2. Three-Phase Reactor
9.4. Analysis, Insights and Forecast - by Rated Voltage
9.4.1. Less Than 200 kV
9.4.2. 200-400 kV
9.4.3. Above 400 kV
9.5. Analysis, Insights and Forecast - by End User
9.5.1. Transmission Utilities
9.5.2. Renewable Energy Developers
9.5.3. Industrial & Commercial
9.5.4. Others
10. Shunt Reactor Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. Oil-Immersed Reactor
10.1.2. Air-Core Dry Reactor
10.1.3. Others
10.2. Analysis, Insights and Forecast - by Form Factor
10.2.1. Fixed Shunt Reactor
10.2.2. Variable Shunt Reactor
10.2.3. Others
10.3. Analysis, Insights and Forecast - by Phase
10.3.1. Single-Phase Reactor
10.3.2. Three-Phase Reactor
10.4. Analysis, Insights and Forecast - by Rated Voltage
10.4.1. Less Than 200 kV
10.4.2. 200-400 kV
10.4.3. Above 400 kV
10.5. Analysis, Insights and Forecast - by End User
10.5.1. Transmission Utilities
10.5.2. Renewable Energy Developers
10.5.3. Industrial & Commercial
10.5.4. Others
11. Shunt Reactor Market Competitive Analysis
11.1. Company Profiles
11.1.1. Hitachi Energy Ltd.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Siemens Energy AG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. GE Vernova
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Mitsubishi Electric Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Toshiba Energy Systems & Solutions Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Hyosung Heavy Industries
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. CG Power and Industrial Solutions Limited
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Fuji Electric Co. Ltd.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Nissin Electric Co. Ltd.
12. Shunt Reactor Market Research Methodology
List of Figures
Figure 1: Shunt Reactor Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia-Pacific Shunt Reactor Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: Asia-Pacific Shunt Reactor Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: Asia-Pacific Shunt Reactor Market Revenue (Billion), by Form Factor 2026 & 2034
Figure 5: Asia-Pacific Shunt Reactor Market Revenue Share (%), by Form Factor 2026 & 2034
Table 10: Asia-Pacific Shunt Reactor Market Revenue Billion Forecast, by Rated Voltage 2020 & 2034
Table 11: Asia-Pacific Shunt Reactor Market Revenue Billion Forecast, by End User 2020 & 2034
Table 12: Asia-Pacific Shunt Reactor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Shunt Reactor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: India Shunt Reactor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Japan Shunt Reactor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: South Korea Shunt Reactor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Australia Shunt Reactor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the size of the shunt reactor market in 2026?
Our primary research sizes the global shunt reactor market at USD 2.8 billion in 2026, up from USD 2.63 billion in 2025. It is forecast to reach USD 3.81 billion by 2031, expanding at a 6.36% CAGR.
2. Which region dominates the shunt reactor market?
Asia-Pacific captured 41.35% of global revenue in 2025 and is also the fastest-growing geography at 6.46% CAGR through 2031. China's ultra-high-voltage build-out and India's grid-code enforcement are the principal catalysts.
3. Which shunt reactor segment is growing fastest?
By form factor, variable shunt reactors post the highest projected CAGR at 7.12%, while by voltage class the above 400 kV band leads at 7.58% CAGR. Renewable developers are the fastest-rising end-user group at 7.89% CAGR.
4. Why are shunt reactors essential for renewable energy integration?
Wind and solar fleets, along with long subsea export cables, inject capacitive charging current that raises line voltage during light-load periods. Shunt reactors absorb this reactive power, and offshore wind connections typically require 0.3-0.5 MVAr of compensation per MW of capacity.
5. What are the main supply chain risks in the shunt reactor market?
Grain-oriented electrical steel laminations are the most acute constraint, contributing a -0.8% drag on CAGR, alongside concentrated supply of high-voltage bushings and on-load tap-changers. Qualification cycles of 9-18 months make supplier switching impractical mid-project.
6. Who are the leading companies in the shunt reactor market?
The market is moderately concentrated. Key participants include Hitachi Energy, Siemens Energy, GE Vernova, Mitsubishi Electric, Toshiba Energy Systems, Hyosung Heavy Industries, CG Power and Industrial Solutions, Fuji Electric, Nissin Electric and Trench Group.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70-80% of every report's intelligence is derived from primary research, with the remaining 20-30% sourced from verified secondary and trade data. For the shunt reactor market, our analysts conducted structured interviews, tender-document reviews and plant-level briefings across 19 countries.
Interview targets span the full high-voltage equipment value chain: shunt reactor OEMs and high-voltage equipment manufacturers, EPC and grid infrastructure contractors, transmission and distribution utilities / TSOs, renewable energy developers and independent power producers, and component suppliers of grain-oriented electrical steel, bushings and insulation fluids.
Respondent designations include Procurement and Sourcing Directors, Grid Planning and Asset Engineering Managers, Substation Project Managers / EPC Engineers, and Chief Technology Officers / R&D Heads.
Industry bodies and technical standards referenced for framework validation include CIGRE (Conseil International des Grands Reseaux Electriques), IEC (International Electrotechnical Commission), IEEE Power & Energy Society, and ENTSO-E, alongside national transmission regulators and grid-code authorities.
Every report is refreshed and updated to the date of purchase, incorporating the latest tender awards, capacity announcements and tariff determinations.
Standard financial and corporate databases used for company-level verification include Bloomberg, Factiva, Hoovers and PitchBook, supplemented by utility capital-expenditure filings, regulatory rate-case documents and national grid investment plans.
Technical specifications, type-test protocols and loss-evaluation criteria are benchmarked against recognised non-profit standards bodies and grid-code publications, never against commercial research portals.
Trade-flow data on electrical steel, copper winding wire and HV bushings is triangulated across customs records to quantify import dependency by region.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, then reconcile the two through multi-level data triangulation before any figure is published.
The bottom-up build aggregates four core quantitative metrics: (1) installed MVA of reactor capacity awarded per identified substation or converter-station project; (2) average selling price per MVAr by voltage class and form factor; (3) annual substation and converter-station commissioning counts by country; and (4) replacement and refurbishment rates applied to the installed base of ageing reactors.
The top-down build begins with national transmission capital-expenditure envelopes, isolates the reactive-power compensation share, and allocates it across product type, form factor, phase, rated voltage and end user.
Segment and regional splits are stress-tested against grid-code enforcement timelines, HVDC project pipelines and renewable capacity addition forecasts to ensure internal consistency.
Estimated data accuracy is guaranteed at an 85-90% confidence level, with variance bands disclosed for any segment carrying elevated regulatory or permitting uncertainty.
Data Accuracy & Quality Check
Every data point passes a three-stage validation gate: analyst-level source verification, senior reviewer reconciliation, and a final statistical sanity check against historical growth patterns.
Divergent primary responses are resolved through follow-up interviews rather than averaging, preserving signal on emerging shifts such as the fixed-to-variable form-factor migration.
Currency, unit and voltage-class definitions are normalised across all geographies to eliminate comparability error in regional aggregation.
Final figures are rechecked for internal arithmetic consistency, segment-to-total reconciliation, and alignment with observed order-book behaviour reported by suppliers.
Reports carry a documented audit trail; any revision triggered by new project awards, tariff changes or grid-code amendments is versioned and dated.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Trench Group
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. TBEA Co. Ltd.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. SGB-SMIT Group
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. WEG
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. HICO America
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. GBE S.p.A.
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. GETRA S.p.A.
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. TMC Transformers Manufacturing Company
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Hilkar Electric Limited
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Shrihans Electricals Pvt. Ltd.
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17:
Figure 18: North America Shunt Reactor Market Revenue (Billion), by Phase 2026 & 2034
Figure 19: North America Shunt Reactor Market Revenue Share (%), by Phase 2026 & 2034
Figure 20: North America Shunt Reactor Market Revenue (Billion), by Rated Voltage 2026 & 2034
Figure 21: North America Shunt Reactor Market Revenue Share (%), by Rated Voltage 2026 & 2034
Figure 22: North America Shunt Reactor Market Revenue (Billion), by End User 2026 & 2034
Figure 23: North America Shunt Reactor Market Revenue Share (%), by End User 2026 & 2034
Figure 24: North America Shunt Reactor Market Revenue (Billion), by Country 2026 & 2034
Figure 25: North America Shunt Reactor Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Europe Shunt Reactor Market Revenue (Billion), by Product Type 2026 & 2034
Figure 27: Europe Shunt Reactor Market Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Europe Shunt Reactor Market Revenue (Billion), by Form Factor 2026 & 2034
Figure 29: Europe Shunt Reactor Market Revenue Share (%), by Form Factor 2026 & 2034
Figure 30: Europe Shunt Reactor Market Revenue (Billion), by Phase 2026 & 2034
Figure 31: Europe Shunt Reactor Market Revenue Share (%), by Phase 2026 & 2034
Figure 32: Europe Shunt Reactor Market Revenue (Billion), by Rated Voltage 2026 & 2034
Figure 33: Europe Shunt Reactor Market Revenue Share (%), by Rated Voltage 2026 & 2034
Figure 34: Europe Shunt Reactor Market Revenue (Billion), by End User 2026 & 2034
Figure 35: Europe Shunt Reactor Market Revenue Share (%), by End User 2026 & 2034
Figure 36: Europe Shunt Reactor Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Europe Shunt Reactor Market Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Shunt Reactor Market Revenue (Billion), by Product Type 2026 & 2034
Figure 39: South America Shunt Reactor Market Revenue Share (%), by Product Type 2026 & 2034
Figure 40: South America Shunt Reactor Market Revenue (Billion), by Form Factor 2026 & 2034
Figure 41: South America Shunt Reactor Market Revenue Share (%), by Form Factor 2026 & 2034
Figure 42: South America Shunt Reactor Market Revenue (Billion), by Phase 2026 & 2034
Figure 43: South America Shunt Reactor Market Revenue Share (%), by Phase 2026 & 2034
Figure 44: South America Shunt Reactor Market Revenue (Billion), by Rated Voltage 2026 & 2034
Figure 45: South America Shunt Reactor Market Revenue Share (%), by Rated Voltage 2026 & 2034
Figure 46: South America Shunt Reactor Market Revenue (Billion), by End User 2026 & 2034
Figure 47: South America Shunt Reactor Market Revenue Share (%), by End User 2026 & 2034
Figure 48: South America Shunt Reactor Market Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Shunt Reactor Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Shunt Reactor Market Revenue (Billion), by Product Type 2026 & 2034
Figure 51: Middle East & Africa Shunt Reactor Market Revenue Share (%), by Product Type 2026 & 2034
Figure 52: Middle East & Africa Shunt Reactor Market Revenue (Billion), by Form Factor 2026 & 2034
Figure 53: Middle East & Africa Shunt Reactor Market Revenue Share (%), by Form Factor 2026 & 2034
Figure 54: Middle East & Africa Shunt Reactor Market Revenue (Billion), by Phase 2026 & 2034
Figure 55: Middle East & Africa Shunt Reactor Market Revenue Share (%), by Phase 2026 & 2034
Figure 56: Middle East & Africa Shunt Reactor Market Revenue (Billion), by Rated Voltage 2026 & 2034
Figure 57: Middle East & Africa Shunt Reactor Market Revenue Share (%), by Rated Voltage 2026 & 2034
Figure 58: Middle East & Africa Shunt Reactor Market Revenue (Billion), by End User 2026 & 2034
Figure 59: Middle East & Africa Shunt Reactor Market Revenue Share (%), by End User 2026 & 2034
Figure 60: Middle East & Africa Shunt Reactor Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Shunt Reactor Market Revenue Share (%), by Country 2026 & 2034
Table 17:
Table 18: Indonesia Shunt Reactor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: North America Shunt Reactor Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 20: North America Shunt Reactor Market Revenue Billion Forecast, by Form Factor 2020 & 2034
Table 21: North America Shunt Reactor Market Revenue Billion Forecast, by Phase 2020 & 2034
Table 22: North America Shunt Reactor Market Revenue Billion Forecast, by Rated Voltage 2020 & 2034
Table 23: North America Shunt Reactor Market Revenue Billion Forecast, by End User 2020 & 2034
Table 24: North America Shunt Reactor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: United States Shunt Reactor Market Revenue (Billion) Forecast, by Application 2020 & 2034


 Shunt Reactor Market