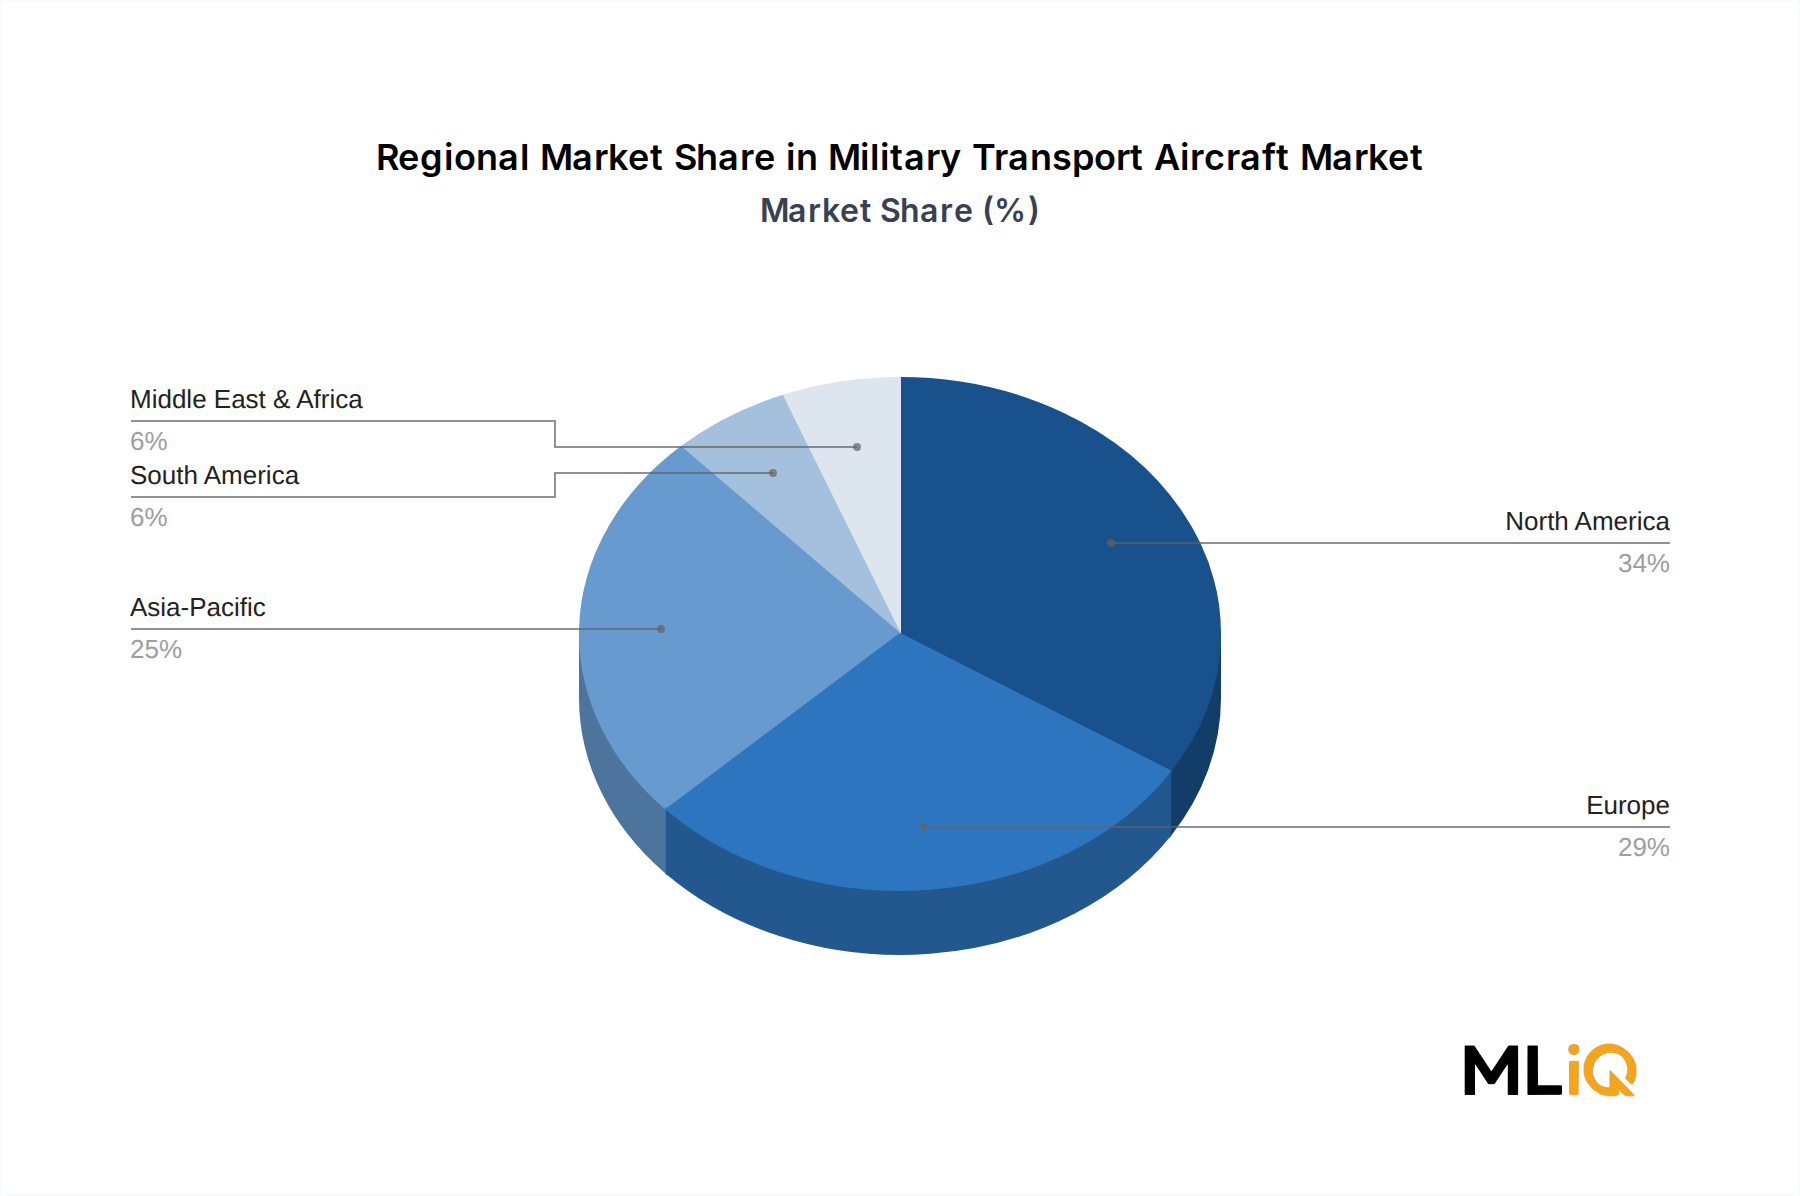
Fixed-wing aircraft constitute the dominant segment within the Military Transport Aircraft Market, commanding the majority of global revenue share by a substantial margin when compared to rotary-wing alternatives. This dominance is structural rather than cyclical, rooted in the physics of long-range strategic airlift, the economics of bulk cargo movement, and the institutional preferences of major defense establishments worldwide.
The primacy of fixed-wing transports is most evident in the heavy-payload category — specifically platforms capable of lifting 101 tons and above. Aircraft such as the Boeing C-17 Globemaster III, the Airbus A400M Atlas, and the Lockheed C-5M Super Galaxy serve as the backbone of strategic airlift for the United States Air Force, the UK Royal Air Force, and multiple NATO allies. These platforms offer intercontinental range, large volumetric cargo capacity, and the ability to deliver outsized loads — including main battle tanks, helicopters, and artillery systems — directly to forward operating locations with improved runway capability compared to older generation heavy lifters.
Within the fixed-wing sub-segment, the 51 Tons to 100 Tons payload category is experiencing the most dynamic procurement activity. The Airbus A400M is the flagship platform in this class, combining turboprop efficiency with jet-comparable speed and the ability to operate from semi-prepared airstrips. Nations including France, Germany, Spain, Turkey, and Malaysia have procured A400M fleets, and additional orders continue to emerge from nations seeking to replace aging C-130 Hercules fleets. Japan's Kawasaki C-2, Brazil's Embraer KC-390 Millennium, and Russia's Ilyushin Il-76MD-90A are competing in overlapping payload ranges, intensifying competition in this tier.
The below-50-ton tactical transport segment, historically dominated by the C-130 Hercules family, is transitioning toward more modern solutions. Embraer's KC-390 has emerged as a credible challenger to the C-130J Super Hercules, offering higher speed, greater payload, and lower maintenance burden through its fly-by-wire architecture and modern CFM International LEAP turbofan engines. Countries such as Portugal, Hungary, and the Netherlands have selected the KC-390, signaling a meaningful shift in procurement preferences.
Key players entrenched in the fixed-wing dominance include Lockheed Martin Corporation (C-130J), Airbus SE (A400M, CN-235, C-295), Embraer SA (KC-390), Boeing (C-17), and Kawasaki Heavy Industries (C-2). These OEMs collectively hold long-term production contracts, MRO agreements, and upgrade programs that extend revenue visibility well beyond initial platform delivery.
The segment's share is consolidating rather than growing in proportional terms — fixed-wing aircraft have long held their commanding position, and rotorcraft are not expected to erode this structurally. However, within the fixed-wing category itself, shifts are occurring: medium tactical transports are growing at a faster clip than the heavy strategic segment, driven by more nations acquiring independent airlift capabilities rather than relying exclusively on allied strategic lift pooling arrangements. This democratization of airlift capability is one of the most defining dynamics shaping segment evolution through 2033.
The application breakdown further reinforces fixed-wing dominance. Cargo supply missions — including logistical resupply, airdrop operations, and medical evacuation — represent the largest application share, followed by troop airlifting and a residual "Others" category encompassing special operations support, aerial refueling tanker variants, and signals intelligence configurations.