Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
MEA Airport Passenger Screening Systems Market: 2.52% CAGR
MEA Airport Passenger Screening Systems Industry
MEA Airport Passenger Screening Systems Market: 2.52% CAGR
MEA Airport Passenger Screening Systems Industry by Type (Metal Detectors, Full Body Scanners, Advanced Imaging Technology), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 14, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: MEA Airport Passenger Screening Systems Industry Market
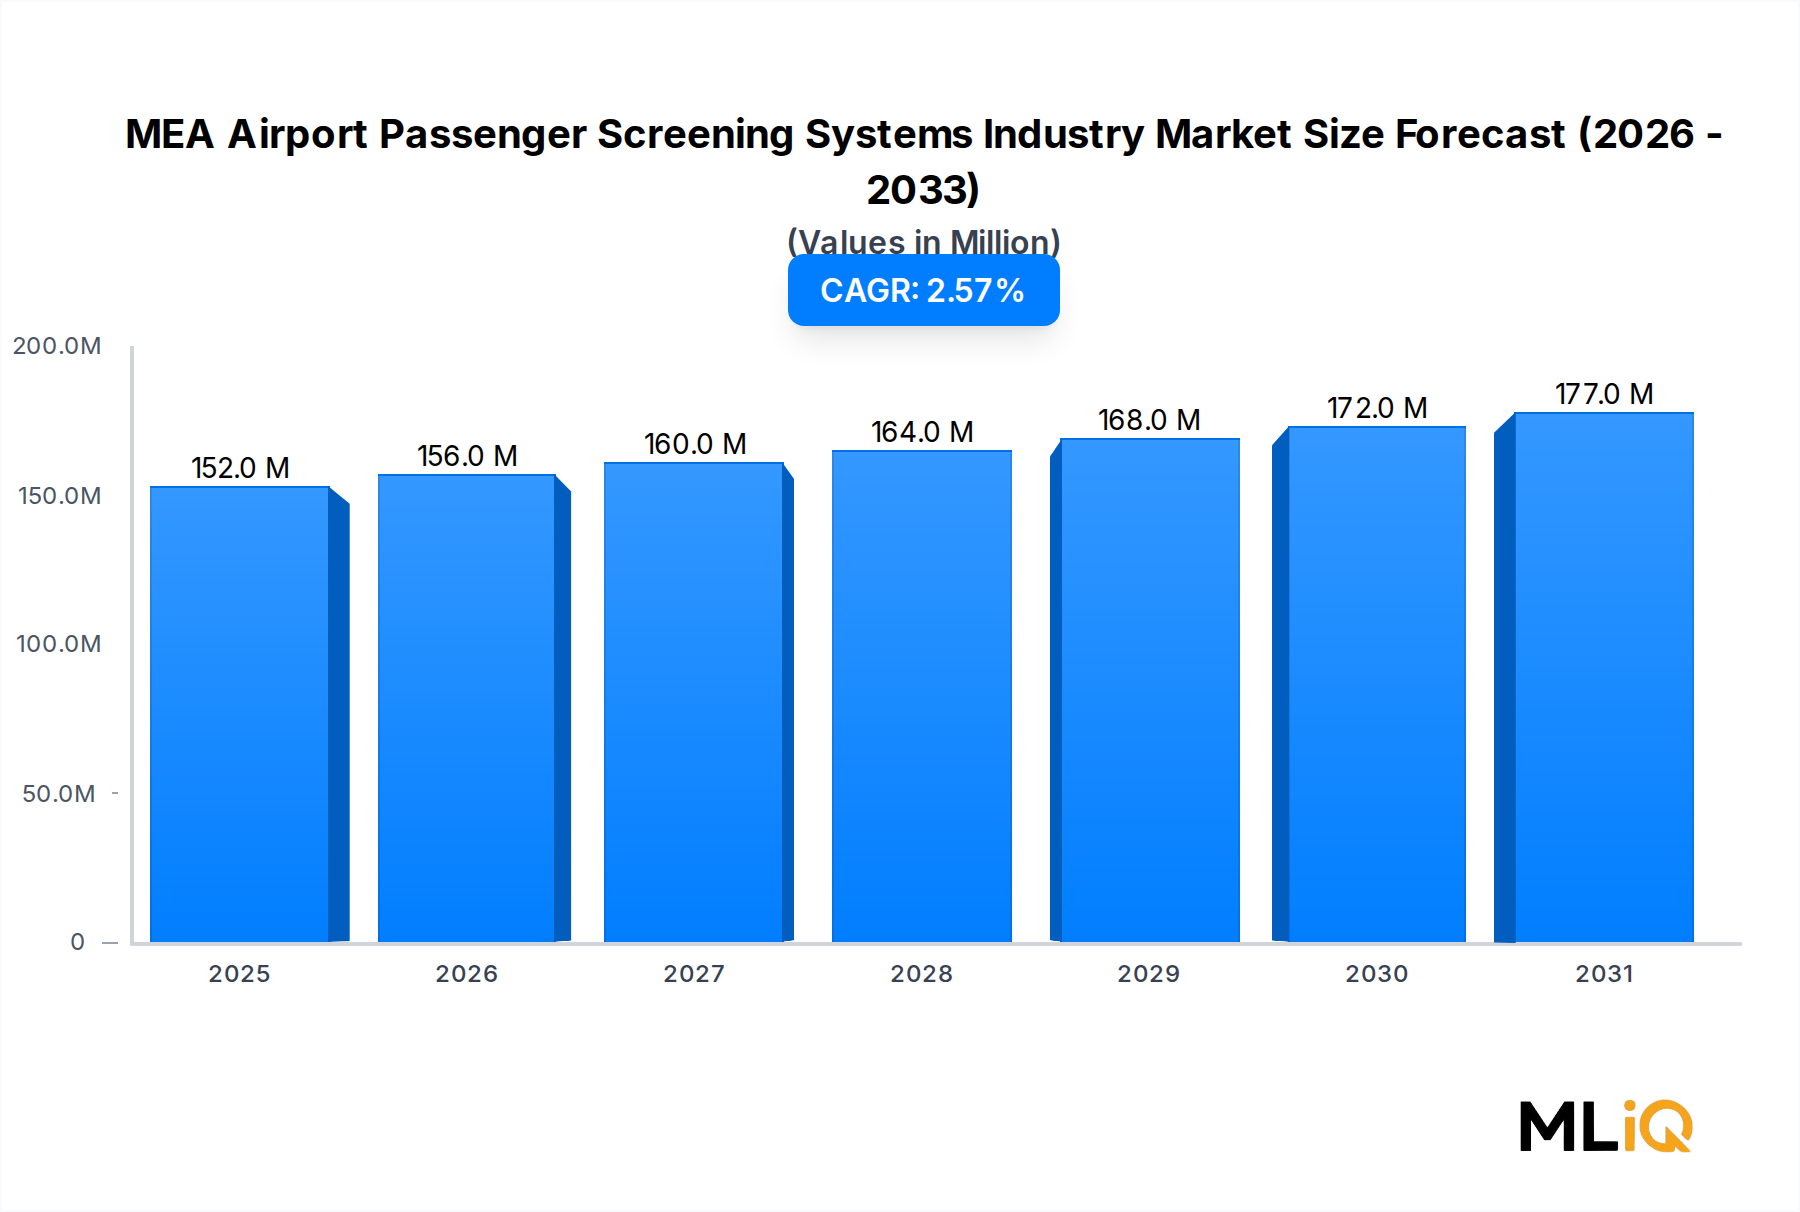
The MEA Airport Passenger Screening Systems Industry Market closed 2025 at USD 152.17 million and is forecast to reach USD 190.4 million by 2034, expanding at a 2.52% CAGR between 2026 and 2034. Middle East & Africa accounts for roughly 30% of global screening-system revenue while processing under 10% of world passenger traffic, a ratio driven by mandatory secondary screening at every international gateway in the region.
MEA Airport Passenger Screening Systems Industry Market Size (In Million)
200.0M
150.0M
100.0M
50.0M
0
152.0 M
2025
156.0 M
2026
160.0 M
2027
164.0 M
2028
168.0 M
2029
172.0 M
2030
177.0 M
2031
Three forces define the current cycle. Terminal capacity programmes in Egypt, Turkey, Saudi Arabia and the UAE are adding screening lanes faster than legacy equipment can be retired. Regulators continue to widen the mandated installed base for explosive trace detection and body imaging. At the same time, price competition from Nuctech and regional integrators compresses hardware gross margins into the 18-24% band.
Key structural signals:
Volume outpaces value. Unit shipments are growing near 4.1% annually against 2.52% revenue growth, implying per-unit price erosion of roughly 1.5% per year.
Replacement, not greenfield. Approximately 60% of 2026-2034 demand replaces equipment installed between 2012 and 2018, shortening sales cycles and favouring incumbents with service contracts.
Service revenue rising. Maintenance, calibration and consumables now represent an estimated 27% of vendor revenue in the Airport Security Screening Market, up from 21% in 2020.
Concentration risk. The top five vendors hold an estimated 58% of the regional installed base, but Chinese and Turkish suppliers are gaining share in price-sensitive North African tenders.
The implication for buyers is that capital budgets will shift from lane-count expansion toward detection fidelity - computed tomography, trace detection and automated alarm resolution - where per-lane pricing is 2.5x to 4x higher than conventional walk-through portals.
Segment Deep-Dive: Advanced Imaging Technology Dominance in MEA Airport Passenger Screening Systems Industry Market
Segment Analysis Matrix
Segment
CAGR 2026-2034 (%)
Market Share 2025 (%)
Key Demand Driver
Advanced Imaging Technology
4.10%
46%
CT checkpoint mandates and liquid-explosive detection rules
Full Body Scanners
3.20%
31%
Privacy-compliant millimetre-wave deployment at GCC hubs
Metal Detectors
1.10%
23%
Baseline walk-through screening in secondary and domestic terminals
Advanced Imaging Technology: The Revenue Engine
The Advanced Imaging Technology Market is the largest and fastest-compounding segment, generating an estimated USD 70.0 million of the USD 152.17 million regional total in 2025. Two regulatory shifts explain the premium: ICAO Annex 17 amendments encouraging inline checked-baggage CT, and national mandates in Saudi Arabia and the UAE requiring advanced imaging at all international departure lanes by 2027.
Capital cost per CT lane ranges from USD 320,000 to USD 520,000, versus USD 45,000 to USD 80,000 for a walk-through portal.
Software and remote-screening licences contribute 12-16% of lifetime segment revenue, a margin pool that hardware-only vendors cannot access.
Deployment lead times of 9-15 months create a demand backlog that cushions the segment against short-term traffic shocks.
Full Body Scanners: Compliance-Led Volume
The Full Body Scanners Market sits at 31% share and grows at 3.20%, supported by privacy-preserving millimetre-wave platforms that replaced backscatter units after backscatter was withdrawn from primary screening in 2012. Regional adoption is concentrated in the GCC, Israel and Turkey, where hubs such as Dubai, Doha and Istanbul each handle more than 25 million passengers annually.
Average selling prices have fallen from USD 175,000 in 2016 to roughly USD 130,000 in 2025 as three vendors now offer comparable platforms.
Automated threat recognition software removes the need for a dedicated image reviewer, cutting per-lane staffing by 1-2 full-time equivalents per shift.
Metal Detectors: Mature, Margin-Squeezed
The Airport Metal Detectors Market grows at only 1.10% and faces the sharpest margin pressure of the three segments. Walk-through portals remain the cheapest compliant option at USD 4,500-12,000 per unit, which makes them vulnerable to local assembly and low-cost imports across North Africa.
Segment share declines from 23% in 2025 to an estimated 19% by 2034 as lanes upgrade to imaging platforms.
Differentiation is shifting to multi-zone detection, Wi-Fi-enabled diagnostics and queue-management integration rather than coil sensitivity.
Margin Pressure Across the Stack
Blended segment gross margin sits near 22%. Advanced imaging carries 28-34%, body scanners 19-23%, and metal detectors 11-15%. Vendors with a service annuity above 25% of revenue sustain margins roughly 4-6 percentage points higher than hardware-only competitors, which explains consolidation toward integrated screening suites.
Primary Market Drivers & Growth Restraints in MEA Airport Passenger Screening Systems Industry Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Airport Terminal Construction Market activity adding 120+ million annual passenger capacity across Egypt, Turkey and Saudi Arabia
High
Medium term
Driver
Mandated upgrade from single-view X-ray to CT-based screening at international departure lanes
High
Short term
Driver
Privatisation of airport operations increasing equipment refresh budgets
Medium
Medium term
Restraint
Foreign exchange volatility in Egypt, Turkey and Nigeria delaying import-dependent procurement
High
Short term
Restraint
Shortage of certified screening operators limiting throughput gains from new hardware
Medium
Long term
Restraint
Tender cycles of 12-24 months stretching vendor working capital
Medium
Long term
Demand Catalysts
Passenger traffic across the Middle East is recovering above 2019 levels at hubs such as Dubai and Doha, while African traffic grows at roughly 5.4% annually. Every incremental 10 million annual passengers typically requires 8-12 additional screening lanes when measured against ICAO throughput guidance. The Computed Tomography Security Scanners Market is the primary beneficiary: these units detect liquid and powder threats that dual-energy X-ray cannot resolve, and their price point above USD 300,000 per lane lifts revenue per installed lane by roughly 6x.
National aviation strategies reinforce the trend. Saudi Arabia targets 330 million annual passengers by 2030 under its aviation roadmap, and Turkey's Antalya expansion alone lifts capacity from 40 million to 80 million passengers. Sustained Airport Terminal Construction Market activity of that scale cascades directly into screening procurement.
Structural Restraints
Currency risk. Egyptian pound and Turkish lira depreciation raised imported equipment costs by 30-60% in local terms between 2022 and 2024, forcing phased tendering.
Trained personnel gap. Regional regulators license screening officers individually, and a shortfall of certified staff delays activation of installed lanes by 3-6 months.
Standards fragmentation. Divergent national acceptance lists mean a platform approved in the UAE may require fresh type approval in Egypt or Nigeria, adding 6-9 months and USD 40,000-90,000 per market.
Competitive Ecosystem & Key Vendor Profiles: MEA Airport Passenger Screening Systems Industry Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
Rapiscan Systems (OSI Systems Inc.)
Broad X-ray, CT and trace portfolio with global service network
National aviation authorities, hub operators
Leader
Leidos Inc.
Checked-baggage CT and integrated security architecture
Government agencies, large hub airports
Leader
Nuctech Company Limited
Cost-competitive CT and X-ray platforms at scale
Regional airports, price-sensitive tenders
Challenger
Vanderlande Industries
Baggage handling and screening lane integration
Airport terminal contractors
Challenger
Garrett Electronics Inc.
Walk-through metal detection and multi-zone portals
Secondary terminals, government buildings
Challenger
C.E.I.A. SpA
X-ray and EDS systems for European and African markets
Mid-size airports, customs agencies
Niche
SITA
Screening data integration and passenger flow software
Airport IT departments, border agencies
Challenger
Elenium Automation
Self-service screening touchpoints and automation
High-throughput hubs
Niche
Kromek Group plc
Radiation detection materials and solid-state sensors
OEMs, defence integrators
Niche
Scarabee Aviation Group
Trace detection consumables and calibration services
Airport operations teams
Niche
Rapiscan Systems (OSI Systems Inc.): Leverages an installed base across more than 100 countries and bundles CT, X-ray and trace detection into single tenders, shortening procurement cycles for hub operators.
Leidos Inc.: Focused on checked-baggage CT and security integration contracts, with depth in government-funded programmes that tolerate longer sales cycles.
Nuctech Company Limited: Compresses hardware pricing by an estimated 15-25% versus Western OEMs and has expanded into North and East African tenders.
Vanderlande Industries: Positions screening as a subsystem of baggage handling, capturing integration revenue even where detection hardware is third-party.
Garrett Electronics Inc.: Retains a defensible position in walk-through portals, though the Airport Metal Detectors Market limits upside.
C.E.I.A. SpA: Italian supplier with type approvals across multiple European and African regulators, suited to mid-size airports with constrained budgets.
SITA: Software layer connecting screening outcomes to passenger flow systems, monetised per passenger rather than per lane.
Elenium Automation: Sells self-service screening and biometric touchpoints aimed at labour-constrained Gulf hubs.
Kromek Group plc: Supplies solid-state detector materials and components rather than complete lanes, positioning it upstream of OEM assembly.
Scarabee Aviation Group: Focuses on trace detection consumables, calibration and training, a recurring-revenue niche with 30%+ gross margins.
Strategic Milestones & Recent Developments in MEA Airport Passenger Screening Systems Industry Market
Latest Strategic Moves
Date
Company
Event Type
Impact
December 2022
Cairo International Airport / Egyptian Civil Aviation Authority
Infrastructure Expansion
High
November 2022
Antalya Airport (Turkey)
Capacity Expansion
High
2023-2026 (ongoing)
Regional airport operators and screening vendors
Retrofit and Lane Modernisation
Medium-High
November 2022 - Antalya Airport expansion (Turkey). Officials approved a three-phase programme lifting annual capacity from 40 million to 80 million passengers. At ICAO throughput norms, the buildout implies 30-45 additional screening lanes across departures and transfer corridors, with procurement spread across the phase schedule.
December 2022 - Cairo International Airport Terminal 4 completion (Egypt). The Egyptian Civil Aviation Authority completed studies and construction for a fourth terminal expressly intended to reduce passenger density in the existing three terminals. The redesign redistributes screening load, lowering peak-hour lane demand per terminal while raising the total count of certified lanes and trace-detection positions.
2023-2026 - Retrofit cycle across the GCC and North Africa. Operators are replacing single-view X-ray lanes with CT-capable platforms and adding automated tray return. These projects are smaller individually but recur annually, and they favour vendors with regional spare-parts depots because downtime penalties in service contracts now reach 2-4% of contract value.
Regional Market Analysis & Growth Corridors for MEA Airport Passenger Screening Systems Industry Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
Middle East & Africa
3.85%
USD 45.7 million
Terminal expansion in Egypt, Turkey, Saudi Arabia and the GCC
High
Asia-Pacific
3.10%
USD 36.5 million
Greenfield airports in China, India and Indonesia
Medium-High
Europe
1.90%
USD 30.4 million
ECAC standard upgrades and CT retrofit cycles
Very High
North America
1.75%
USD 27.4 million
TSA lane reconfiguration and checked-baggage CT
High
South America
1.40%
USD 12.2 million
Concession renewals in Brazil and Colombia
Medium
Fastest-Growing Corridor: Middle East & Africa
Middle East & Africa grows at 3.85%, roughly 1.3 percentage points above the global average, supported by capacity programmes that add more than 120 million annual passenger seats this decade. The Middle East Aviation Security Market is the single most attractive sub-geography for vendors because average revenue per lane there is 2.1x the Asia-Pacific level, reflecting heavier use of CT and trace-detection equipment per departure.
GCC: highest equipment specification and shortest replacement cycles of 5-7 years.
Turkey: largest single pipeline via Antalya and Istanbul capacity works.
North Africa: price-sensitive, with tender awards increasingly contested by Chinese suppliers.
Most Mature Markets: Europe and North America
Europe and North America together hold 38% of global value but grow at only 1.75-1.90%. Demand is replacement-driven: CT installation at EU hubs proceeds under ECAC C3 and C4 standards, while US lanes continue reconfiguration following checked-baggage CT mandates. Both regions enforce the strictest type-approval regimes, which raises compliance cost and also raises switching costs for incumbent vendors.
Underpenetrated Opportunity: South America and Sub-Saharan Africa
South America represents only 8% of global value at 1.40% CAGR, constrained by concession renewals and currency volatility. Sub-Saharan Africa outside South Africa remains the least-equipped geography in absolute terms, where walk-through portals and handheld detectors still constitute the majority of installed units.
Regulatory & Policy Landscape: MEA Airport Passenger Screening Systems Industry Market
Screening equipment sits at the intersection of aviation security regulation, radiation safety law and occupational health rules.
ICAO Annex 17 sets the baseline: states must ensure screening of passengers and cabin baggage, and it drives periodic revision of national acceptance lists.
ECAC Common Evaluation Process (CEP) governs European type approval; a C3 or C4 designation signals CT capability and is increasingly required for transfer lanes.
US TSA Qualified Products List and EU radiation safety directives (national implementations of IAEA Basic Safety Standards) impose dose limits on operators, which shapes demand in the Radiation Shielding Materials Market for enclosure, collimation and shielding assemblies.
Manufacturing standards including ISO 9001, IEC 62471 photobiological safety, and RoHS and REACH restrictions on lead and certain flame retardants affect the X-ray Detection Components Market, particularly for detectors using older scintillator chemistries.
Recent policy direction concentrates on automated threat recognition: regulators now permit alarm resolution without a human image reviewer where software is certified, which reduces staffing requirements by 1-2 operators per lane and reshapes tender specifications toward software licences rather than detector heads.
Compliance cost is material. Type approval per platform per jurisdiction is estimated at USD 40,000-90,000 and 6-9 months, with renewal obligations every 3-5 years. For suppliers targeting multiple MEA states, cumulative approval spend can exceed USD 600,000 before a single unit ships.
Investment, M&A & Funding Activity in MEA Airport Passenger Screening Systems Industry Market
Capital formation in this industry is strategic rather than venture-driven.
Consolidation logic: large diversified defence and detection groups acquire component and software assets to sell integrated lanes. The rationale is margin mix - adding a 28-34% gross-margin imaging platform to a portfolio weighted toward 11-15% metal detectors lifts blended profitability by 3-5 percentage points.
Private equity interest centres on service and consumables businesses - calibration, trace-detection consumables, training - because these generate recurring revenue with 25-35% gross margins and limited regulatory exposure.
Sovereign and development funding: multilateral lenders and national development banks finance airport construction, which indirectly funds screening procurement. Projects tied to national aviation strategies in Saudi Arabia and Turkey are the largest single source of committed capital.
Venture activity is concentrated in automation and data: biometric touchpoints, remote screening software and artificial intelligence alarm-triage tools. Deal sizes typically range from USD 5 million to USD 40 million in Series A and B rounds.
Sub-segment attractiveness ranking: advanced imaging first, trace detection consumables second, software integration third, manual metal detection last.
Acquirers value installed-lane footprint over unit price leadership because the service annuity compounds with each installed base unit. Vendors holding more than 40% of revenue in service contracts command valuation multiples roughly 2-3 turns above hardware-only peers.
MEA Airport Passenger Screening Systems Industry Segmentation
1. Type
1.1. Metal Detectors
1.2. Full Body Scanners
1.3. Advanced Imaging Technology
MEA Airport Passenger Screening Systems Industry Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
MEA Airport Passenger Screening Systems Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 2.52% from 2020-2034
Segmentation
By Type
Metal Detectors
Full Body Scanners
Advanced Imaging Technology
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Metal Detectors
5.1.2. Full Body Scanners
5.1.3. Advanced Imaging Technology
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Metal Detectors
6.1.2. Full Body Scanners
6.1.3. Advanced Imaging Technology
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Metal Detectors
7.1.2. Full Body Scanners
7.1.3. Advanced Imaging Technology
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Metal Detectors
8.1.2. Full Body Scanners
8.1.3. Advanced Imaging Technology
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Metal Detectors
9.1.2. Full Body Scanners
9.1.3. Advanced Imaging Technology
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Metal Detectors
10.1.2. Full Body Scanners
10.1.3. Advanced Imaging Technology
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Rapiscan Systems (OSI Systems Inc )
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Garrett Electronics Inc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Leidos Inc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Vanderlande Industries
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. C E I A S p A
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Scarabee Aviation Group
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. SITA
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Kromek Group plc
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Elenium Automation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Nuctech Company Limite
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
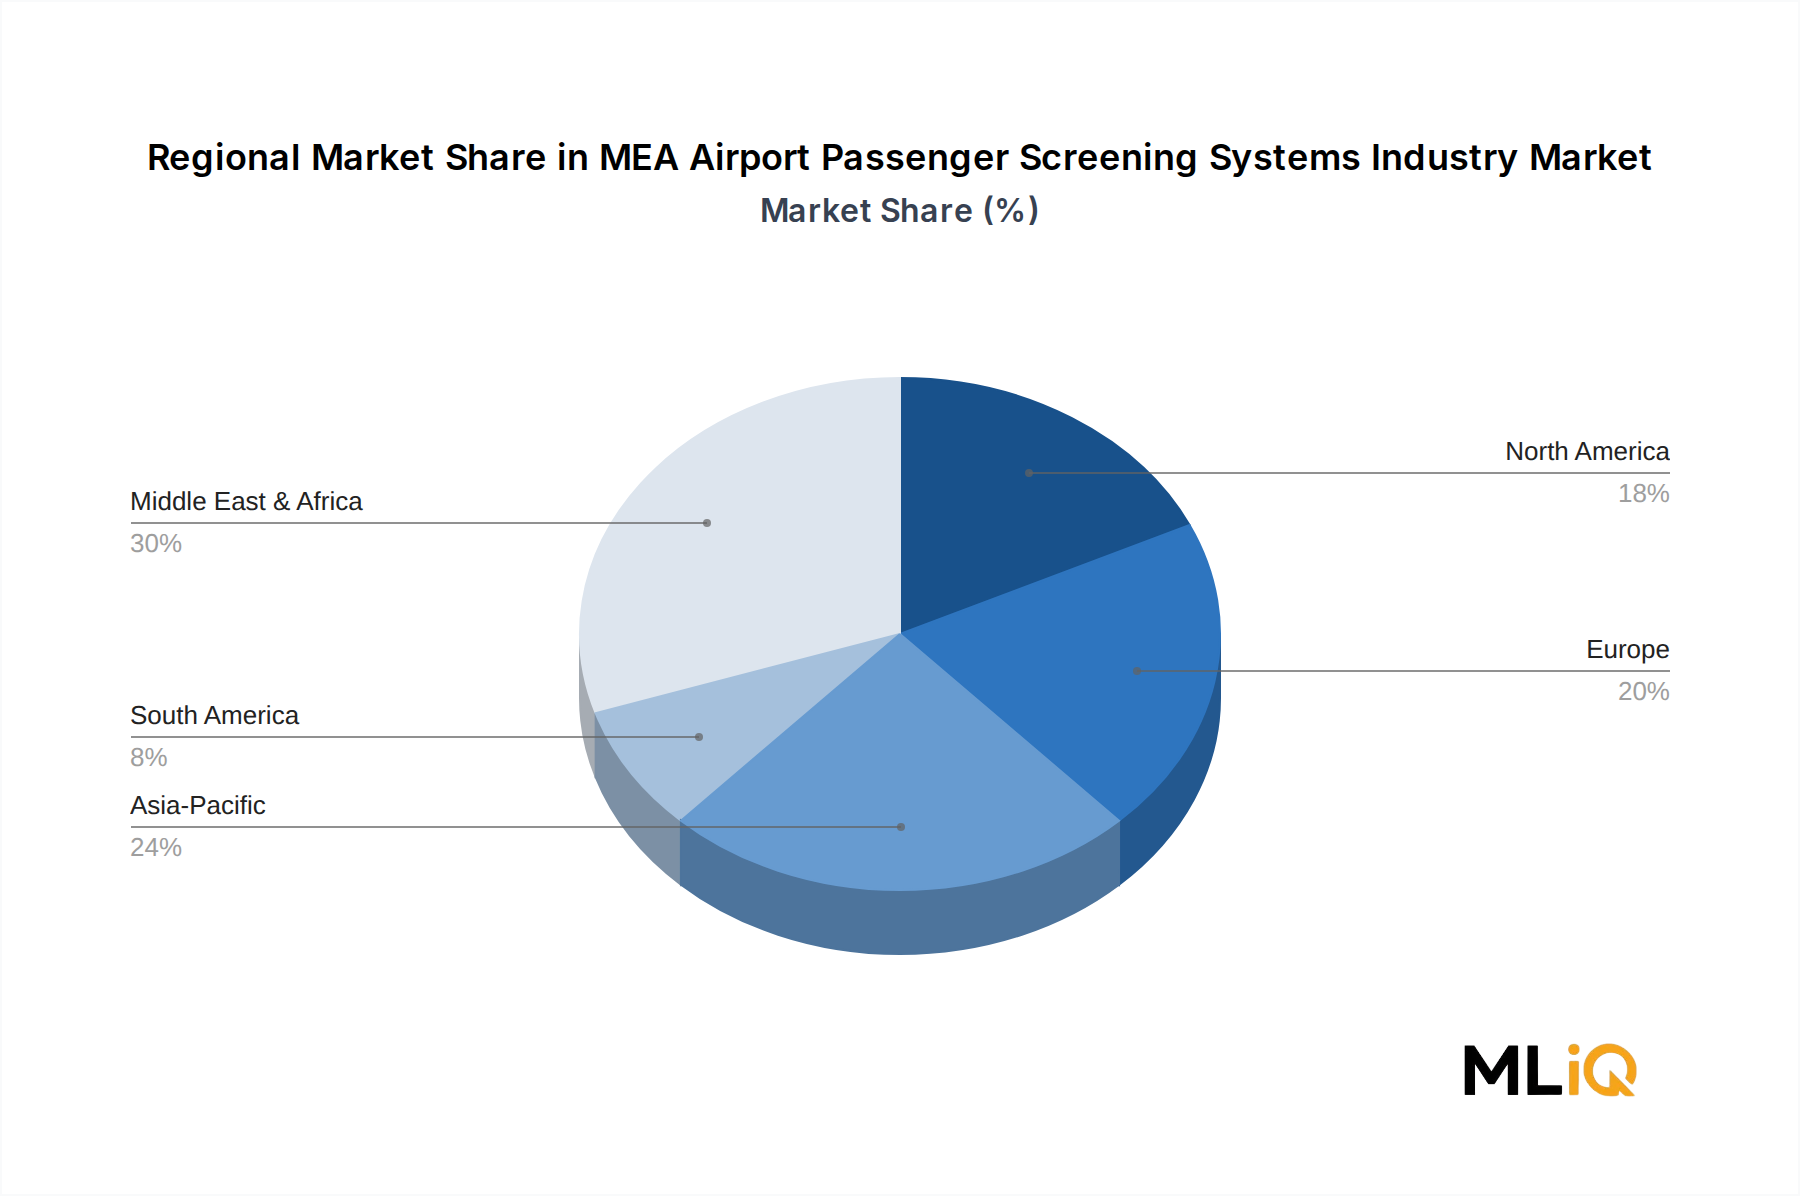
Figure 1: MEA Airport Passenger Screening Systems Industry Revenue Breakdown (millionusdmillion, %) by Region 2026 & 2034
Figure 2: North America MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Type 2026 & 2034
Figure 3: North America MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Type 2026 & 2034
Figure 4: North America MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Country 2026 & 2034
Figure 5: North America MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Country 2026 & 2034
Figure 6: South America MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Type 2026 & 2034
Figure 7: South America MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Type 2026 & 2034
Figure 8: South America MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Country 2026 & 2034
Figure 9: South America MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Type 2026 & 2034
Figure 11: Europe MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Type 2026 & 2034
Figure 12: Europe MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Country 2026 & 2034
Figure 13: Europe MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Type 2026 & 2034
Figure 15: Middle East & Africa MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Type 2026 & 2034
Figure 16: Middle East & Africa MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Country 2026 & 2034
Figure 17: Middle East & Africa MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Type 2026 & 2034
Figure 19: Asia Pacific MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Type 2026 & 2034
Figure 20: Asia Pacific MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion), by Country 2026 & 2034
Figure 21: Asia Pacific MEA Airport Passenger Screening Systems Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Type 2020 & 2034
Table 2: MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Region 2020 & 2034
Table 3: North America MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Type 2020 & 2034
Table 4: North America MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Country 2020 & 2034
Table 5: United States MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 6: Canada MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 7: Mexico MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 8: South America MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Type 2020 & 2034
Table 9: South America MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Country 2020 & 2034
Table 10: Brazil MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 11: Argentina MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 12: Rest of South America MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 13: Europe MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Type 2020 & 2034
Table 14: Europe MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Country 2020 & 2034
Table 15: United Kingdom MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 16: Germany MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 17: France MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 18: Italy MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 19: Spain MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 20: Russia MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 21: Benelux MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 22: Nordics MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 23: Rest of Europe MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 24: Middle East & Africa MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Type 2020 & 2034
Table 25: Middle East & Africa MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Country 2020 & 2034
Table 26: Turkey MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 27: Israel MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 28: GCC MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 29: North Africa MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 30: South Africa MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 31: Rest of Middle East & Africa MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 32: Asia Pacific MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Type 2020 & 2034
Table 33: Asia Pacific MEA Airport Passenger Screening Systems Industry Revenue millionusdmillion Forecast, by Country 2020 & 2034
Table 34: China MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 35: India MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 36: Japan MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 37: South Korea MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 38: ASEAN MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 39: Oceania MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Table 40: Rest of Asia Pacific MEA Airport Passenger Screening Systems Industry Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of the total data foundation, with the remaining 20-30% sourced from secondary research and industry benchmarking.
Direct interviews and structured surveys are conducted with five company types across the value chain: airport screening system OEMs supplying CT and X-ray checkpoint lanes; walk-through metal detector and millimetre-wave body scanner manufacturers; airport terminal contractors and baggage-handling integrators; trace-detection consumable and calibration service providers; and national civil aviation security regulators and airport authority procurement units.
Interviewee designations include Airport Security Equipment Procurement Director, Terminal Operations and Screening Lane Manager, Aviation Security Regulatory Compliance Lead, and Detection Systems R&D and Product Engineering Manager.
Interview programmes are supplemented by tender-document analysis, factory acceptance test records and lane-level deployment data supplied by airport operators.
We guarantee an estimated data accuracy level of 85-90%, with confidence intervals published alongside each forecast table.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Airport Security Equipment Procurement Directors
28%
Terminal Operations and Screening Lane Managers
24%
Aviation Security Regulatory Compliance Leads
18%
Detection Systems R&D and Product Engineering Managers
16%
Border, Customs and Civil Aviation Program Officers
14%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Airport screening system OEMs (CT and X-ray lanes)
30%
Airport authorities and terminal operators
22%
Detection component and sensor suppliers
18%
Systems integrators and baggage-handling vendors
15%
Regulatory, standards and certification bodies
15%
Secondary Research & Industry Benchmarking
Secondary research validates primary findings against published filings, regulatory dockets and trade press, and is cross-referenced using standard financial databases including Bloomberg, Factiva, Hoovers and PitchBook.
Government and standards sources include the International Civil Aviation Organization (ICAO), the US Transportation Security Administration (TSA), and the European Civil Aviation Conference (ECAC).
Trade association benchmarking draws on Airports Council International (ACI World) and the International Air Transport Association (IATA) for traffic, capacity and capital expenditure data.
Only .gov, .org, regulator and trade association sources are used for statutory and compliance inputs; market research websites are excluded from the source base.
Every report is updated to the date of purchase, so all tables, vendor profiles and forecast baselines reflect the most recent available filings and tender outcomes.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously, then reconciled through multi-level data triangulation across segment, product and geography layers.
The bottom-up model is built from specific quantitative inputs: the number of screening lanes per terminal by region and airport tier; the installed-base replacement cycle for X-ray, CT and portal equipment (5-10 years by platform); average selling price per lane type (USD 4,500-12,000 for metal detectors, approximately USD 130,000 for millimetre-wave body scanners, and USD 320,000-520,000 for CT lanes); and annual passenger throughput per lane under ICAO guidance.
The top-down model anchors total market value to airport capital expenditure on security systems, cross-checked against public airport expansion budgets in Egypt, Turkey, Saudi Arabia and the GCC.
Regional splits are validated against passenger traffic growth of approximately 5.4% in Africa and above-2019 recovery levels at Middle East hubs, producing a base-year valuation of USD 152.17 million for 2025 and a 2.52% CAGR for 2026-2034.
Data Accuracy & Quality Check
A guaranteed estimated data accuracy level of 85-90% is enforced through mandatory multi-level data triangulation, in which no single-source figure is accepted without corroboration from at least two independent primary or secondary inputs.
Quality control includes sanity checks against historical shipment volumes, price-per-lane ranges and installed-base replacement math to detect implausible growth or share shifts.
Segment and regional forecasts are stress-tested against alternate currency, traffic and procurement-timing scenarios before publication.
Any revision after publication is versioned and dated, and the entire dataset is refreshed to the date of purchase so subscribers always hold the current baseline.
Frequently Asked Questions
1. How do regulatory frameworks affect equipment approval in the MEA Airport Passenger Screening Systems Industry Market?
Every national regulator maintains its own acceptance list, so a platform certified in the UAE may still require fresh type approval in Egypt or Nigeria. Type approval costs are typically USD 40,000 to 90,000 per platform per jurisdiction and take 6 to 9 months, with renewal obligations every 3 to 5 years. ICAO Annex 17 sets the baseline screening obligation, while ECAC Common Evaluation Process designations and the US TSA Qualified Products List influence specifications that MEA operators borrow from.
2. What technological innovations and R&D trends are reshaping airport passenger screening?
Computed tomography has become the reference platform for checkpoint and checked-baggage lanes because it resolves liquid and powder threats that dual-energy X-ray cannot. Vendors are investing in automated threat recognition software that allows alarm resolution without a human image reviewer, cutting staffing by 1 to 2 operators per lane. Solid-state detector development by suppliers such as Kromek Group plc targets smaller, lower-dose sensor packages for next-generation lanes.
3. What are the major challenges and supply-chain risks facing vendors in this market?
Currency depreciation in Egypt, Turkey and Nigeria raised imported equipment costs by 30% to 60% in local terms between 2022 and 2024, forcing phased tendering. Tender cycles of 12 to 24 months stretch vendor working capital, and a regional shortfall of individually licensed screening officers delays lane activation by 3 to 6 months after installation. Divergent national acceptance lists add compliance cost before any unit ships.
4. How do raw material sourcing and component supply chains influence screening system pricing?
Cost structure is dominated by X-ray generators, scintillator materials such as cesium iodide and gadolinium oxysulfide, and detector arrays, all of which carry semiconductor-style lead times. Shielding assemblies depend on lead, tungsten and barium-based compounds, so restrictions under RoHS and REACH push manufacturers toward alternative chemistries and raise enclosure costs. Multi-zone coil assemblies and millimetre-wave transceiver modules add further exposure to rare-earth magnet and radio-frequency component availability.
5. Which region is the fastest-growing and where are the emerging geographic opportunities?
Middle East & Africa is the fastest-growing corridor at a projected 3.85% CAGR, roughly 1.3 percentage points above the global average, supported by capacity programmes adding more than 120 million annual passenger seats this decade. Turkey offers the largest single pipeline through the Antalya expansion from 40 million to 80 million passengers, while Saudi Arabia targets 330 million annual passengers by 2030. Sub-Saharan Africa outside South Africa remains the most under-equipped geography in absolute terms.
6. What are the primary growth drivers and demand catalysts in this market?
Airport Terminal Construction Market activity across Egypt, Turkey, Saudi Arabia and the GCC is the leading catalyst, since every 10 million incremental annual passengers requires roughly 8 to 12 additional screening lanes under ICAO throughput guidance. Replacement demand is equally significant: about 60% of 2026-2034 volume replaces equipment installed between 2012 and 2018. Service, calibration and consumables now contribute an estimated 27% of vendor revenue, up from 21% in 2020, stabilising cash flow through traffic cycles.