Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Attitude Control in Satellite Communication Market 10.36 CAGR
Attitude Control in Satellite Communication Market
Attitude Control in Satellite Communication Market 10.36 CAGR
Attitude Control in Satellite Communication Market by Application (Communication, Earth Observation, Navigation, Space Observation, Others), by Satellite Mass (10-100kg, 100-500kg, 500-1000kg, Below 10 Kg, above 1000kg), by Orbit Class (GEO, LEO, MEO), by End User (Commercial, Military & Government, Other), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 197
Key Insights & Executive Summary: Attitude Control in Satellite Communication Market
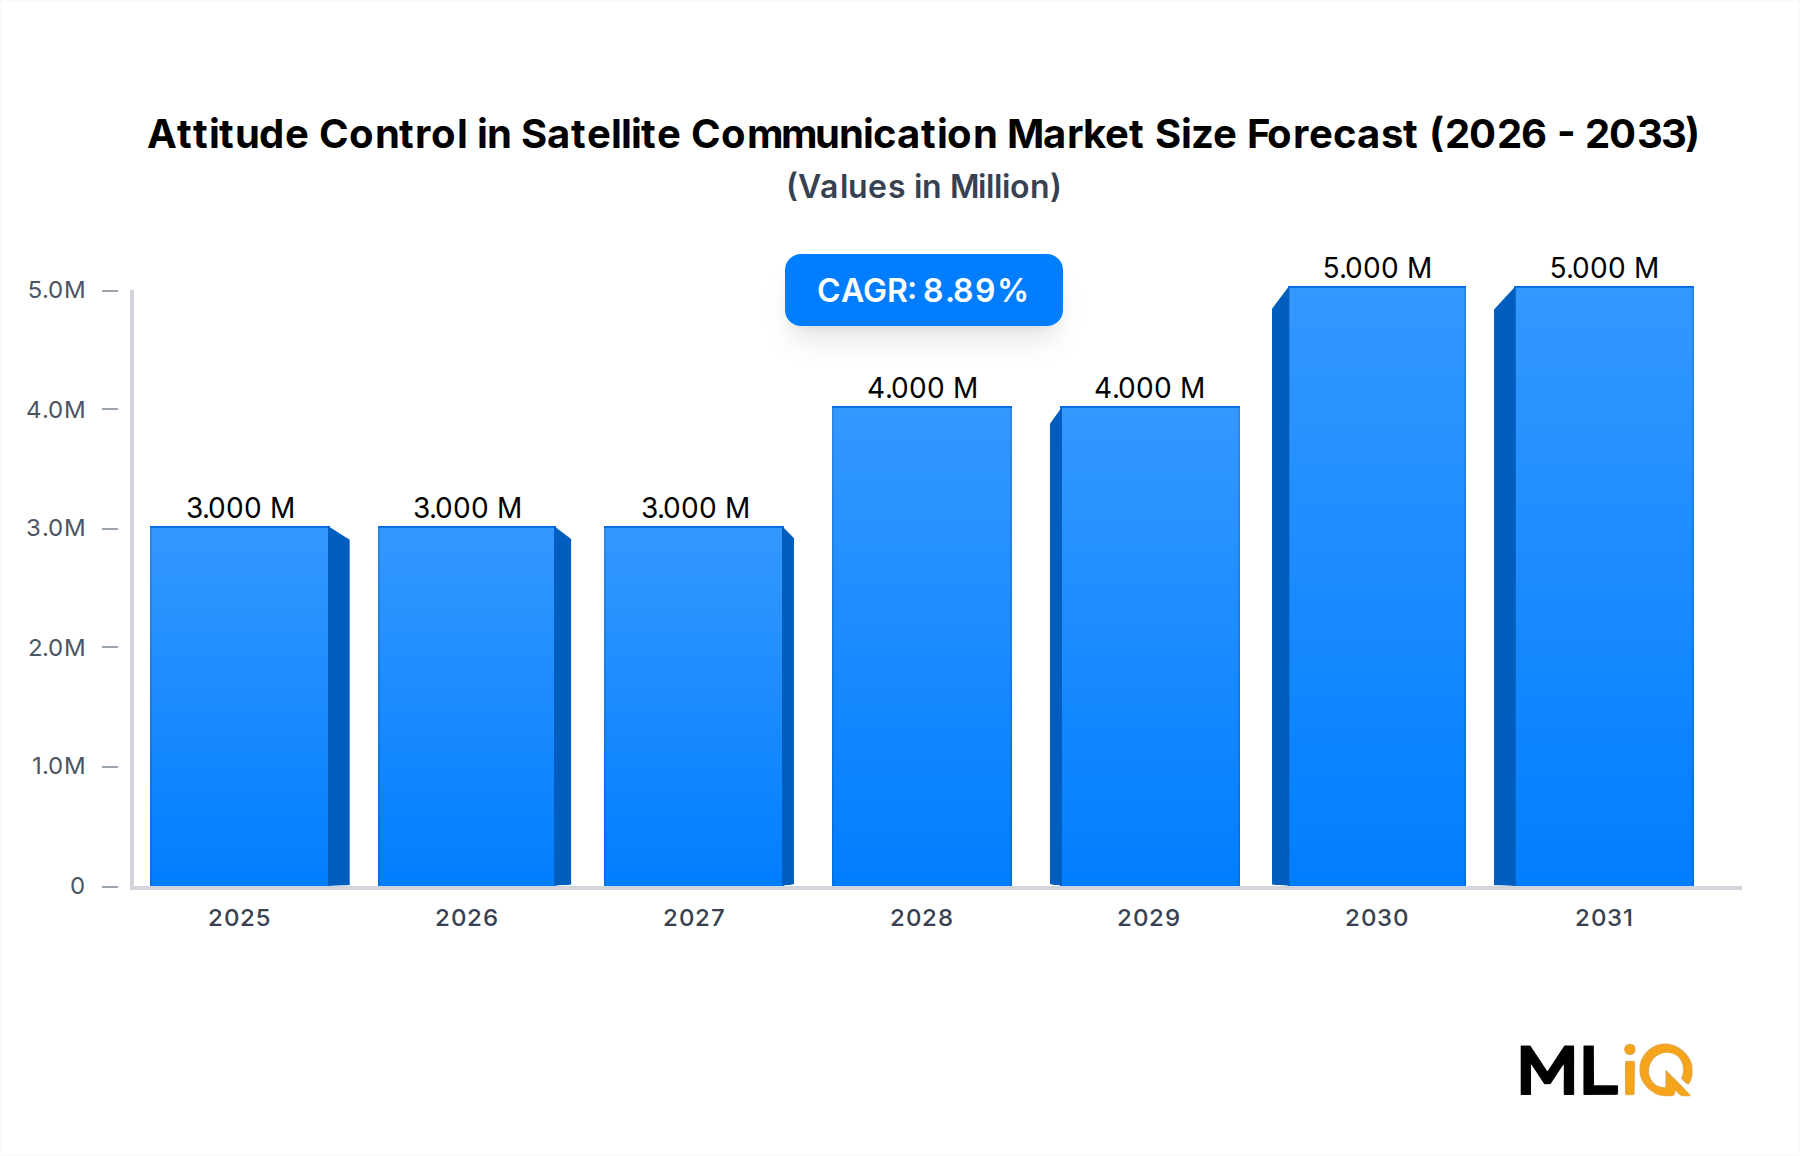
The Attitude Control in Satellite Communication Market is valued at $2.87 billion in 2025 and is projected to reach $6.32 billion by 2033, expanding at a 10.36% CAGR. This growth is fueled by the deployment of LEO broadband constellations, military satellite modernization, and the increasing demand for precise pointing in small satellites.
Attitude Control in Satellite Communication Market Size (In Million)
5.0M
4.0M
3.0M
2.0M
1.0M
0
3.000 M
2025
3.000 M
2026
3.000 M
2027
4.000 M
2028
4.000 M
2029
5.000 M
2030
5.000 M
2031
Communication applications dominate with a 38% share, driven by the need for stable links in the LEO Satellite Communication Market. The Satellite Attitude Control System Market is also benefiting from advances in star trackers and reaction wheels.
Key macro drivers include:
LEO constellation launches: Over 2,500 small satellites launched annually.
Defense budgets: $12 billion allocated to space-based communication in 2024.
Miniaturization: AOCS components now weigh less than 500 grams.
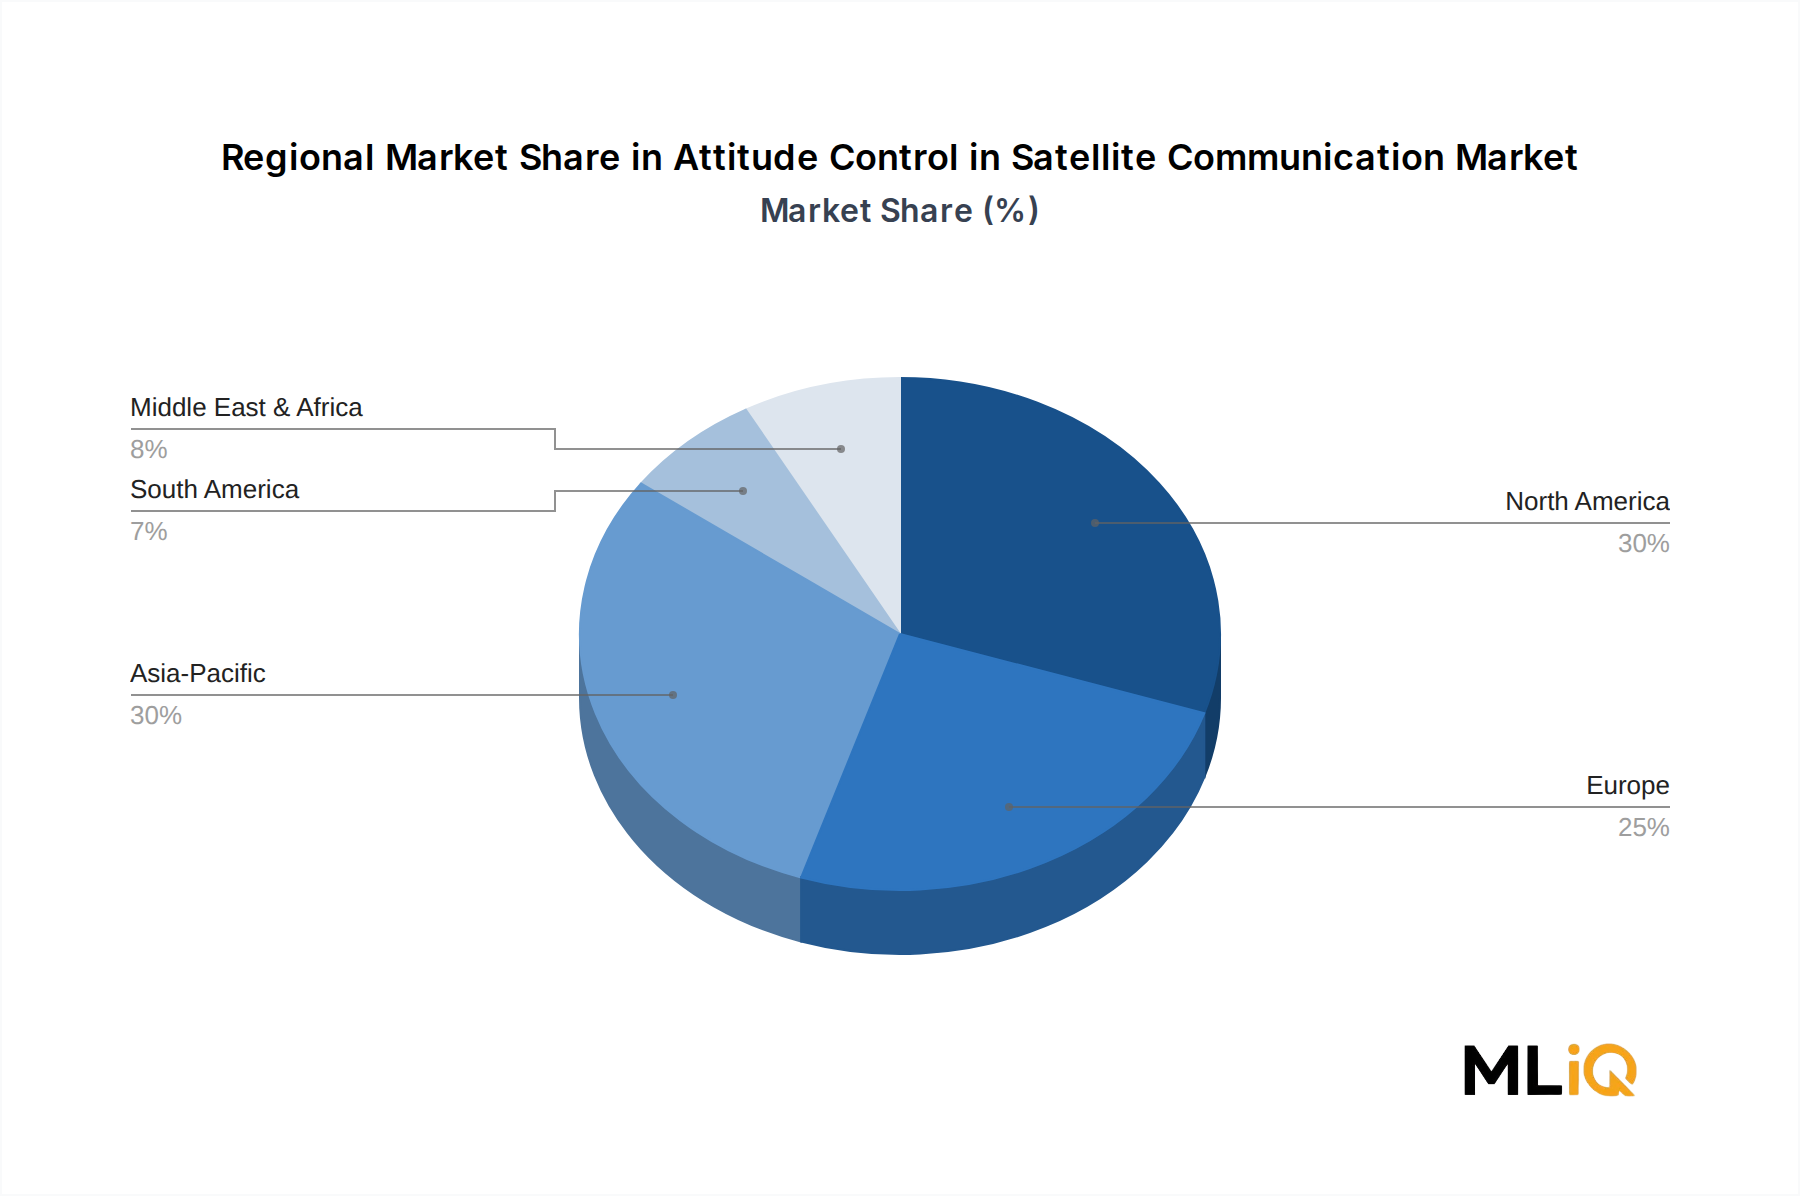
North America leads with 30% revenue share, followed by Asia-Pacific at 30% and Europe at 25%. The Spacecraft Attitude Determination and Control Market is witnessing a shift toward software-defined architectures.
Segment Deep-Dive: Communication Application Dominance in Attitude Control in Satellite Communication Market
Segment Analysis Matrix
CAGR (%)
Market Share (%)
Key Demand Driver
Communication
11.2
38
LEO broadband constellations
Earth Observation
9.8
24
Climate monitoring and defense
Navigation
8.5
18
GNSS augmentation and autonomy
Communication Segment Dynamics
The Communication segment is the largest revenue generator, accounting for $1.09 billion in 2025. Growth is primarily from LEO constellations requiring high-accuracy attitude control for inter-satellite links. The Small Satellite AOCS Market is expanding as operators like SpaceX and OneWeb deploy thousands of satellites.
Sub-segment and Margin Pressures
LEO orbit class represents 45% of AOCS demand, growing at 12.1% CAGR.
100-500kg satellite mass is the dominant mass category, with 40% share.
The Military Satellite Communication Market demands radiation-hardened AOCS, commanding a 25% price premium. In contrast, commercial operators prioritize cost and lead time.
Primary Market Drivers & Growth Restraints in Attitude Control in Satellite Communication Market
Market Dynamics Impact Analysis
Description
Impact Level
Timeline
Driver
LEO constellation deployments
High
Long term
Driver
Military satellite modernization
High
Short term
Driver
Small satellite launch rate
High
Short term
Restraint
High cost of radiation-hardened components
Medium
Long term
Restraint
Regulatory hurdles for spectrum allocation
Medium
Short term
Restraint
Supply chain constraints for star trackers
Medium
Short term
Quantitative evaluation:
LEO launches are projected to grow from 1,800 in 2024 to 3,500 by 2030.
The Reaction Wheel Market is expected to reach $1.2 billion by 2030, at 9.5% CAGR.
The Star Tracker Market is projected to reach $2.1 billion by 2030, at 11% CAGR, driven by demand for high-precision attitude determination.
Export controls on AOCS components add 6-9 months to procurement cycles.
Competitive Ecosystem & Key Vendor Profiles: Attitude Control in Satellite Communication Market
Vendor Benchmarking Matrix
Core Strength
Target Audience
Market Position
Jena-Optronik
Star trackers and AOCS sensors
Commercial and government
Leader
OHB SE
Integrated satellite systems
Institutional and commercial
Leader
AAC Clyde Space
Small satellite platforms
Commercial smallsat operators
Challenger
NewSpace Systems
Reaction wheels and momentum control
LEO constellation operators
Challenger
SENER Group
AOCS mechanisms and actuators
Space agencies and primes
Niche
Bradford Engineering
Attitude control thrusters
Satellite primes
Niche
Innovative Solutions in Space
CubeSat AOCS kits
Academic and smallsat
Niche
Sitael
Electric propulsion and AOCS
European institutional
Challenger
Thale
AOCS components
European satellite builders
Niche
Jena-Optronik: Supplies ASTRO CL star trackers to Airbus OneWeb and Maxar; selected for NASA Artemis I.
OHB SE: Integrates AOCS into full satellite buses for European institutional and commercial customers.
AAC Clyde Space: Provides turnkey small satellite platforms with embedded AOCS for LEO missions.
NewSpace Systems: Specializes in reaction wheels and momentum control for high-volume LEO constellations.
SENER Group: Develops precision mechanisms and actuators for space agencies and prime contractors.
Bradford Engineering: Offers attitude control thrusters for satellite primes in Europe.
Innovative Solutions in Space: Delivers CubeSat AOCS kits to academic and smallsat customers.
Sitael: Combines electric propulsion with AOCS for European institutional satellites.
Thale: Supplies AOCS components to European satellite builders.
Strategic Milestones & Recent Developments in Attitude Control in Satellite Communication Market
Latest Strategic Moves
Company
Event Type
Impact
Feb 2023
Jena-Optronik
Partnership
Selected by Airbus OneWeb for ASTRO CL AOCS sensors
Dec 2022
Jena-Optronik
Partnership
Maxar selects ASTRO CL star trackers for proliferated LEO
Nov 2022
Jena-Optronik
Launch
NASA Artemis I equipped with two star sensors
February 2023: Jena-Optronik announced that it has been selected by Airbus OneWeb Satellites to provide the ASTRO CL AOCS sensor for the ARROW family of small satellites. This contract underscores the growing demand for compact, high-performance attitude control in LEO constellations.
December 2022: ASTRO CL, the smallest member of Jena-Optronik's ASTRO star tracker family, was chosen to support Maxar's new proliferated LEO satellite platform. Each satellite will carry two ASTRO CL star trackers for guidance, navigation, and control.
November 2022: NASA's Artemis I mission was equipped with two star sensors by Jena-Optronik, ensuring precise alignment on its way to the Moon. This demonstrates the critical role of attitude control in deep space communication.
Regional Market Analysis & Growth Corridors for Attitude Control in Satellite Communication Market
Regional Growth Comparison
Projected CAGR (%)
Base Year Valuation ($ billion)
Primary Catalyst
Regulatory Stringency
North America
9.8
0.86
Defense and commercial LEO
High
Europe
10.1
0.72
Institutional programs and smallsat
High
Asia-Pacific
11.5
0.86
National space programs and commercial
Medium
LAMEA
10.5
0.43
Emerging satellite markets
Low to Medium
Asia-Pacific is the fastest-growing region, driven by China's 1,000+ satellite constellation plans and India's commercial space sector. North America remains the most mature market, with 30% share, due to high defense spending and the presence of leading AOCS vendors.
Europe follows closely, with 25% share, supported by ESA programs and strong smallsat manufacturing. The Inertial Measurement Unit Market is also expanding in Europe for precise attitude determination.
LAMEA is an emerging region, with Brazil and the UAE investing in communication satellites. Regulatory frameworks are less stringent, enabling faster deployment.
Investment, M&A & Funding Activity in Attitude Control in Satellite Communication Market
M&A activity has intensified as larger aerospace firms acquire nimble AOCS technology providers. In 2023, Redwire acquired Roccor to bolster its star tracker and deployable systems portfolio. AAC Clyde Space acquired Hyperion Technologies in 2022 to integrate AOCS components.
Private equity and venture capital investments focus on:
Small Satellite AOCS Market: $150 million raised in 2024 across 12 startups.
Reaction Wheel Market: $80 million in Series B rounds for miniaturized wheels.
Strategic partnerships are common, such as Jena-Optronik's supply agreements with Airbus OneWeb and Maxar. High-growth sub-segments include software-defined AOCS and radiation-hardened electronics.
Customer Segmentation & Buying Behavior in Attitude Control in Satellite Communication Market
End-user base:
Commercial (60%): Driven by LEO constellation operators, prioritizing cost, lead time, and mass.
Military & Government (30%): Require radiation-hardened, ITAR-free components, with high price elasticity.
Other (10%): Academic and research institutions, often purchasing CubeSat AOCS kits.
Procurement channels:
Direct from OEMs for custom AOCS.
Distributors for off-the-shelf components.
Government contracts through prime contractors.
Buyer expectations have shifted toward modular, plug-and-play AOCS that reduce integration time. Digital purchasing habits include online configurators and rapid quotes. The Satellite Bus Market is increasingly bundled with AOCS, influencing buying decisions.
Attitude Control in Satellite Communication Market Segmentation
1. Application
1.1. Communication
1.2. Earth Observation
1.3. Navigation
1.4. Space Observation
1.5. Others
2. Satellite Mass
2.1. 10-100kg
2.2. 100-500kg
2.3. 500-1000kg
2.4. Below 10 Kg
2.5. above 1000kg
3. Orbit Class
3.1. GEO
3.2. LEO
3.3. MEO
4. End User
4.1. Commercial
4.2. Military & Government
4.3. Other
Attitude Control in Satellite Communication Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Attitude Control in Satellite Communication Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.36% from 2020-2034
Segmentation
By Application
Communication
Earth Observation
Navigation
Space Observation
Others
By Satellite Mass
10-100kg
100-500kg
500-1000kg
Below 10 Kg
above 1000kg
By Orbit Class
GEO
LEO
MEO
By End User
Commercial
Military & Government
Other
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Communication
5.1.2. Earth Observation
5.1.3. Navigation
5.1.4. Space Observation
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Satellite Mass
5.2.1. 10-100kg
5.2.2. 100-500kg
5.2.3. 500-1000kg
5.2.4. Below 10 Kg
5.2.5. above 1000kg
5.3. Market Analysis, Insights and Forecast - by Orbit Class
5.3.1. GEO
5.3.2. LEO
5.3.3. MEO
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Commercial
5.4.2. Military & Government
5.4.3. Other
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. South America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Communication
6.1.2. Earth Observation
6.1.3. Navigation
6.1.4. Space Observation
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Satellite Mass
6.2.1. 10-100kg
6.2.2. 100-500kg
6.2.3. 500-1000kg
6.2.4. Below 10 Kg
6.2.5. above 1000kg
6.3. Market Analysis, Insights and Forecast - by Orbit Class
6.3.1. GEO
6.3.2. LEO
6.3.3. MEO
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Commercial
6.4.2. Military & Government
6.4.3. Other
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Communication
7.1.2. Earth Observation
7.1.3. Navigation
7.1.4. Space Observation
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Satellite Mass
7.2.1. 10-100kg
7.2.2. 100-500kg
7.2.3. 500-1000kg
7.2.4. Below 10 Kg
7.2.5. above 1000kg
7.3. Market Analysis, Insights and Forecast - by Orbit Class
7.3.1. GEO
7.3.2. LEO
7.3.3. MEO
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Commercial
7.4.2. Military & Government
7.4.3. Other
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Communication
8.1.2. Earth Observation
8.1.3. Navigation
8.1.4. Space Observation
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Satellite Mass
8.2.1. 10-100kg
8.2.2. 100-500kg
8.2.3. 500-1000kg
8.2.4. Below 10 Kg
8.2.5. above 1000kg
8.3. Market Analysis, Insights and Forecast - by Orbit Class
8.3.1. GEO
8.3.2. LEO
8.3.3. MEO
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Commercial
8.4.2. Military & Government
8.4.3. Other
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Communication
9.1.2. Earth Observation
9.1.3. Navigation
9.1.4. Space Observation
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Satellite Mass
9.2.1. 10-100kg
9.2.2. 100-500kg
9.2.3. 500-1000kg
9.2.4. Below 10 Kg
9.2.5. above 1000kg
9.3. Market Analysis, Insights and Forecast - by Orbit Class
9.3.1. GEO
9.3.2. LEO
9.3.3. MEO
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Commercial
9.4.2. Military & Government
9.4.3. Other
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Communication
10.1.2. Earth Observation
10.1.3. Navigation
10.1.4. Space Observation
10.1.5. Others
10.2. Market Analysis, Insights and Forecast - by Satellite Mass
10.2.1. 10-100kg
10.2.2. 100-500kg
10.2.3. 500-1000kg
10.2.4. Below 10 Kg
10.2.5. above 1000kg
10.3. Market Analysis, Insights and Forecast - by Orbit Class
10.3.1. GEO
10.3.2. LEO
10.3.3. MEO
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Commercial
10.4.2. Military & Government
10.4.3. Other
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AAC Clyde Space
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Bradford Engineering BV
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Innovative Solutions in Space BV
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Jena-Optronik
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. NewSpace Systems
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. OHB SE
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. SENER Group
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Sitael S p A
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Thale
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Attitude Control in Satellite Communication Market Revenue Breakdown (billionusdbillion, %) by Product 2026 & 2034
Figure 2: Attitude Control in Satellite Communication Market Value Share (%), by Application 2026 & 2034
Figure 3: Attitude Control in Satellite Communication Market Value Share (%), by Satellite Mass 2026 & 2034
Figure 4: Attitude Control in Satellite Communication Market Value Share (%), by Orbit Class 2026 & 2034
Figure 5: Attitude Control in Satellite Communication Market Value Share (%), by End User 2026 & 2034
Figure 6: Attitude Control in Satellite Communication Market Share (%) by Company 2026
List of Tables
Table 1: Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 2: Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Satellite Mass 2020 & 2034
Table 3: Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Orbit Class 2020 & 2034
Table 4: Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by End User 2020 & 2034
Table 5: Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Region 2020 & 2034
Table 6: North America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 7: North America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Satellite Mass 2020 & 2034
Table 8: North America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Orbit Class 2020 & 2034
Table 9: North America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by End User 2020 & 2034
Table 10: North America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 11: United States Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 12: Canada Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 13: Mexico Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 14: South America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 15: South America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Satellite Mass 2020 & 2034
Table 16: South America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Orbit Class 2020 & 2034
Table 17: South America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by End User 2020 & 2034
Table 18: South America Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 19: Brazil Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 20: Argentina Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 21: Rest of South America Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 22: Europe Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 23: Europe Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Satellite Mass 2020 & 2034
Table 24: Europe Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Orbit Class 2020 & 2034
Table 25: Europe Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by End User 2020 & 2034
Table 26: Europe Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 27: United Kingdom Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 28: Germany Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 29: France Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 30: Italy Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 31: Spain Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 32: Russia Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 33: Benelux Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 34: Nordics Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 35: Rest of Europe Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 36: Middle East & Africa Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 37: Middle East & Africa Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Satellite Mass 2020 & 2034
Table 38: Middle East & Africa Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Orbit Class 2020 & 2034
Table 39: Middle East & Africa Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by End User 2020 & 2034
Table 40: Middle East & Africa Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 41: Turkey Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 42: Israel Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 43: GCC Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 44: North Africa Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 45: South Africa Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 46: Rest of Middle East & Africa Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 47: Asia Pacific Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 48: Asia Pacific Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Satellite Mass 2020 & 2034
Table 49: Asia Pacific Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Orbit Class 2020 & 2034
Table 50: Asia Pacific Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by End User 2020 & 2034
Table 51: Asia Pacific Attitude Control in Satellite Communication Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 52: China Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 53: India Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 54: Japan Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 55: South Korea Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 56: ASEAN Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 57: Oceania Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 58: Rest of Asia Pacific Attitude Control in Satellite Communication Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of data collection, with interviews and surveys of AOCS Lead Engineers, Satellite Procurement Managers, Space Systems Program Directors, and GNC Specialists.
We engage 4-5 company types: AOCS component OEMs, star tracker and reaction wheel manufacturers, small satellite bus integrators, AOCS software developers, and satellite constellation operators.
We consult industry associations and regulatory bodies: International Astronautical Federation (IAF), American Institute of Aeronautics and Astronautics (AIAA), European Space Agency (ESA), and FAA Office of Commercial Space Transportation.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
AOCS Lead Engineer
30%
Satellite Procurement Manager
25%
Space Systems Program Director
25%
GNC Specialist
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
AOCS Component OEMs
30%
Star Tracker and Reaction Wheel Manufacturers
25%
Small Satellite Bus Integrators
20%
AOCS Software Developers
15%
Satellite Constellation Operators
10%
Secondary Research & Industry Benchmarking
Secondary research comprises 20-30% of data collection, using Bloomberg, Factiva, Hoovers, and PitchBook for financial data.
We cite .gov, .org, and trade association sources, including ESA and AIAA.
Every report is updated to the date of purchase.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up calculation uses quantitative metrics: number of active LEO satellites, average AOCS cost per satellite, satellite launch rate per year, and reaction wheel replacement cycles.
Top-down uses regional space budgets and constellation investment forecasts.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90%.
We cross-validate primary interview data with secondary sources.
Final estimates are reviewed by senior analysts.
Frequently Asked Questions
1. What technological innovations are shaping the Attitude Control in Satellite Communication Market?
Miniaturized star trackers and reaction wheels now enable sub-0.1-degree pointing accuracy, critical for LEO inter-satellite links. Software-defined AOCS architectures allow in-orbit reprogramming, reducing hardware swaps. Jena-Optronik's ASTRO CL star tracker, selected for Airbus OneWeb satellites, exemplifies this trend.
2. What are the main barriers to entry in the Attitude Control in Satellite Communication Market?
High R&D costs for radiation-hardened components and stringent qualification cycles (often 3-5 years) deter new entrants. Established vendors like OHB SE and Jena-Optronik hold proprietary algorithms and flight heritage. Supply chain constraints for star trackers and reaction wheels further limit competition.
3. Which end-user industries drive demand in the Attitude Control in Satellite Communication Market?
Commercial LEO constellation operators account for 60% of demand, followed by military and government at 30%. Earth observation and navigation satellite makers rely on AOCS for precise pointing. Academic CubeSat missions represent a smaller but growing segment.
4. Who are the leading companies in the Attitude Control in Satellite Communication Market?
Jena-Optronik leads in star trackers with contracts from Airbus OneWeb, Maxar, and NASA Artemis I. OHB SE dominates integrated satellite systems in Europe. AAC Clyde Space and NewSpace Systems are key challengers in small satellite AOCS, while SENER Group and Bradford Engineering occupy niche positions.
5. Which region dominates the Attitude Control in Satellite Communication Market and why?
North America holds the largest share at 30%, driven by high defense spending and major commercial LEO constellations like SpaceX's Starlink. The presence of leading AOCS vendors and favorable regulatory frameworks further cement its dominance. Asia-Pacific is the fastest-growing region, with an 11.5% CAGR.
6. What are the primary growth drivers in the Attitude Control in Satellite Communication Market?
The deployment of over 2,500 small satellites annually and military satellite modernization programs are key catalysts. Increasing demand for high-accuracy pointing in LEO broadband constellations and Earth observation drives AOCS adoption. Falling component prices and miniaturization expand addressable markets.