Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
UAV Flight Training and Simulation Market 17.95% CAGR
UAV Flight Training and Simulation Market
UAV Flight Training and Simulation Market 17.95% CAGR
UAV Flight Training and Simulation Market by Application (Military and Law Enforcement, Civil and Commercial), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: UAV Flight Training and Simulation Market
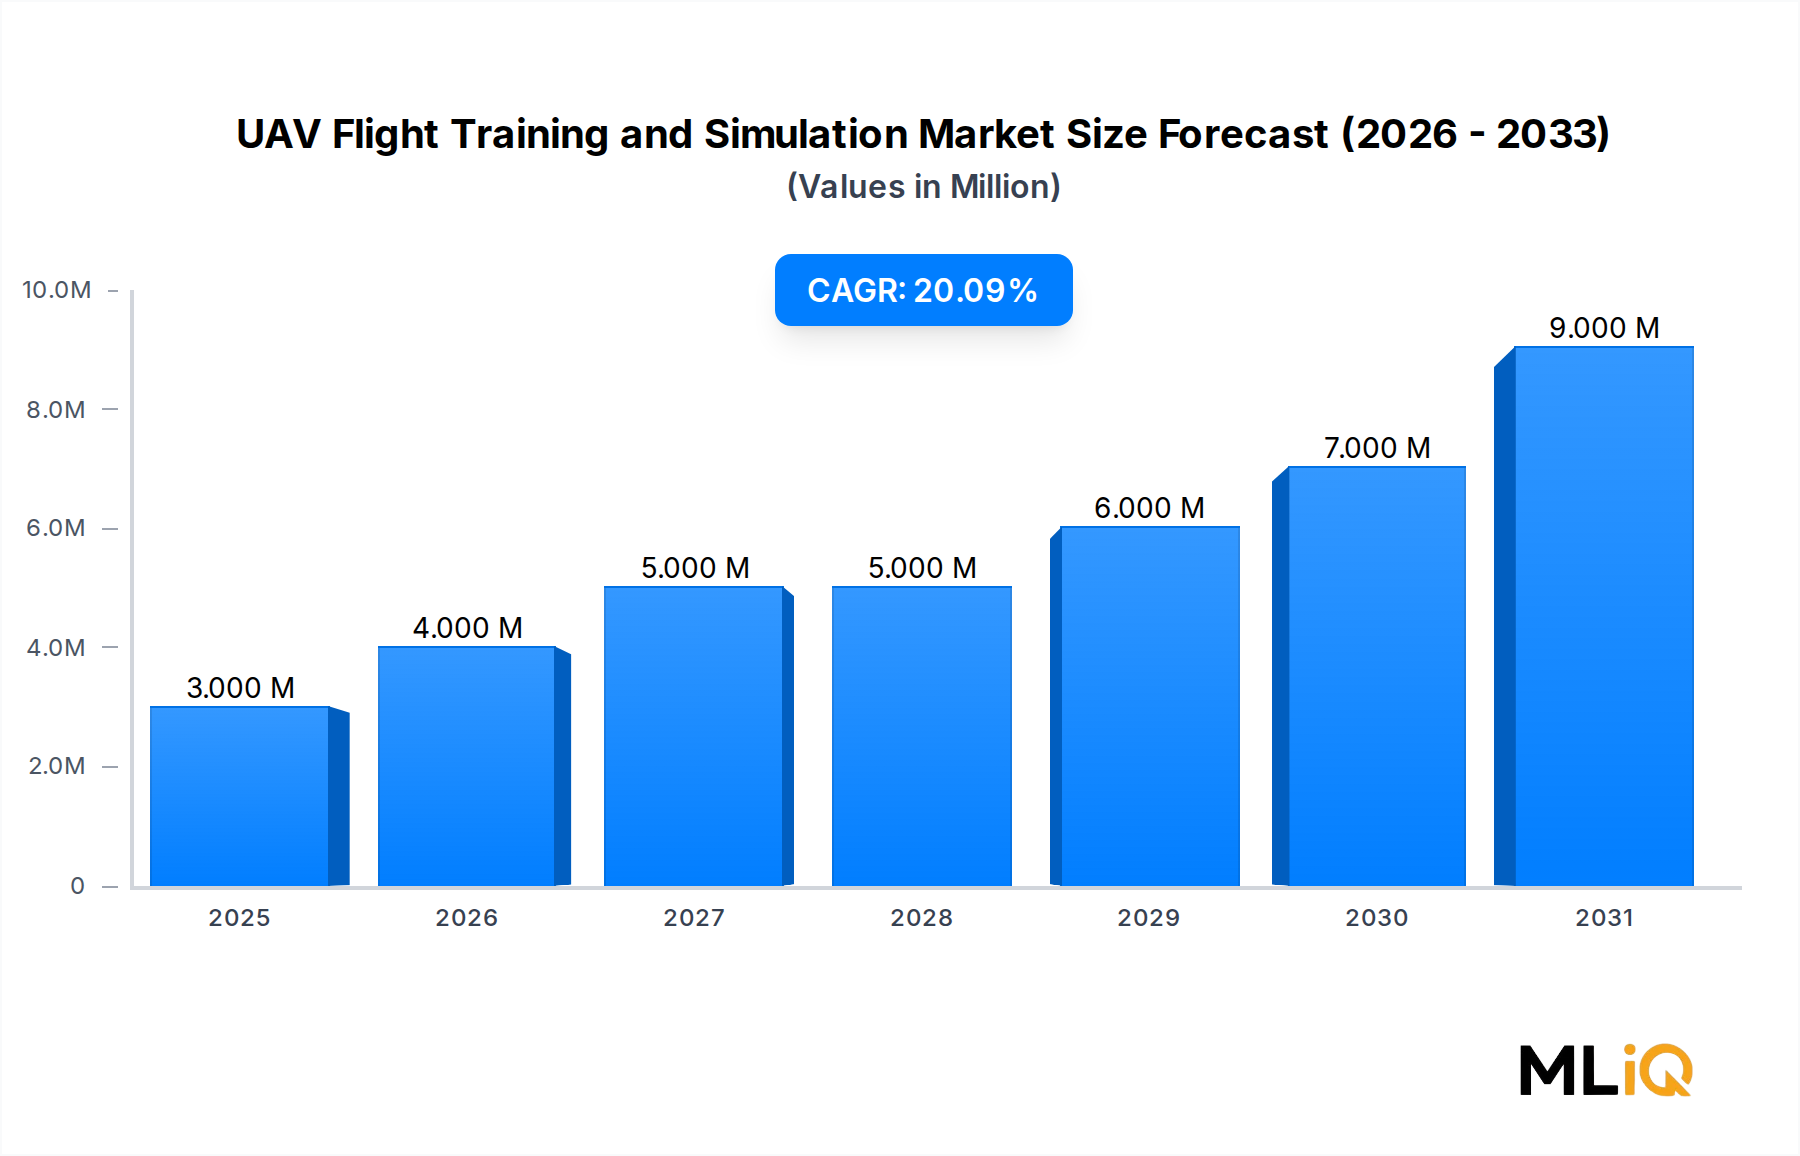
UAV Flight Training and Simulation Market Size (In Million)
10.0M
8.0M
6.0M
4.0M
2.0M
0
3.000 M
2025
4.000 M
2026
5.000 M
2027
5.000 M
2028
6.000 M
2029
7.000 M
2030
9.000 M
2031
Market at a Glance
The UAV Flight Training and Simulation Market is valued at $3.26 billion in 2025 and is projected to reach $12.20 billion by 2033, expanding at a 17.95% CAGR. This growth is embedded within the broader Aerospace and Defense Training Market, where simulation adoption reduces live-flight costs and risk. Military UAV Training Market demand remains anchored by defense budgets, while the Commercial UAV Training Market accelerates due to Part 107 recurrent certification and BVLOS operations.
Military and law enforcement accounts for an estimated 62% of 2025 revenue, driven by operator readiness for ISR and combat UAVs.
Civil and commercial is the faster-growing segment at 20.5% CAGR, supported by delivery, inspection, and public safety use cases.
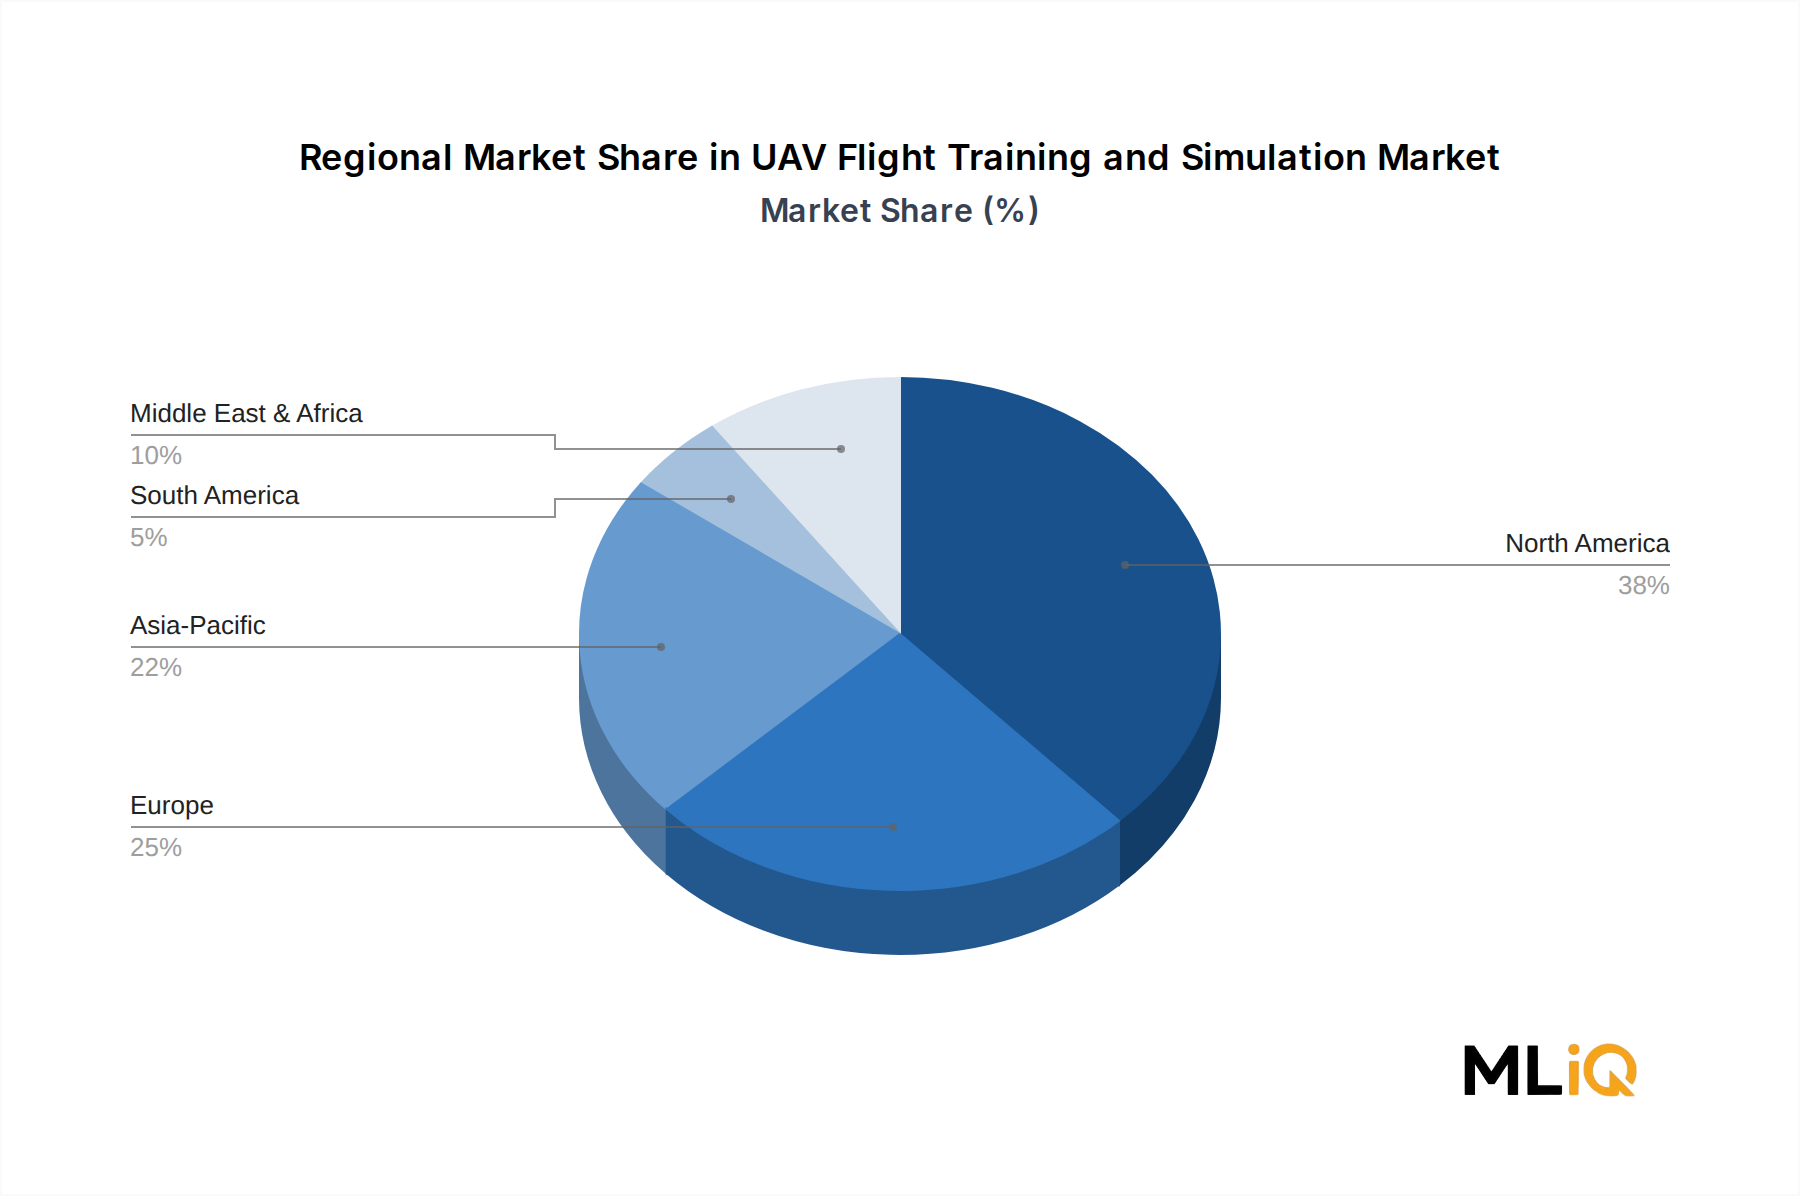
North America holds 38% of global revenue, but Asia-Pacific is forecast to grow at 20.1% CAGR through 2033.
Hardware and software integration costs represent 55–65% of total simulator lifecycle expense, pressuring margins for smaller vendors.
Macro drivers include rising geopolitical tensions, unmanned system procurement in NATO and Indo-Pacific commands, and commercial UAS fleet expansion. Restraints include high acquisition costs, export controls, and limited interoperability. The UAV Flight Training and Simulation Market is shifting from bespoke military simulators toward cloud-enabled, AI-assisted training architectures that lower cost per trainee. This shift favors vendors with strong synthetic environment expertise and regulatory certifications.
Segment Deep-Dive: Military and Law Enforcement Dominance in UAV Flight Training and Simulation Market
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Military and Law Enforcement
16.8%
62%
Defense budgets for UAS operator readiness and mission rehearsal
Civil and Commercial
20.5%
38%
Part 107 recurrent training, BVLOS certification, UAM pilot pipeline
Law Enforcement sub-segment
18.2%
14%
Border patrol, SWAT, and disaster response UAV operations
The Military UAV Training Market remains the largest revenue pool. Military and law enforcement agencies require high-fidelity simulators for RQ-4, MQ-9, and tactical UAS platforms. The segment includes basic remote pilot certification, sensor operator training, and full-mission rehearsal. Procurement cycles are long, with multi-year contracts from the US DoD, UK MoD, and Israeli Defense Forces. Margin pressure is moderate because defense customers prioritize certification and security over price.
Sub-Segment Dynamics
Military UAV training covers ISR, strike, and electronic warfare simulation; simulators must replicate SATCOM links and weapons release.
Law enforcement UAV training is growing from a smaller base, with agencies adopting simulation for indoor tactical and evidence-gathering scenarios.
Civil and commercial UAV training includes agriculture, construction, energy inspection, and drone delivery. The Commercial UAV Training Market is fragmented and more price-sensitive.
The UAV Flight Simulator Software Market is expected to grow faster than UAV Simulator Hardware Market because software updates and synthetic environments can be delivered digitally. However, hardware still accounts for the majority of initial contract value due to visual display systems, motion platforms, and high-performance computing components.
Margin Pressures
Hardware margin is compressed by GPU scarcity and custom display costs, with gross margins often 25–35% for simulator OEMs.
Software margin is higher at 60–75% for pure-play synthetic environment vendors.
Services and sustainment provide recurring revenue but face wage inflation for instructor pilots and software engineers.
Primary Market Drivers & Growth Restraints in UAV Flight Training and Simulation Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Rising military UAV procurement and operator training mandates
High
Short term
Driver
Commercial BVLOS and Part 107 recurrent training requirements
High
Medium term
Driver
AI and synthetic environment cost reduction
Medium
Medium term
Restraint
High simulator acquisition and sustainment costs
High
Short term
Restraint
Export controls on high-fidelity simulation
Medium
Long term
Restraint
Limited interoperability across UAV platforms
Medium
Long term
Quantitative evaluation shows defense budgets for unmanned systems grew 8–12% annually across NATO countries between 2022 and 2025. This directly lifts Military UAV Training Market demand. FAA Part 107 remote pilot certificates exceeded 870,000 cumulative issuances by 2025, creating a recurring training pool for the Commercial UAV Training Market. EASA UAS regulations and BVLOS rules add scenario-based training requirements.
Bottlenecks include simulator unit costs ranging from $250,000 for desktop systems to $15 million for full-mission domes. Sustainment contracts add 15–25% of original acquisition cost annually. Export controls under ITAR and EAR restrict high-fidelity simulators, limiting vendor addressable markets. Interoperability gaps force customers to buy platform-specific training, reducing price competition but increasing total cost of ownership.
Competitive Ecosystem & Key Vendor Profiles: UAV Flight Training and Simulation Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
CAE Inc
Full-flight simulators and defense training
Military, commercial
Leader
L3Harris Technologies Inc
ISR and UAV mission trainers
Defense, law enforcement
Leader
Northrop Grumman Corporation
Integrated UAV training systems
Military
Leader
Israel Aerospace Industries (IAI) Ltd
UAS and simulation
Defense
Challenger
Simlat UAS Simulation
UAS simulation software
Military, civil
Niche
Zen Technologies Limited
Combat training simulators
Defense
Challenger
General Atomics
UAV platforms and training
Military
Challenger
Textron Inc
UAS and simulation
Military, commercial
Challenger
CAE Inc: Provides full-mission simulators and training services; signed a 2022 MoU with Boeing to expand defense aerospace training collaboration.
L3Harris Technologies Inc: Supplies ISR and UAV mission trainers; benefits from US defense contracts and law enforcement modernization.
Northrop Grumman Corporation: Integrates UAV training with platform sales; strong in high-altitude ISR simulation.
Israel Aerospace Industries (IAI) Ltd: Leverages Israeli UAS operational experience for exportable simulation systems.
Simlat UAS Simulation: Focuses on software-based UAS simulation for military and civil customers.
Zen Technologies Limited: Offers combat training simulators with cost advantages for Asian and Middle Eastern buyers.
General Atomics: Couples UAV platform expertise with training solutions for MQ-9 and related systems.
Textron Inc: Provides UAS platforms and simulation for military and commercial operators.
The competitive ecosystem is moderately concentrated, with CAE and L3Harris holding an estimated 30–35% combined share of military UAV simulation revenue. Niche software vendors compete on synthetic environment fidelity and integration speed.
Strategic Milestones & Recent Developments in UAV Flight Training and Simulation Market
Latest Strategic Moves
Date
Company
Event Type
Impact
July 2022
CAE
Partnership
MoU with Boeing to expand defense aerospace training collaboration
September 2022
MORAI
Launch
MORAI SIM Air UAV/UAM simulation platform launched at Commercial UAV Expo 2022
July 2022: CAE signed a Memorandum of Understanding with Boeing to explore teaming in defense aerospace training. The memorandum leverages strengths in advanced technologies to enhance innovation and competition through potential joint offerings.
September 2022: MORAI, a South Korean autonomous vehicle simulation developer, launched MORAI SIM Air at the Commercial UAV Expo 2022. The platform is designed for UAVs and UAM to verify system safety in realistic virtual spaces.
These moves signal consolidation around integrated training ecosystems. The AI-Powered Simulation Market is attracting investment because AI can generate edge cases, adapt scenarios, and reduce instructor workload. Future milestones likely include cloud-delivered simulation and multi-domain training that links UAV, UAM, and crewed aircraft.
Regional Market Analysis & Growth Corridors for UAV Flight Training and Simulation Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
16.5%
$1.24B
Defense budgets, FAA Part 107
High
Europe
18.2%
$0.82B
EASA UAS rules, defense programs
High
Asia-Pacific
20.1%
$0.72B
Military modernization, commercial UAS
Medium
LAMEA
19.4%
$0.48B
Border security, oil and gas inspection
Medium
North America is the most mature market, with 38% of global revenue. The FAA Part 107 framework and large defense budgets sustain Military UAV Training Market demand.
Europe is the second-largest region, driven by EASA UAS regulations and multinational defense programs. Germany, France, and the UK lead adoption.
Asia-Pacific is the fastest-growing region at 20.1% CAGR, led by China, India, Japan, and South Korea. Military modernization and commercial UAS fleets expand the Commercial UAV Training Market.
LAMEA combines Latin America, Middle East, and Africa. Growth is concentrated in border security, oil and gas inspection, and defense modernization. The Synthetic Environment Simulation Market benefits from demand for low-cost, deployable training.
Pricing Dynamics, Cost Structures & Margin Pressure in UAV Flight Training and Simulation Market
Cost Component
Share of Simulator ASP (%)
Trend
Hardware (GPUs, FPGAs, displays)
35–45%
Rising
Software and synthetic environment
25–30%
Stable
Labor and integration
15–20%
Rising
Sustainment and updates
10–15%
Stable
Average selling prices (ASP) for UAV flight simulators range from $250,000 for desktop trainers to $15 million for full-mission systems. Hardware costs are exposed to Advanced Semiconductor Materials Market volatility, where advanced node capacity and substrate availability affect GPU and FPGA pricing. Carbon Fiber Composites Market inputs are less direct but matter for motion platform and airframe mock-up components. Labor costs for instructors and software engineers rose 6–9% annually from 2022 to 2025.
Margin structures vary by layer:
Hardware OEMs face gross margins of 25–35% due to component costs and customization.
Service providers earn 20–30% operating margins on recurring training contracts.
Pricing power is strongest for certified full-mission simulators with defense certifications. Commercial desktop simulators face price erosion of 3–5% annually as competition intensifies.
Export, Cross-Border Trade & Tariff Impact on UAV Flight Training and Simulation Market
Corridor
Key Exporters
Key Importers
Tariff/Barrier
US to NATO
United States
Europe, Canada
ITAR/EAR licensing
Europe to Asia
France, Germany
India, Japan
Wassenaar Arrangement
Israel to Asia
Israel
India, South Korea
Defense export permits
China to Global South
China
Middle East, Africa
US tariffs on Chinese electronics
Trade flows in UAV training simulators are constrained by dual-use export controls. US ITAR and EAR rules require licenses for high-fidelity simulators, adding 3–9 months to delivery timelines. The Wassenaar Arrangement governs conventional arms and dual-use exports among 42 participating states. Tariffs on Chinese electronics and European avionics can raise simulator unit costs by 5–12%.
Net exporters include the United States, Israel, France, and the United Kingdom. Key importers are India, Japan, South Korea, and Gulf states. Geopolitical tensions are driving localization, with India and China increasing domestic simulator production. The AI-Powered Simulation Market may partially bypass hardware trade barriers because software can be delivered via cloud, though data sovereignty rules still apply.
UAV Flight Training and Simulation Market Segmentation
1. Application
1.1. Military and Law Enforcement
1.2. Civil and Commercial
UAV Flight Training and Simulation Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
UAV Flight Training and Simulation Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 17.95% from 2020-2034
Segmentation
By Application
Military and Law Enforcement
Civil and Commercial
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Military and Law Enforcement
5.1.2. Civil and Commercial
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Military and Law Enforcement
6.1.2. Civil and Commercial
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Military and Law Enforcement
7.1.2. Civil and Commercial
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Military and Law Enforcement
8.1.2. Civil and Commercial
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Military and Law Enforcement
9.1.2. Civil and Commercial
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Military and Law Enforcement
10.1.2. Civil and Commercial
11. Competitive Analysis
11.1. Company Profiles
11.1.1. CAE Inc
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Israel Aerospace Industries (IAI) Ltd
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. L3Harris Technologies Inc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Simlat UAS Simulation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. General Atomics
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Northrop Grumman Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Textron Inc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Zen Technologies Limited
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Quantum3D
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. H-SIM
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Presagis USA Inc
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: UAV Flight Training and Simulation Market Revenue Breakdown (billionusdbillion, %) by Region 2026 & 2034
Figure 2: North America UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 3: North America UAV Flight Training and Simulation Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 5: North America UAV Flight Training and Simulation Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 7: South America UAV Flight Training and Simulation Market Revenue Share (%), by Application 2026 & 2034
Figure 8: South America UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 9: South America UAV Flight Training and Simulation Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 11: Europe UAV Flight Training and Simulation Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Europe UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 13: Europe UAV Flight Training and Simulation Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 15: Middle East & Africa UAV Flight Training and Simulation Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Middle East & Africa UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 17: Middle East & Africa UAV Flight Training and Simulation Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 19: Asia Pacific UAV Flight Training and Simulation Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Asia Pacific UAV Flight Training and Simulation Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 21: Asia Pacific UAV Flight Training and Simulation Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 2: UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Region 2020 & 2034
Table 3: North America UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 4: North America UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 5: United States UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 6: Canada UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 7: Mexico UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 8: South America UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 9: South America UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 10: Brazil UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 11: Argentina UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 12: Rest of South America UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 13: Europe UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 14: Europe UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 15: United Kingdom UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 16: Germany UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 17: France UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 18: Italy UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 19: Spain UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 20: Russia UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 21: Benelux UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 22: Nordics UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 23: Rest of Europe UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 24: Middle East & Africa UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 25: Middle East & Africa UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 26: Turkey UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 27: Israel UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 28: GCC UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 29: North Africa UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 30: South Africa UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 31: Rest of Middle East & Africa UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 32: Asia Pacific UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Application 2020 & 2034
Table 33: Asia Pacific UAV Flight Training and Simulation Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 34: China UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 35: India UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 36: Japan UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 37: South Korea UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 38: ASEAN UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 39: Oceania UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 40: Rest of Asia Pacific UAV Flight Training and Simulation Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We allocate 70–80% of total research effort to primary research, interviewing executives, engineers, and procurement officials across the UAV training and simulation value chain.
Primary interviews target 4–5 company types: UAV simulator hardware OEMs, UAV flight simulator software vendors, defense prime contractors integrating UAV training systems, commercial UAS training academies, and synthetic environment/visual system providers.
We interview 3–4 specific stakeholder job titles: Director of UAV Flight Training Programs, Defense Procurement Manager for Simulation Systems, Chief Simulation Engineer, and Aviation Regulatory Compliance Lead for UAS.
Primary research also captures pricing, contract structure, and adoption barriers through structured questionnaires and semi-structured interviews.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of UAV Flight Training Programs
30%
Defense Procurement Manager for Simulation Systems
25%
Chief Simulation Engineer
20%
Aviation Regulatory Compliance Lead for UAS
15%
Commercial UAS Operations Manager
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
UAV simulator hardware OEMs
25%
UAV flight simulator software vendors
20%
Defense prime contractors integrating UAV training systems
20%
Commercial UAS training academies
20%
Synthetic environment and visual system providers
15%
Secondary Research & Industry Benchmarking
We use 20–30% secondary research, drawing on financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
We do not cite market research websites; instead we use .gov, .org, and trade association publications.
Industry benchmarking includes defense budget documents, UAS certification statistics, and simulator procurement records.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up quantification uses 3–4 specific quantitative metrics: number of active military UAV operators per country, annual UAV pilot training throughput per training center, average simulator replacement cycle in years, and defense training budget allocated to UAV simulation.
Top-down modeling uses regional defense and commercial UAS spending, then applies simulation intensity factors by platform type.
Every report is updated to the date of purchase, with forecast adjustments for order backlogs, policy changes, and technology shifts.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, based on source triangulation and respondent validation.
Cross-checks compare primary interview data against Bloomberg, Factiva, Hoovers, PitchBook, and government procurement records.
Outlier detection and sensitivity analysis are applied to segment shares, regional CAGRs, and pricing assumptions.
Final estimates are reviewed by senior analysts and checked for internal consistency before publication.
Frequently Asked Questions
1. What sustainability and ESG factors affect the UAV Flight Training and Simulation Market?
Simulation training can cut live UAV flight hours by 30–50%, lowering jet fuel consumption and CO2 emissions compared with live-fly training. OEMs face pressure to report Scope 3 emissions from hardware manufacturing and simulator power draw. CAE and other leaders are publishing ESG targets that include simulator energy efficiency.
2. How do FAA and EASA regulations shape the UAV Flight Training and Simulation Market?
FAA Part 107 and EASA's 2021 UAS regulation require recurrent training for remote pilots, directly lifting demand for certified simulation modules. Compliance with BVLOS rules adds need for scenario-based sim training. Northrop Grumman and L3Harris adjust simulator content to match these regulatory updates.
3. What raw material and supply chain factors affect UAV simulator production?
UAV flight simulators rely on GPUs, FPGAs, and high-brightness LCDs; 2022–2023 semiconductor lead times stretched to 26–52 weeks. Supply concentration in Taiwan and South Korea for advanced chips creates risk. Simlat and Zen Technologies mitigate by dual-sourcing displays and computing modules.
4. How do export controls and tariffs affect cross-border trade in UAV training simulators?
US ITAR and EAR restrictions classify high-fidelity UAV simulators as dual-use, requiring export licenses for many destinations. Tariffs on Chinese electronics and European avionics can raise simulator unit costs by 5–12%. The Wassenaar Arrangement coordinates controls among 42 states, affecting shipments from Israel and France.
5. Who are the leading companies in the UAV Flight Training and Simulation Market?
CAE Inc. and L3Harris Technologies are leaders, with CAE holding an estimated 18–22% share of global military UAV training simulation revenue. Simlat and Zen Technologies serve niche civil and defense segments. Northrop Grumman and Israel Aerospace Industries compete through platform-integrated training.
6. What technological innovations are shaping UAV flight training and simulation?
AI-driven synthetic environments and digital twins cut scenario development time by up to 40%. MORAI SIM Air, launched in 2022, validates UAV safety in realistic virtual spaces. Cloud-delivered simulation and multi-domain training link UAV, UAM, and crewed aircraft scenarios.