Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Aircraft Brakes Market to Hit $14.6B by 2033, CAGR 5.11%
Aircraft Brakes Market
Aircraft Brakes Market to Hit $14.6B by 2033, CAGR 5.11%
Aircraft Brakes Market by Type (Electric Brakes, Carbon Brakes, Steel Brakes), by End-User (Commercial, Military, General Aviation), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
The global Aircraft Brakes Market is valued at $9.8 billion in 2025 and is projected to reach $14.6 billion by 2033, expanding at a 5.11% CAGR. Growth is anchored in commercial aviation recovery, rising aircraft deliveries, and an expanding aftermarket for brake overhauls. Carbon Brakes Market accounts for the largest revenue pool, supported by narrowbody and widebody fleet modernization.
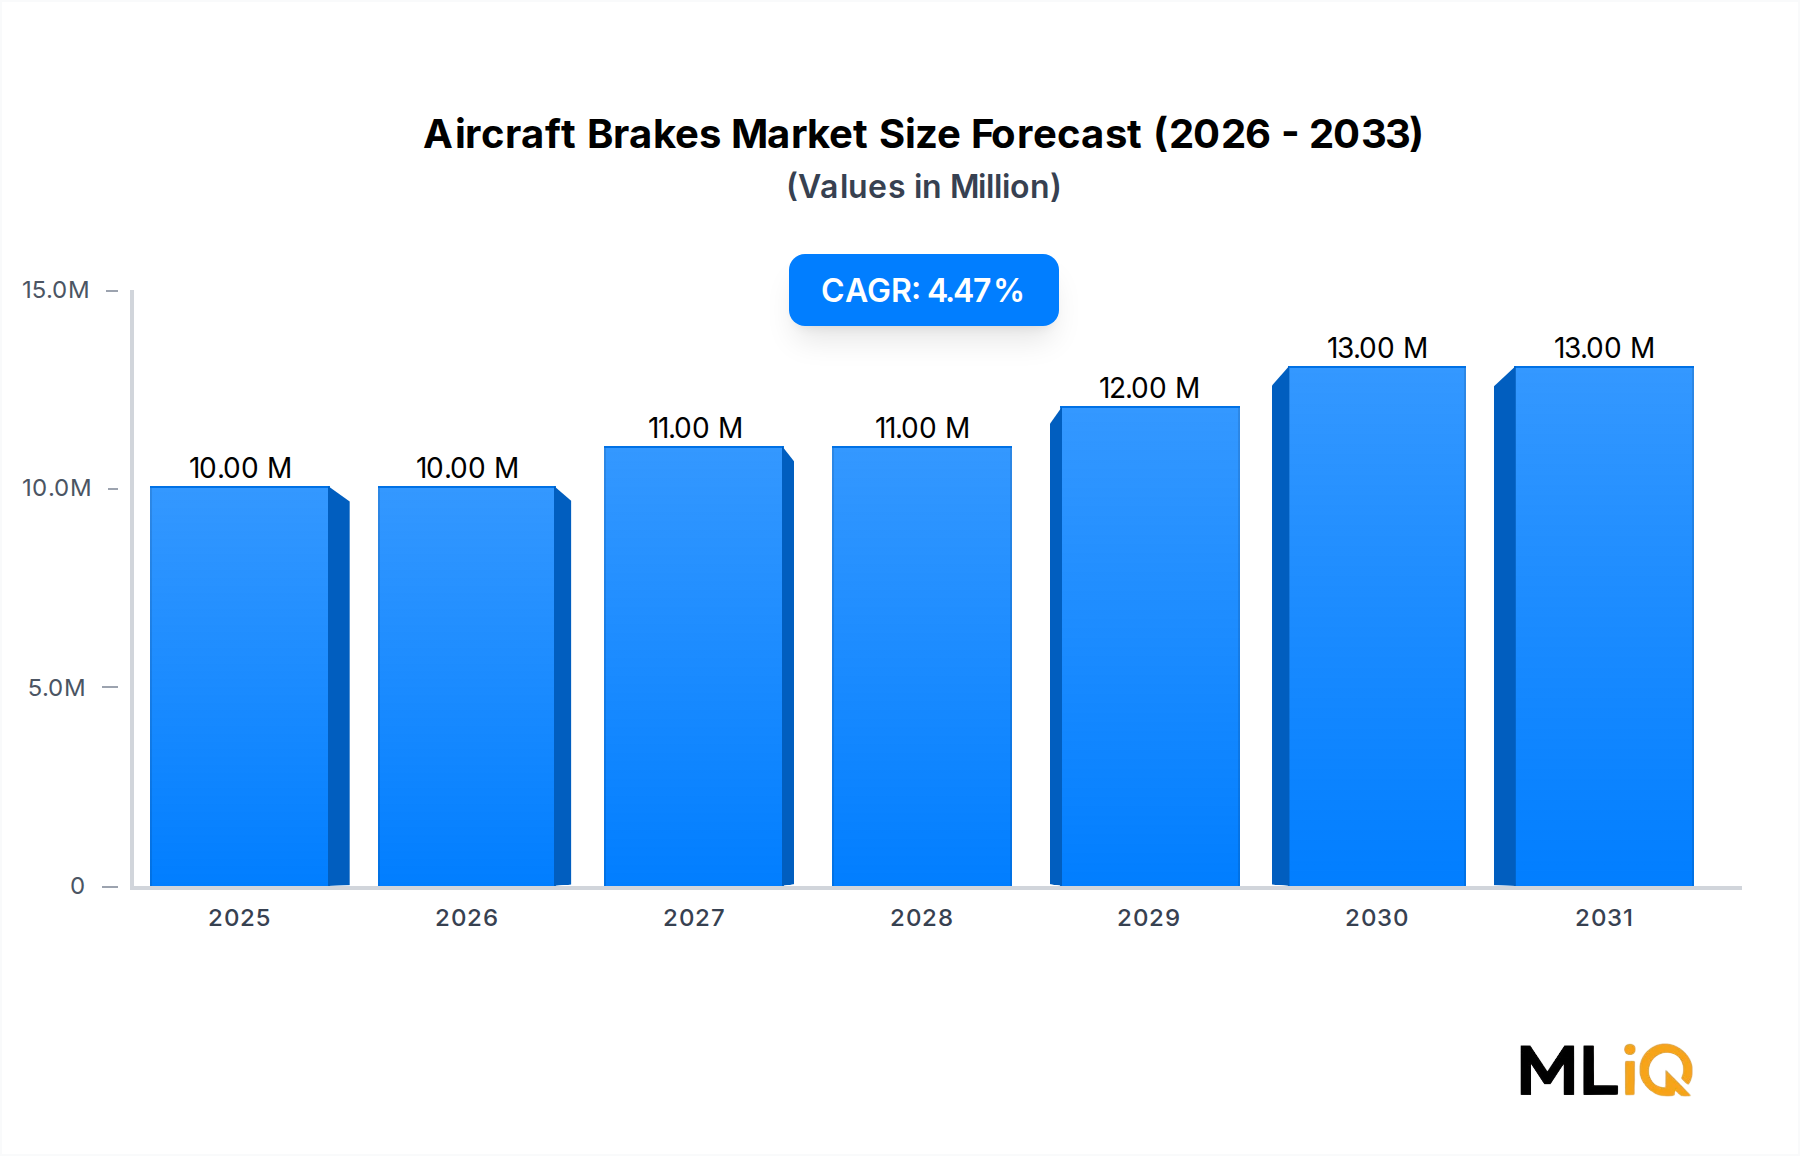
Aircraft Brakes Market Size (In Million)
15.0M
10.0M
5.0M
0
10.00 M
2025
10.00 M
2026
11.00 M
2027
11.00 M
2028
12.00 M
2029
13.00 M
2030
13.00 M
2031
Commercial Aircraft Brakes Market demand is led by Boeing 737 MAX, Airbus A320neo, and 787 programs, which together drive 62% of OEM brake volumes.
Military Aircraft Brakes Market remains stable, with $1.4 billion in 2025 revenue, tied to F-35, F-15EX, and Eurofighter sustainment.
General Aviation Brakes Market represents 11% of global value, with steady replacement cycles across Cessna, Cirrus, and Beechcraft fleets.
Regional momentum favors Asia-Pacific, forecast to grow at 6.2% CAGR, as China and India expand fleets and local MRO capacity.
Key strategic takeaways: suppliers must invest in carbon composite capacity and digital brake-health monitoring to capture aftermarket margin. The Electric Aircraft Brakes Market, though under 4% share, is the fastest-growing niche due to eVTOL and UAV adoption. Regulatory compliance and raw material supply for Aircraft Brake Materials Market will separate leaders from laggards.
Segment Deep-Dive: Carbon Brakes Dominance in Aircraft Brakes Market
Segment Analysis Matrix
Growth Rate (CAGR 2025–2033)
Market Share (2025)
Key Demand Driver
Carbon Brakes
5.8%
58%
Lightweight, high thermal capacity for commercial jets
Steel Brakes
3.2%
27%
Cost-sensitive military trainers and legacy GA aircraft
Electric Brakes
7.4%
15%
eVTOL, UAV, and brake-by-wire business jets
Carbon Brakes Lead Revenue and Innovation
Carbon brakes use carbon-carbon composite discs that weigh 40% less than steel equivalents and last up to 2,000 landing cycles. The Carbon Brakes Market is projected to add $2.9 billion in incremental revenue from 2025 to 2033. Safran, Collins Aerospace, and Parker-Meggitt control roughly 75% of this segment, creating high barriers for new entrants.
Steel Brakes Retain Defensive Position
Steel Brakes Market revenue is concentrated in military transport, trainer, and older general aviation platforms where acquisition cost outweighs weight savings. Growth is limited to 3.2% CAGR, but aftermarket replacement demand remains predictable. Honeywell and Crane Aerospace supply key steel brake assemblies for legacy fleets.
Electric Brakes Represent the Fastest-Growing Niche
The Electric Aircraft Brakes Market is expanding from a small base, forecast at 7.4% CAGR through 2033. Adoption is driven by electric vertical takeoff and landing vehicles, unmanned aerial systems, and fly-by-wire business jets that require precise, lightweight braking. Meggitt (now Parker-Meggitt) and Beringer Aero are early leaders, though certification timelines remain a bottleneck.
Margin Pressures and Sub-Segment Dynamics
Raw material inflation for carbon fiber precursor and ceramic matrix composites has raised input costs by 8–12% since 2022.
OEM brake margins range from 18–24%, while aftermarket margins reach 35–42%, pushing vendors toward service contracts.
The Commercial Aircraft Brakes Market favors carbon brakes for new deliveries, but airline retrofit budgets are sensitive to interest rates.
Primary Market Drivers & Growth Restraints in Aircraft Brakes Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Rising commercial aircraft deliveries
Driver
Boeing and Airbus target 1,800+ deliveries by 2026, each requiring new brake sets
High
Short term
Carbon brake retrofit cycle
Driver
Airlines replace steel with carbon to cut weight and fuel burn by 1–2%
High
Long term
Military sustainment budgets
Driver
F-35 and F-15EX programs fund brake spares and upgrades
Medium
Long term
Raw material price volatility
Restraint
Carbon fiber and steel input costs fluctuate 10–15% annually
Medium
Short term
Certification delays
Restraint
FAA/EASA brake approvals add 12–18 months, slowing electric brake adoption
High
Short term
Aftermarket counterfeit parts
Restraint
Unapproved brake components create safety and liability risks
Medium
Long term
The primary growth engine is the Commercial Aircraft Brakes Market, where global revenue passenger kilometers (RPKs) grew 8.1% in 2024 and are expected to sustain 4–5% annual growth. This directly increases brake wear and replacement frequency. Airlines also favor carbon brakes because each kilogram saved reduces fuel burn by approximately 0.03% per aircraft per year.
Restraints are concentrated in supply chain and regulation. Carbon brake discs require specialized precursors and long lead times, exposing OEMs to 15–20% cost swings. Certification bottlenecks for Electric Aircraft Brakes Market products limit near-term scale. However, aftermarket demand from the Aviation Aftermarket Brakes Market cushions cyclical OEM downturns, as brake overhauls are mandatory regardless of new aircraft sales.
Safran: The company holds an estimated 28% share of the global carbon brake market and supplies Airbus, Boeing, and Dassault. Its landing systems division generated €4.2 billion in 2024 revenue.
Parker-Meggitt: Acquired by Parker Hannifin in 2022, it controls key military brake programs including the F-35 and Typhoon. Its aftermarket network covers 3,000+ aircraft operators.
Honeywell International Inc: Provides brake control and monitoring systems integrated with avionics. It invests $900 million annually in aerospace R&D, including brake-by-wire.
RTX Corporation: Collins Aerospace won the F-15EX boltless wheel and carbon brake contract in 2022. It supports 40+ commercial and military platforms.
Crane Aerospace & Electronics: Supplies anti-skid brake control units for regional jets and business aircraft. It is expanding into electric brake actuation.
Beringer Aero: Focuses on STC-approved wheels and brakes for general aviation and emerging eVTOL platforms, with 35% revenue growth in 2024.
Advent Aircraft Systems Inc: Develops electric brake systems for unmanned aircraft and has partnered with three UAS manufacturers.
Matco Aircraft Landing Systems: Provides cost-effective brake discs and cylinders for experimental and light sport aircraft, with a strong North American aftermarket.
Strategic Milestones & Recent Developments in Aircraft Brakes Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Distribution agreement with Aircraft Wheel and Brake for KT-1/KT-100
March 2023
AllClear Aerospace & Defense
Partnership
Expands military brake aftermarket to select international regions
Collins Aerospace selected for F-15EX boltless wheels and carbon brakes
September 2022
RTX Corporation
Contract
Replaces legacy wheels and brakes on Boeing production line
Parker Hannifin completes Meggitt acquisition
September 2022
Parker-Meggitt
M&A
Creates a leading military and commercial brake supplier
Safran opens carbon brake production line in Malaysia
January 2024
Safran
Capacity expansion
Adds 20% to regional carbon disc output for Asia-Pacific
March 2023: AllClear Aerospace & Defense signed an exclusive distribution agreement with Aircraft Wheel and Brake, LLC (a Kaman company) for KT-1 and KT-100 platforms. This move strengthens the Military Aircraft Brakes Market aftermarket channel in international regions.
September 2022: Boeing selected Collins Aerospace (RTX Corporation) to provide boltless wheels and carbon brakes for the F-15EX. The equipment replaces legacy systems on the production line, reinforcing the trend toward lighter, longer-life carbon brakes.
September 2022: Parker Hannifin completed its acquisition of Meggitt, forming Parker-Meggitt. The combined entity now competes directly with Safran and Honeywell in both Commercial Aircraft Brakes Market and Military Aircraft Brakes Market segments.
January 2024: Safran expanded carbon brake manufacturing in Malaysia to serve Asia-Pacific airlines. The plant is expected to produce 12,000 carbon discs annually by 2026.
Regional Market Analysis & Growth Corridors for Aircraft Brakes Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
4.6%
$3.33 billion
Fleet size, defense spending, aftermarket density
High (FAA)
Europe
4.9%
$2.35 billion
Airbus production, carbon brake retrofits
High (EASA)
Asia-Pacific
6.2%
$2.74 billion
China/India fleet expansion, MRO localizations
Medium-High
LAMEA
5.4%
$1.38 billion
Military modernization, Brazilian and Middle East aviation
Medium
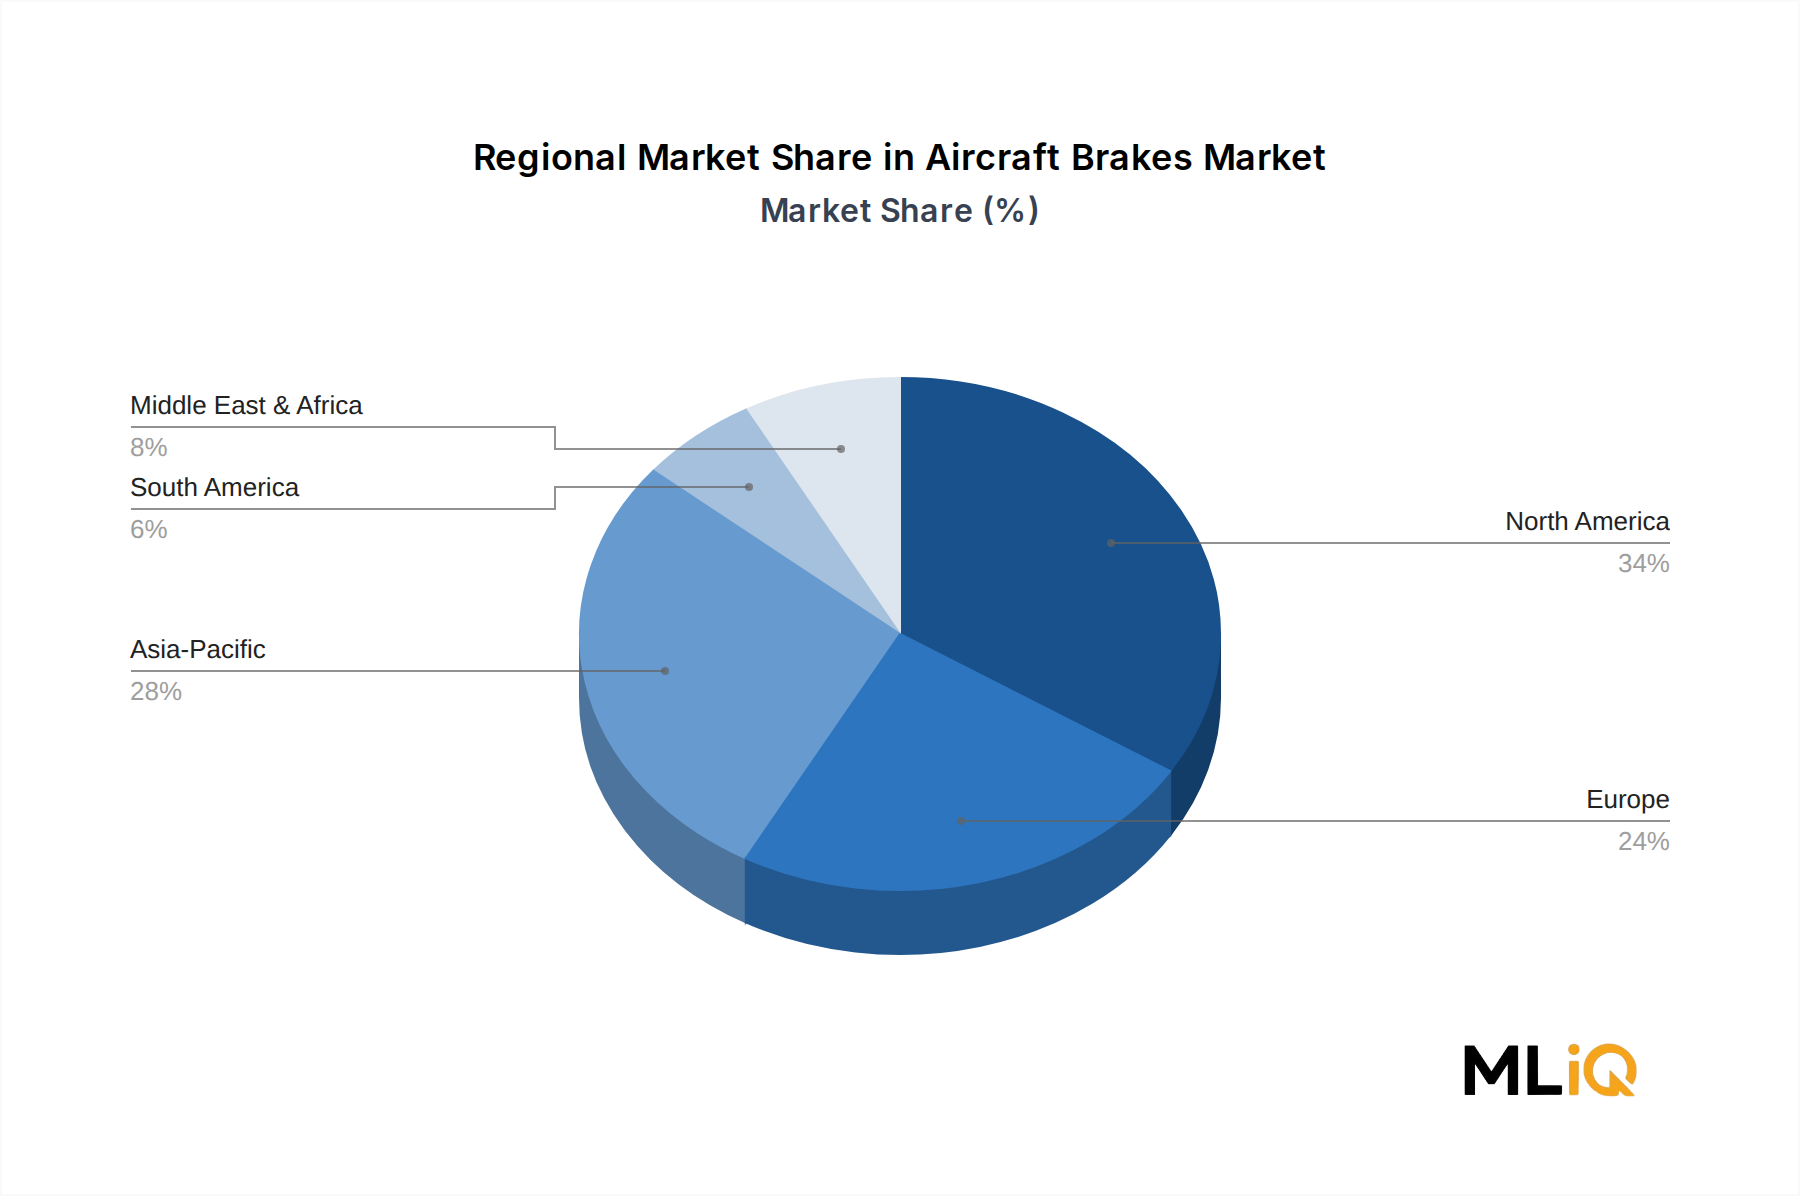
North America remains the most mature market, holding 34% share in 2025. The United States operates 45% of global commercial aircraft and maintains the largest military brake sustainment budget. Growth is steady at 4.6% CAGR, driven by aftermarket replacements rather than new aircraft.
Asia-Pacific is the fastest-growing region at 6.2% CAGR, with China expected to add 1,200 commercial jets by 2030. Local MRO providers are expanding carbon brake repair capabilities, reducing reliance on Western depots.
Europe benefits from Airbus production and stringent EASA rules that mandate frequent brake inspections. The region's Carbon Brakes Market is projected to reach $1.4 billion by 2030.
LAMEA shows moderate growth, led by Middle East carriers and Brazilian military modernization. The region's General Aviation Brakes Market is small but resilient, with 7% annual aftermarket growth.
Key risk: trade restrictions on carbon fiber exports could disrupt Asia-Pacific supply chains, adding 10–15% to brake component costs.
Technology Innovation & R&D Trajectory in Aircraft Brakes Market
Three disruptive technologies are reshaping the Aerospace Braking Systems Market: electric brake actuation, ceramic matrix composite (CMC) friction materials, and digital brake health monitoring.
Electric brake actuation removes hydraulic lines, reducing weight by up to 15% and enabling precise anti-skid control. Adoption is accelerating in eVTOL and business jets, with certification expected by 2027.
Ceramic matrix composites offer 30% higher thermal capacity than carbon-carbon and resist oxidation at 1,400°C. Safran and Honeywell have filed 40+ patents since 2022.
Digital brake health monitoring uses sensors and predictive analytics to reduce unscheduled maintenance by 25%. RTX Collins Aerospace is deploying this on the F-35 and 787.
R&D investment levels at top vendors range from 5–8% of aerospace segment revenue. These innovations reinforce incumbent positions because certification and fleet integration favor established suppliers. However, additive manufacturing could allow new entrants to produce brake calipers at 20–30% lower cost, threatening the Aircraft Brake Materials Market.
European airworthiness and environmental standards
Requires REACH-compliant materials
SAE International
AS/AMS standards
Brake disc and lining specifications
Global design harmonization
ICAO
Annex 8
Airworthiness of aircraft
National adoption varies
The FAA and EASA impose the most stringent brake certification requirements. The 2024 FAA airworthiness directive on carbon brake oxidation required operators to inspect and replace affected units within 120 days, creating a spike in aftermarket demand. EASA's REACH restrictions on chromium and cadmium force suppliers to reformulate friction materials, adding 3–5% to production costs.
North America: FAA oversight emphasizes continued airworthiness and mandatory service bulletins. Compliance costs for new brake systems average $2.5 million per certification.
Europe: EASA applies CS-25 and ETSO standards, with increasing scrutiny on electric brake software under DO-178C. This slows the Electric Aircraft Brakes Market but improves safety.
Asia-Pacific: China's CAAC and India's DGCA are aligning with FAA/EASA standards, reducing duplicate certification but extending local approval timelines.
Policy trend: regulators are moving toward performance-based rules for brake health monitoring, which could accelerate adoption of predictive maintenance and benefit the Aviation Aftermarket Brakes Market.
Aircraft Brakes Market Segmentation
1. Type
1.1. Electric Brakes
1.2. Carbon Brakes
1.3. Steel Brakes
2. End-User
2.1. Commercial
2.2. Military
2.3. General Aviation
Aircraft Brakes Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Aircraft Brakes Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.11% from 2020-2034
Segmentation
By Type
Electric Brakes
Carbon Brakes
Steel Brakes
By End-User
Commercial
Military
General Aviation
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Electric Brakes
5.1.2. Carbon Brakes
5.1.3. Steel Brakes
5.2. Market Analysis, Insights and Forecast - by End-User
5.2.1. Commercial
5.2.2. Military
5.2.3. General Aviation
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Electric Brakes
6.1.2. Carbon Brakes
6.1.3. Steel Brakes
6.2. Market Analysis, Insights and Forecast - by End-User
6.2.1. Commercial
6.2.2. Military
6.2.3. General Aviation
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Electric Brakes
7.1.2. Carbon Brakes
7.1.3. Steel Brakes
7.2. Market Analysis, Insights and Forecast - by End-User
7.2.1. Commercial
7.2.2. Military
7.2.3. General Aviation
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Electric Brakes
8.1.2. Carbon Brakes
8.1.3. Steel Brakes
8.2. Market Analysis, Insights and Forecast - by End-User
8.2.1. Commercial
8.2.2. Military
8.2.3. General Aviation
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Electric Brakes
9.1.2. Carbon Brakes
9.1.3. Steel Brakes
9.2. Market Analysis, Insights and Forecast - by End-User
9.2.1. Commercial
9.2.2. Military
9.2.3. General Aviation
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Electric Brakes
10.1.2. Carbon Brakes
10.1.3. Steel Brakes
10.2. Market Analysis, Insights and Forecast - by End-User
10.2.1. Commercial
10.2.2. Military
10.2.3. General Aviation
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Safran
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Parker-Meggitt
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Honeywell International Inc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. RTX Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Crane Aerospace & Electronics
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Beringer Aero
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Advent Aircraft Systems Inc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Tactair
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. RAPCO Inc
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Matco Aircraft Landing Systems
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. The Carlyle Johnson Machine Company LL
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Aircraft Brakes Market Revenue Breakdown (billionusdbillion, %) by Region 2026 & 2034
Figure 2: North America Aircraft Brakes Market Revenue (billionusdbillion), by Type 2026 & 2034
Figure 3: North America Aircraft Brakes Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Aircraft Brakes Market Revenue (billionusdbillion), by End-User 2026 & 2034
Figure 5: North America Aircraft Brakes Market Revenue Share (%), by End-User 2026 & 2034
Figure 6: North America Aircraft Brakes Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 7: North America Aircraft Brakes Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Aircraft Brakes Market Revenue (billionusdbillion), by Type 2026 & 2034
Figure 9: South America Aircraft Brakes Market Revenue Share (%), by Type 2026 & 2034
Figure 10: South America Aircraft Brakes Market Revenue (billionusdbillion), by End-User 2026 & 2034
Figure 11: South America Aircraft Brakes Market Revenue Share (%), by End-User 2026 & 2034
Figure 12: South America Aircraft Brakes Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 13: South America Aircraft Brakes Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Aircraft Brakes Market Revenue (billionusdbillion), by Type 2026 & 2034
Figure 15: Europe Aircraft Brakes Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Aircraft Brakes Market Revenue (billionusdbillion), by End-User 2026 & 2034
Figure 17: Europe Aircraft Brakes Market Revenue Share (%), by End-User 2026 & 2034
Figure 18: Europe Aircraft Brakes Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 19: Europe Aircraft Brakes Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Aircraft Brakes Market Revenue (billionusdbillion), by Type 2026 & 2034
Figure 21: Middle East & Africa Aircraft Brakes Market Revenue Share (%), by Type 2026 & 2034
Figure 22: Middle East & Africa Aircraft Brakes Market Revenue (billionusdbillion), by End-User 2026 & 2034
Figure 23: Middle East & Africa Aircraft Brakes Market Revenue Share (%), by End-User 2026 & 2034
Figure 24: Middle East & Africa Aircraft Brakes Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 25: Middle East & Africa Aircraft Brakes Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Aircraft Brakes Market Revenue (billionusdbillion), by Type 2026 & 2034
Figure 27: Asia Pacific Aircraft Brakes Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Aircraft Brakes Market Revenue (billionusdbillion), by End-User 2026 & 2034
Figure 29: Asia Pacific Aircraft Brakes Market Revenue Share (%), by End-User 2026 & 2034
Figure 30: Asia Pacific Aircraft Brakes Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 31: Asia Pacific Aircraft Brakes Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Aircraft Brakes Market Revenue billionusdbillion Forecast, by Type 2020 & 2034
Table 46: Rest of Asia Pacific Aircraft Brakes Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70–80% of total research effort through primary interviews, surveys, and direct data exchanges with aircraft brake value chain participants.
Target respondents include: Carbon brake disc and heat sink manufacturers; Aircraft wheel and brake assembly OEMs; Electric brake actuator and control unit suppliers; Brake-by-wire systems integrators; Aftermarket MRO distributors.
Interviewed job titles: Director of Aircraft Landing Systems Procurement; Chief Engineer, Braking and Wheel Systems; VP of Airline Technical Operations; Military Aviation Sustainment Program Manager; Aftermarket Parts Category Manager.
Primary data collection covers 2025 base year and forecast years 2026–2034, with cross-validation against actual order books and aftermarket consumption records.
We guarantee an estimated data accuracy level of 85–90% for all market sizing and share estimates.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Aircraft Landing Systems Procurement
25%
Chief Engineer, Braking and Wheel Systems
25%
VP of Airline Technical Operations
20%
Military Aviation Sustainment Program Manager
20%
Aftermarket Parts Category Manager
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Carbon brake OEMs
35%
Aircraft wheel and brake assembly manufacturers
25%
Brake actuator and control unit suppliers
15%
Aftermarket distributors and MRO providers
15%
Raw material suppliers (carbon composite)
10%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20–30% of total effort and includes filed annual reports, investor presentations, and regulatory dockets.
We do not cite market research websites; all third-party references are .gov, .org, or trade association publications.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up calculation uses specific quantitative metrics: annual commercial aircraft deliveries; global commercial fleet size and retirement rate; average brake replacement cycles per aircraft type; military aircraft procurement budgets by platform; aftermarket brake component consumption per flight hour.
Top-down modeling uses segment revenue splits for Electric Brakes, Carbon Brakes, and Steel Brakes, and end-user splits for Commercial, Military, and General Aviation.
Regional demand is modeled across North America, South America, Europe, Middle East & Africa, and Asia Pacific, with country-level granularity for United States, Canada, Mexico, Brazil, Argentina, United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Turkey, Israel, GCC, North Africa, South Africa, China, India, Japan, South Korea, ASEAN, Oceania, and Rest of Asia Pacific.
Every report is updated to the date of purchase to reflect the latest order wins, regulatory changes, and aftermarket pricing.
Data Accuracy & Quality Check
Multi-level data triangulation compares primary interview results, secondary financial filings, and regulatory databases to identify outliers.
We enforce a guaranteed estimated data accuracy level of 85–90%, with error bands disclosed for niche segments such as Electric Aircraft Brakes.
Cross-checks include year-over-year growth consistency, capacity utilization at brake manufacturing plants, and aftermarket revenue per flight hour.
All currency figures are reported in USD billions unless otherwise stated; CAGR is calculated on a constant-currency basis.
Final quality review is conducted by a senior analyst and a sector lead before publication.
Frequently Asked Questions
1. Which region dominates the Aircraft Brakes Market and why?
North America holds the largest share at 34% in 2025, driven by the world's largest commercial and military aircraft fleet, high aftermarket replacement cycles, and the presence of Safran Landing Systems, Honeywell, and RTX Collins Aerospace. The FAA's stringent maintenance rules and defense sustainment budgets further reinforce regional leadership.
2. How are purchasing trends shifting in the Commercial Aircraft Brakes Market?
Airlines are shifting toward carbon brake retrofits and longer-life heat sinks to reduce downtime and fuel burn, with carbon brakes now accounting for about 58% of type revenue. Procurement teams increasingly bundle brake and wheel services into power-by-the-hour contracts, pushing vendors like Parker-Meggitt and Safran to offer performance-based aftermarket programs.
3. What post-pandemic recovery patterns are visible in the Aviation Aftermarket Brakes Market?
Global commercial flight hours recovered to roughly 92% of 2019 levels by early 2025, triggering a 7.1% annual rise in brake replacement demand. Structural shifts include deferred fleet retirements, higher utilization of narrowbody aircraft, and accelerated inventory restocking by MRO providers. This has made the Aviation Aftermarket Brakes Market a critical growth engine for the next five years.
4. What technological innovations are shaping the Aerospace Braking Systems Market?
Electric brake actuation, brake-by-wire, and ceramic matrix composite friction materials are the leading innovations, with R&D budgets at major vendors rising 6–8% annually. Collins Aerospace and Safran are testing lighter boltless wheels and health-monitoring sensors that predict brake wear. These advances aim to cut weight by up to 15% and reduce maintenance events.
5. Which disruptive technologies could challenge incumbent Aircraft Brake Materials Market suppliers?
Additive manufacturing of brake calipers and graphene-reinforced composites could lower production costs by 20–30% while improving thermal resistance. Electric propulsion and eVTOL platforms require new brake architectures, potentially bypassing traditional hydraulic suppliers. Incumbents like Honeywell and Crane Aerospace are investing in these areas to avoid substitution risk.
6. How do FAA and EASA regulations affect the Aircraft Brakes Market?
FAA TSO-C26 and EASA CS-25 set strict performance, flammability, and fatigue-testing requirements for aircraft brakes, adding 12–18 months to certification cycles. The 2024 FAA airworthiness directive on carbon brake oxidation forced operators to inspect and replace affected units, creating aftermarket demand. Compliance costs are estimated at 3–5% of brake system revenue for OEMs.