Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
APAC Military Unmanned Vehicles Market: 16.4% CAGR to 2034
Asia-Pacific Military Unmanned Vehicles Market
APAC Military Unmanned Vehicles Market: 16.4% CAGR to 2034
Asia-Pacific Military Unmanned Vehicles Market by Vehicle Type (Unmanned Aerial Vehicles, Unmanned Ground Vehicles, Unmanned Surface and Underwater Vehicles), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
Unmanned Aerial Vehicles (63% of regional revenue)
Key Insights & Executive Summary: Asia-Pacific Military Unmanned Vehicles Market
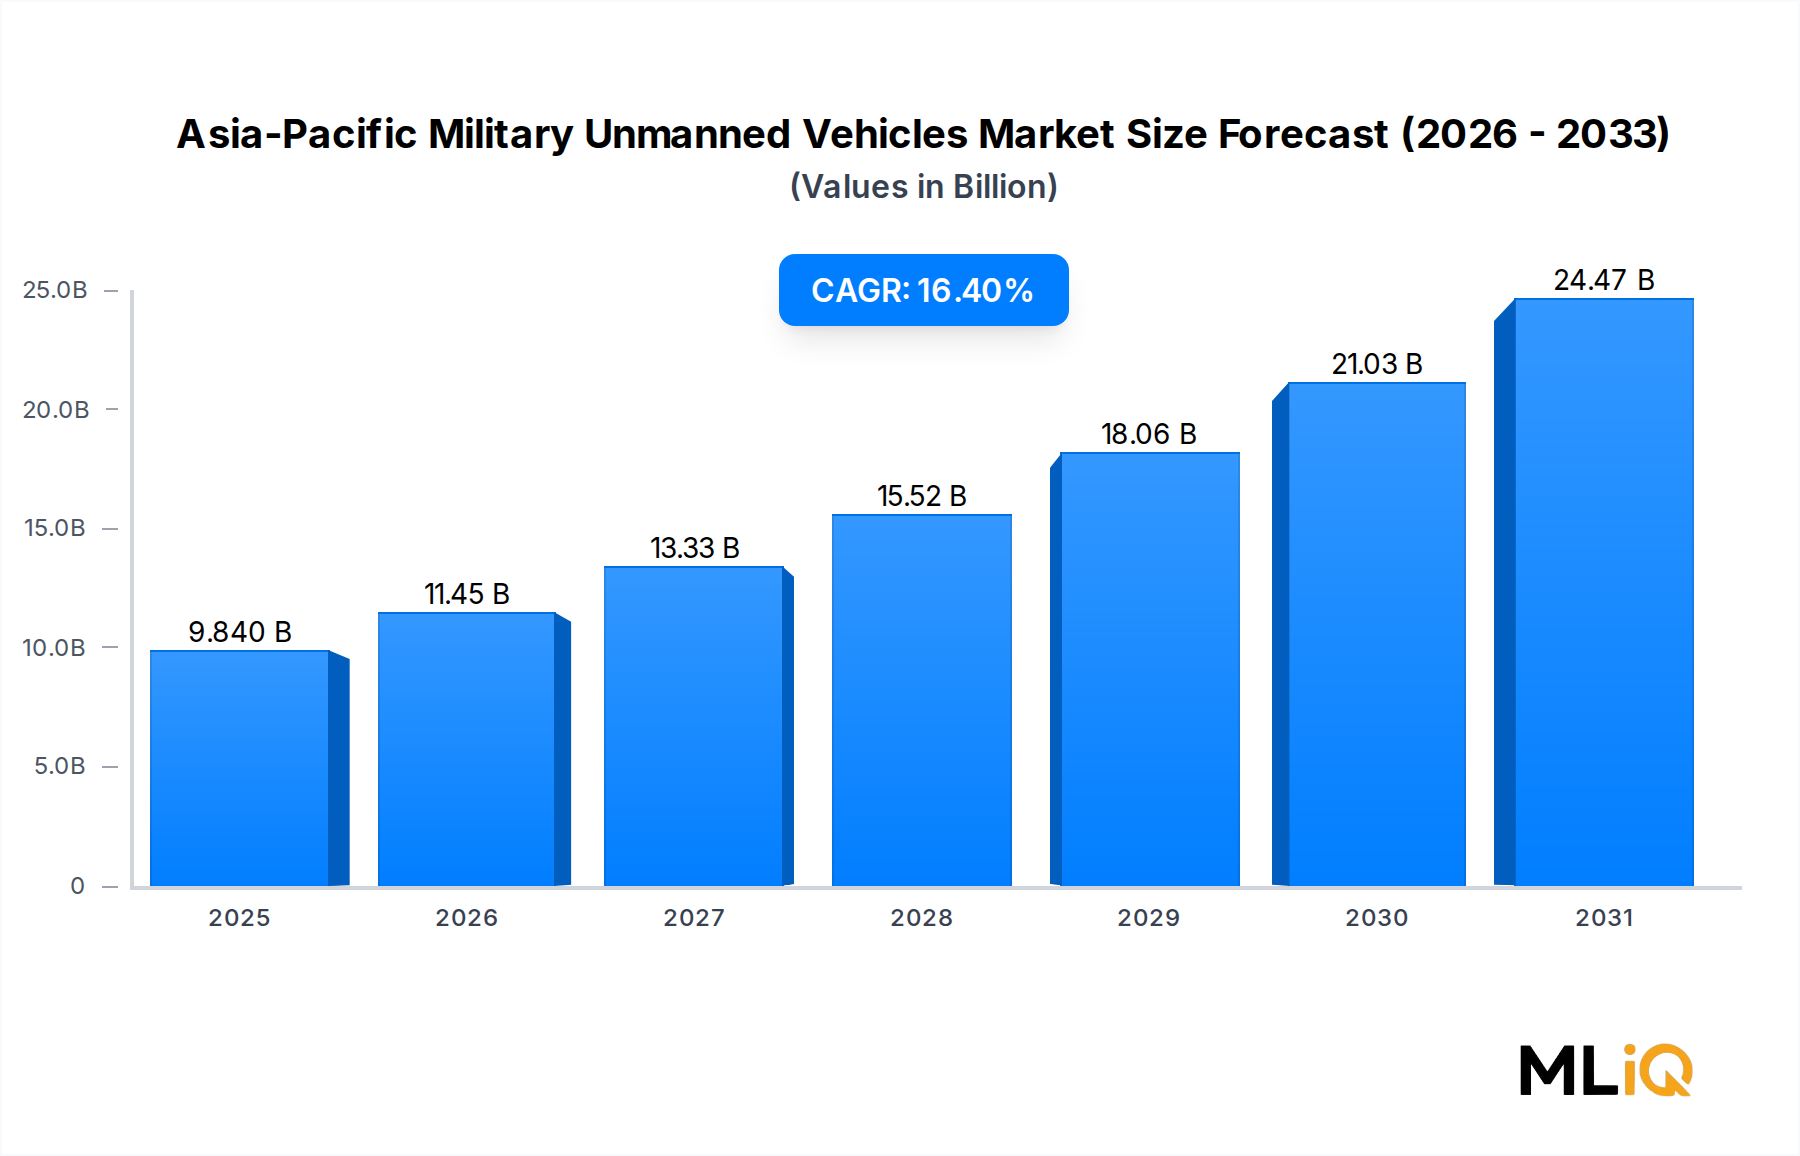
Asia-Pacific Military Unmanned Vehicles Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
9.840 B
2025
11.45 B
2026
13.33 B
2027
15.52 B
2028
18.06 B
2029
21.03 B
2030
24.47 B
2031
Market at a Glance
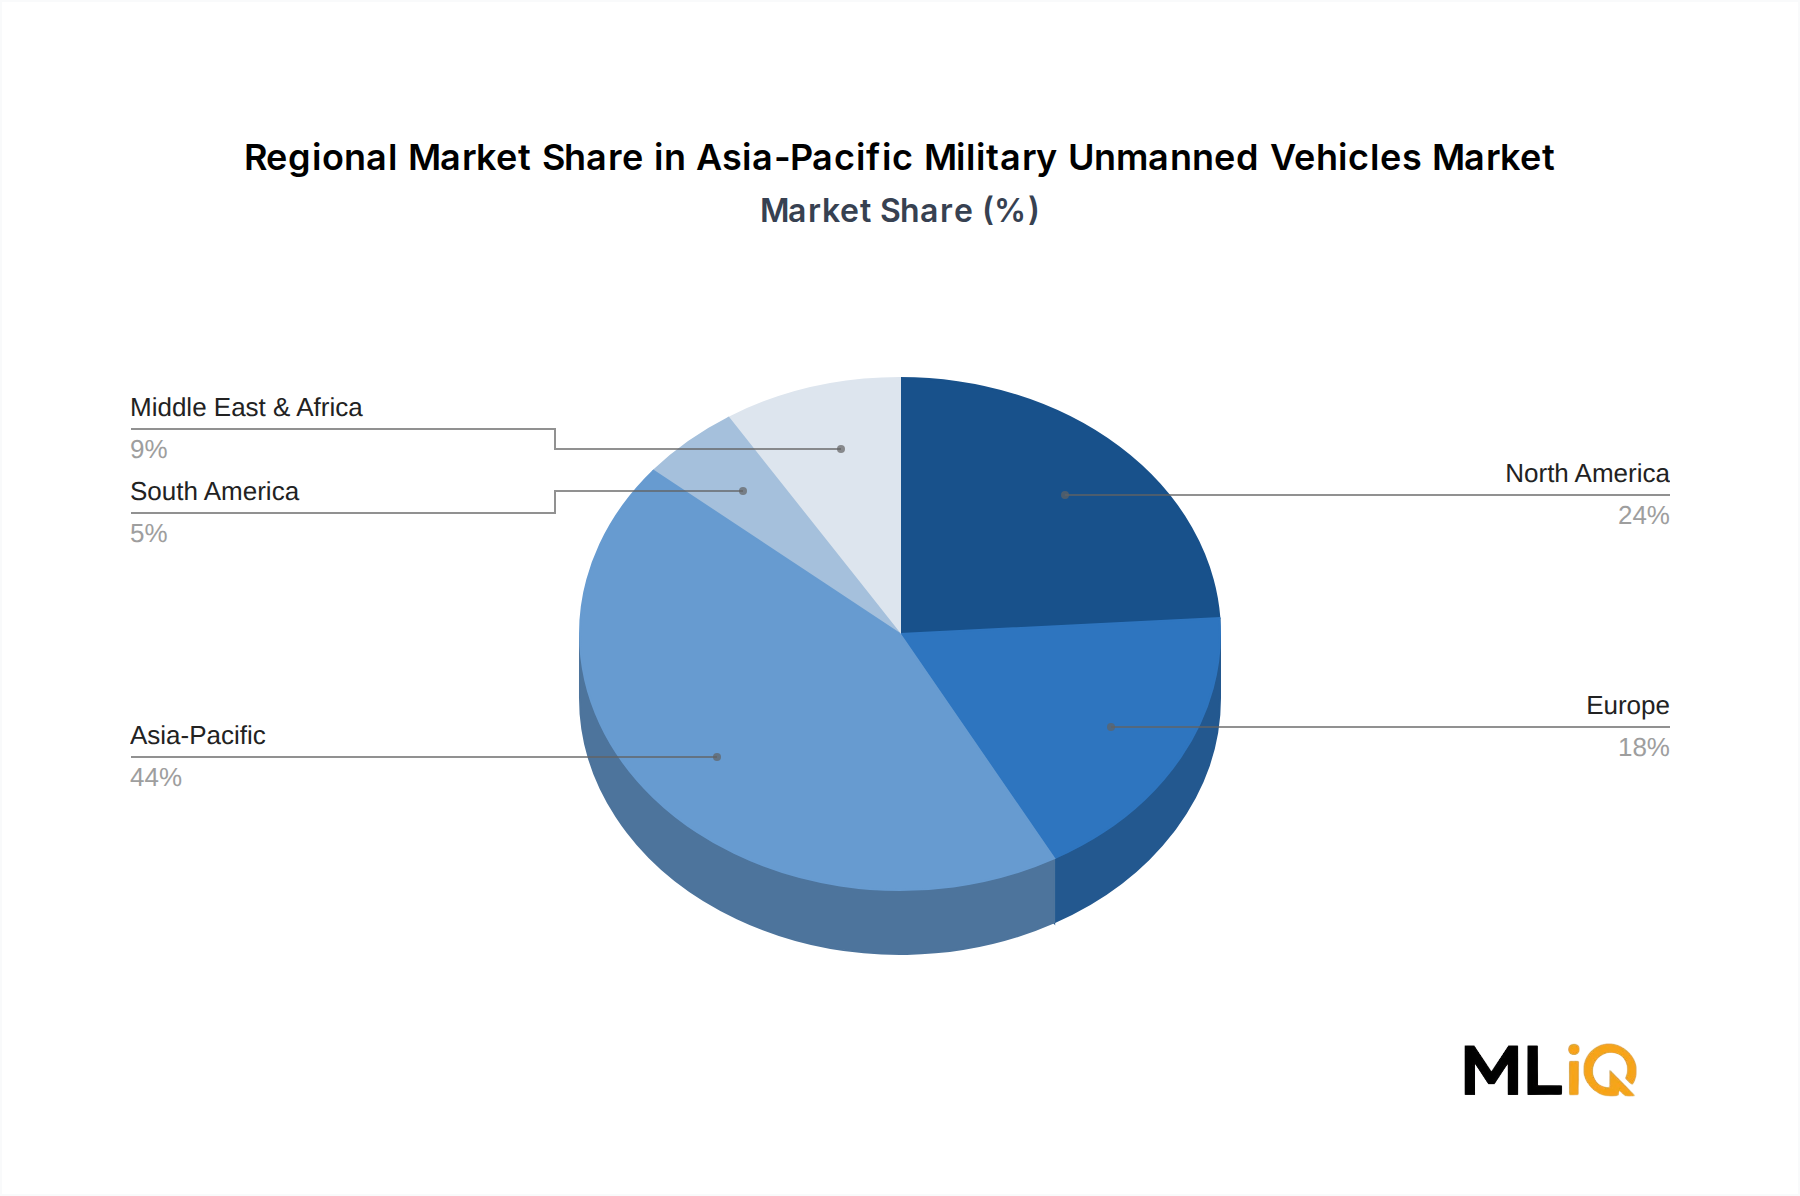
The Asia-Pacific Military Unmanned Vehicles Market closed 2025 at USD 9.84 billion and is forecast to reach USD 38.6 billion by 2034, a 16.4% CAGR across the 2026-2034 window. Within the Global Military Unmanned Vehicles Market, Asia Pacific captures 44% of revenue, ahead of North America at 24% and Europe at 18%. Growth concentrates in three procurement cycles: China's domestic MALE and stealth combat drone programs, India's emergency procurement plus the indigenous TAPAS and Ghatak pipeline, and Japan's island-defence maritime surveillance fleet.
Three structural forces set the pace:
Budget expansion: SIPRI estimates 2024 military spending near USD 314 billion (China), USD 86 billion (India), USD 55 billion (Japan), USD 48 billion (South Korea) and USD 34 billion (Australia).
Attritable mass: Indo-Pacific planners increasingly buy cheaper expendable platforms at volume rather than small fleets of exquisite systems.
Naval autonomy: Undersea and surface unmanned programs now represent 22% of regional unmanned revenue, up from an estimated 14% in 2020.
The Defense Autonomous Systems Market, which spans unmanned platforms, autonomy software and command-and-control layers, is the main channel converting these budgets into revenue. Procurement shifts toward multi-year framework contracts, with service-entry milestones written into tenders rather than prototype demonstrations.
Constraints are equally measurable: 30-40% of regional programs depend on imported engines, EO/IR payloads or flight-control electronics, exposing buyers to export-control delay. Cybersecurity hardening for datalinks and satellite relay adds 5-9% to program cost baselines. Export-licence review times of 6-14 months remain the single largest schedule risk for cross-border sales into ASEAN and South Asia.
Strategic Takeaways
Platforms below USD 5 million per unit will drive unit-volume growth; premium MALE systems will drive revenue growth.
Local assembly requirements are becoming a de facto market entry condition in India, Indonesia and South Korea.
Sustainment and datalink services will outgrow hardware revenue after 2029.
Segment Deep-Dive: Unmanned Aerial Vehicles Dominance in Asia-Pacific Military Unmanned Vehicles Market
The Military Unmanned Aerial Vehicles Market generates 63% of regional segment revenue and is the most contested procurement category in the Indo-Pacific. Demand splits into three tiers:
Tier 1 MALE/HALE: General Atomics MQ-9B SeaGuardian and Heron TP-class platforms, procured in 8-31 unit batches with 20+ hour endurance.
Tier 2 indigenous: India's TAPAS, Indonesia's Elang Hitam, and South Korea's KUS-FS, supported by state-funded development.
Tier 3 attritable: loitering munitions and collaborative combat aircraft such as Boeing's MQ-28 Ghost Bat.
Unit economics favour Tier 3. An attritable airframe at USD 2-4 million can be fielded in squadrons, while a single Tier 1 MALE system with ground segment exceeds USD 30 million. That gap explains why unit volumes rise faster than revenue.
Naval and Undersea Systems: Fastest Growth
The Unmanned Surface and Underwater Vehicles Market is the fastest-compounding cluster at 20.1% CAGR, driven by mine countermeasures, extra-large AUVs for seabed cable surveillance, and surface vessels for maritime domain awareness. Australia, Japan, Singapore and South Korea all fund naval unmanned programs with clear service-entry dates before 2030.
Ground Robotics: Structural, Not Spectacular
The Military Unmanned Ground Vehicles Market grows at 14.2%, weighted toward logistics convoys, explosive ordnance disposal and combat engineering. Adoption is slowed by rugged terrain, spectrum congestion and doctrine gaps rather than by technology limits.
Margin Pressures
Input costs: the Aerospace Grade Composites Market remains tight, with aerospace-grade carbon fiber lead times of 20-40 weeks.
Payload concentration: EO/IR turrets and SAR modules are supplied by a handful of vendors, capping OEM pricing power.
Local content rules: assembly offsets compress gross margin by an estimated 3-6 percentage points on export contracts.
Primary Market Drivers & Growth Restraints in Asia-Pacific Military Unmanned Vehicles Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
IoT and autonomous systems integration across ISR and logistics
High
Short term
Driver
Rising demand for military and defense satellite communication solutions
High
Short to long term
Driver
Attritable platform economics lowering cost per orbit
Medium
Short term
Restraint
Cybersecurity threats to satellite communication links
High
Long term
Restraint
Interference in transmission of data and spectrum congestion
Medium
Short to long term
Restraint
Export licensing and local content mandates
Medium
Short term
Catalyst Evaluation
Autonomy and connectivity are the two multipliers. Edge-compute modules priced below USD 50,000 now deliver onboard target recognition previously requiring a ground station and a dedicated analyst. That reduces crew-per-platform from 3-4 operators to 1, the largest single cost lever in fleet economics.
The Military Satellite Communication Market is the transmission backbone for beyond-line-of-sight control, and demand for protected, anti-jam capacity is rising in step with unmanned fleet size. Regional operators are contracting commercial LEO and GEO capacity alongside sovereign military satellites, which shortens capability timelines from 8-10 years to 3-5 years.
Bottleneck Evaluation
Cyber risk: datalink and ground-segment intrusion attempts scale with fleet size; a single compromised link can neutralize a full orbit.
Interference: dense RF environments near contested maritime zones degrade video and telemetry throughput.
Defence Research and Development Organisation (DRDO)
Indigenous development pipeline
India
Niche
Mitsubishi Heavy Industries Ltd
Heavy platform engineering
Japan
Challenger
Singapore Technologies Engineering Lt
Naval and ground unmanned systems
Singapore, ASEAN
Niche
PT Dirgantara Indonesia
Local airframe manufacture
Indonesia
Niche
Hyundai Motor Group
Ground robotics, mobility platforms
South Korea
Niche
The Military Robotics Market in the region is moderately fragmented, with no vendor above 15% revenue share.
The Boeing Company: leads the attritable combat aircraft category through the MQ-28 Ghost Bat developed with the Royal Australian Air Force.
General Atomics: the benchmark exporter of MALE systems, with MQ-9B orders from India and maritime surveillance operations in Japan.
Lockheed Martin Corporation: positions on mission systems, sensor fusion and command-and-control rather than airframe volume.
Elbit Systems Ltd: supplies UAS mission suites and payloads across ASEAN and South Asia with faster licensing cycles than US primes.
Hanwha Corporation: combines loitering munitions and ground systems with domestic South Korean procurement scale.
Defence Research and Development Organisation (DRDO): anchors India's indigenous pipeline, including TAPAS and stealth UCAV programs.
Mitsubishi Heavy Industries Ltd: holds Japanese heavy engineering capability for national unmanned programs.
Singapore Technologies Engineering Lt: leads ASEAN naval and ground unmanned offerings, including VTOL UAS and UGV families.
PT Dirgantara Indonesia: provides local airframe manufacture and sustainment for Indonesian MALE development.
Hyundai Motor Group: applies automotive mobility and autonomy stacks to military ground robotics.
Strategic Milestones & Recent Developments in Asia-Pacific Military Unmanned Vehicles Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2022
The Boeing Company
Launch
MQ-28 Ghost Bat production expansion in Australia
2023
Elbit Systems Ltd
Partnership
Payload and UAS integration agreements with ASEAN buyers
2024
General Atomics
Contract
31-unit MQ-9B order for India, approx. USD 3.5 billion
2024
Hanwha Corporation
Launch
Expanded loitering munition and unmanned system line
2024
Defence Research and Development Organisation (DRDO)
Test
Flight trials advancing India's MALE and stealth UCAV programs
2025
Singapore Technologies Engineering Lt
Launch
New VTOL UAS and UGV variants for regional export
Chronological Detail
2022: Boeing Australia industrialized MQ-28 Ghost Bat manufacturing, establishing the first Indo-Pacific attritable combat aircraft production line.
2023: Elbit Systems Ltd deepened payload and mission-suite cooperation across ASEAN, prioritising shorter licensing timelines.
2024: India finalized a 31-airframe MQ-9B acquisition spanning naval, army and air force operators, the region's largest single unmanned import contract.
2024: Hanwha Corporation broadened its unmanned portfolio, coupling loitering munitions with ground robotic systems.
2024: DRDO progressed flight trials for indigenous MALE and stealth combat UAV demonstrators.
2025: Singapore Technologies Engineering Lt rolled out export-oriented VTOL UAS and UGV variants targeting ASEAN maritime and urban requirements.
Regional Market Analysis & Growth Corridors for Asia-Pacific Military Unmanned Vehicles Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (2025)
Primary Catalyst
Regulatory Stringency
Asia Pacific
16.4
USD 9.84 billion
Sovereign procurement scale, naval autonomy
Medium to High
North America
12.6
USD 5.4 billion
Attritable aircraft, autonomy software
High
Europe
11.8
USD 4.0 billion
Collaborative combat aircraft programs
High
Middle East & Africa
14.2
USD 2.0 billion
Border surveillance, counter-UAS
Medium
South America
9.4
USD 1.1 billion
Maritime patrol, incremental upgrades
Low to Medium
Fastest-Growing Geographies
India: the fastest-scaling national market, combining a 31-unit MQ-9B import with indigenous TAPAS and Ghatak development.
ASEAN: Indonesia's Elang Hitam and Singapore's ST Engineering portfolio serve smaller sovereign requirements with faster decision cycles.
South Korea: Hanwha and Hyundai-led programs target both domestic force structure and export markets.
Most Mature Markets
Japan: mature maritime ISR operations with sustained MQ-9B-class flight hours and island-defence focus.
Australia: mature attritable aircraft development and naval unmanned integration, with an established industrial base.
China: largest absolute spend, closed to external suppliers, and the primary reason Asia Pacific holds 44% of the Global Military Unmanned Vehicles Market.
Purchasing power is shifting toward sub-regional buyers. ASEAN and Oceania together account for roughly 23% of Asia Pacific unmanned revenue and are the fastest to adopt commercially derived platforms.
Investment, M&A & Funding Activity in Asia-Pacific Military Unmanned Vehicles Market
Capital formation in this space runs through sovereign and strategic channels rather than conventional venture exits.
Sovereign funds and state programs: India's iDEX innovation scheme, Japan's ATLA research funding, and Australia's defence innovation programs seed autonomy, sensor and propulsion startups.
Strategic partnerships: Boeing-Australia, Elbit-ASEAN, and Hanwha-domestic supplier agreements function as quasi-equity arrangements, providing demand certainty in exchange for localization.
Sub-segment capital concentration: autonomy software, counter-UAS, and undersea sensing attract the majority of early-stage funding; airframe manufacturing attracts little external capital because qualification cost exceeds typical venture check sizes.
Acquirer profile: prime contractors acquire autonomy and perception startups to shorten software roadmaps, while naval primes acquire undersea vehicle developers.
Materials remain an investment theme. The Aerospace Grade Composites Market is attracting capacity investment from suppliers seeking to reduce the 20-40 week lead times that constrain airframe output. Valuation multiples for autonomy software firms typically range from 6x to 12x forward revenue, versus 1.5x to 3x for hardware-centric suppliers.
Technology Innovation & R&D Trajectory in Asia-Pacific Military Unmanned Vehicles Market
Three technology clusters define the next procurement cycle.
1. AI-Enabled Autonomy and Swarming
Edge autonomy reduces operator load to one controller per multiple platforms. Adoption is already visible in collaborative combat aircraft programs, with service entry expected between 2028 and 2032. R&D intensity is high: autonomy software budgets typically represent 15-25% of program value in new starts.
2. Attritable Airframes and Additive Manufacturing
Low-observable, additively manufactured airframes shorten production cycles and reduce tooling cost. The Military UAV Flight Control Systems Market is consolidating around a small group of suppliers offering redundant, jam-resistant flight control with integrated mission computing, which raises switching costs for airframers.
3. Undersea Autonomy and Acoustic Mesh Networking
Extra-large AUVs and undersea gliders for seabed infrastructure surveillance represent the most disruptive naval development, threatening the economics of crewed mine countermeasure vessels. Acoustic mesh communications remain the principal technical bottleneck, with effective data rates still measured in kilobits per second.
Incumbent Impact
Autonomy layers reinforce incumbent primes that own mission-system integration.
Additive manufacturing weakens the moat held by traditional airframe tooling suppliers.
Counter-UAS directed energy threatens the economics of low-cost loitering munitions, creating a technology race between offense and defense.
Patent activity concentrates in perception algorithms, swarm control, and anti-jam datalinks, with Chinese and South Korean filings growing fastest on a percentage basis.
Asia-Pacific Military Unmanned Vehicles Market Segmentation
1. Vehicle Type
1.1. Unmanned Aerial Vehicles
1.2. Unmanned Ground Vehicles
1.3. Unmanned Surface and Underwater Vehicles
Asia-Pacific Military Unmanned Vehicles Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Asia-Pacific Military Unmanned Vehicles Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 16.4% from 2020-2034
Segmentation
By Vehicle Type
Unmanned Aerial Vehicles
Unmanned Ground Vehicles
Unmanned Surface and Underwater Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Vehicle Type
5.1.1. Unmanned Aerial Vehicles
5.1.2. Unmanned Ground Vehicles
5.1.3. Unmanned Surface and Underwater Vehicles
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Vehicle Type
6.1.1. Unmanned Aerial Vehicles
6.1.2. Unmanned Ground Vehicles
6.1.3. Unmanned Surface and Underwater Vehicles
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Vehicle Type
7.1.1. Unmanned Aerial Vehicles
7.1.2. Unmanned Ground Vehicles
7.1.3. Unmanned Surface and Underwater Vehicles
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Vehicle Type
8.1.1. Unmanned Aerial Vehicles
8.1.2. Unmanned Ground Vehicles
8.1.3. Unmanned Surface and Underwater Vehicles
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Vehicle Type
9.1.1. Unmanned Aerial Vehicles
9.1.2. Unmanned Ground Vehicles
9.1.3. Unmanned Surface and Underwater Vehicles
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Vehicle Type
10.1.1. Unmanned Aerial Vehicles
10.1.2. Unmanned Ground Vehicles
10.1.3. Unmanned Surface and Underwater Vehicles
11. Competitive Analysis
11.1. Company Profiles
11.1.1. The Boeing Company
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Elbit Systems Ltd
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Lockheed Martin Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. General Atomics
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Defence Research and Development Organisation (DRDO)
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Mitsubishi Heavy Industries Ltd
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. PT Dirgantara Indonesia
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Hanwha Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Hyundai Motor Group
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Singapore Technologies Engineering Lt
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Asia-Pacific Military Unmanned Vehicles Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Vehicle Type 2026 & 2034
Figure 3: North America Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 4: North America Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Vehicle Type 2026 & 2034
Figure 7: South America Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 8: South America Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Vehicle Type 2026 & 2034
Figure 11: Europe Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 12: Europe Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Vehicle Type 2026 & 2034
Figure 15: Middle East & Africa Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 16: Middle East & Africa Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Vehicle Type 2026 & 2034
Figure 19: Asia Pacific Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 20: Asia Pacific Asia-Pacific Military Unmanned Vehicles Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Asia-Pacific Military Unmanned Vehicles Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Vehicle Type 2020 & 2034
Table 2: Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Region 2020 & 2034
Table 3: North America Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Vehicle Type 2020 & 2034
Table 4: North America Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Country 2020 & 2034
Table 5: United States Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 6: Canada Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 7: Mexico Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 8: South America Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Vehicle Type 2020 & 2034
Table 9: South America Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Country 2020 & 2034
Table 10: Brazil Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Argentina Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: Rest of South America Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 13: Europe Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Vehicle Type 2020 & 2034
Table 14: Europe Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Country 2020 & 2034
Table 15: United Kingdom Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: Germany Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: France Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Italy Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Spain Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 20: Russia Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 21: Benelux Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 22: Nordics Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 23: Rest of Europe Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Middle East & Africa Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Vehicle Type 2020 & 2034
Table 25: Middle East & Africa Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Country 2020 & 2034
Table 26: Turkey Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Israel Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: GCC Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: North Africa Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: South Africa Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Middle East & Africa Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Asia Pacific Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Vehicle Type 2020 & 2034
Table 33: Asia Pacific Asia-Pacific Military Unmanned Vehicles Market Revenue billion Forecast, by Country 2020 & 2034
Table 34: China Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: India Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Japan Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: South Korea Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: ASEAN Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: Oceania Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Rest of Asia Pacific Asia-Pacific Military Unmanned Vehicles Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70-80% of total project effort is allocated to primary intelligence gathering through direct interviews, paid expert calls, and structured surveys across the Asia Pacific military unmanned vehicle value chain.
Interviewed company types: UAV airframe and mission-system OEMs; UGV and ground robotics integrators; naval unmanned platform builders for USV and UUV programs; sensor, payload and command-and-control subsystem suppliers; propulsion, composites and advanced materials suppliers.
Interviewed stakeholder designations: Unmanned Systems Program Directors; Defence Procurement and Acquisition Officers; Payload, Sensor and Autonomy Engineering Leads; Military Satellite Communications Architects.
Every report is updated to the date of purchase, with interview transcripts and procurement notices re-validated against the latest budget documents immediately before delivery.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Unmanned Systems Program Directors
30%
Defence Procurement & Acquisition Officers
25%
Payload, Sensor & Autonomy Engineering Leads
25%
Military Satellite Communications Architects
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
UAV Airframe & Mission-System OEMs
30%
UGV & Ground Robotics Integrators
20%
Naval Unmanned Platform Builders (USV/UUV)
15%
Sensor, Payload & C2 Subsystem Suppliers
20%
Propulsion, Composites & Materials Suppliers
15%
Secondary Research & Industry Benchmarking
Secondary sources account for 20-30% of research input, covering filings, tender documents, budget annexes, and technical standards.
Institutional sources include .gov and .org publications, defence white papers, parliamentary budget submissions, and trade association technical reports. Market research websites are excluded from the source base.
Benchmarking covers unit pricing, procurement volumes, industrial offset obligations, and export-licence processing times across China, India, Japan, South Korea, ASEAN, and Oceania.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously and reconciled through multi-level data triangulation at segment, national, and platform level.
Bottom-up quantitative inputs include: (1) count of active unmanned platform programs per country and announced unit quantities; (2) annual production units by platform class multiplied by average selling price; (3) share of national defence procurement budgets allocated to unmanned systems; (4) platform attrition and replacement cycles of 8-15 years for MALE/HALE airframes and 3-5 years for attritable systems; (5) number of naval vessels per fleet requiring embarked unmanned systems.
Top-down validation anchors regional totals to published defence expenditure aggregates and unmanned system budget lines, then distributes across vehicle type and geography.
Segment CAGRs are derived independently for Unmanned Aerial Vehicles, Unmanned Ground Vehicles, and Unmanned Surface and Underwater Vehicles, then weighted to reconcile with the regional blended growth rate.
Data Accuracy & Quality Check
The methodology delivers a guaranteed estimated data accuracy level of 85-90%, validated through multi-level data triangulation across primary interviews, secondary filings, and budget documentation.
Every data point is cross-checked against at least two independent sources; divergences above 5% trigger a follow-up interview or a documented reconciliation note.
Segment shares are sanity-checked against platform-level unit forecasts to prevent overstatement of high-value but low-volume categories.
Draft findings undergo internal peer review by sector specialists and, where available, external validation with procurement officials or industry association contacts.
Data is version-controlled, and every report is updated to the date of purchase so that procurement awards, contract values and program timelines reflect the most recent public record.
Frequently Asked Questions
1. Which region dominates the Asia-Pacific Military Unmanned Vehicles Market and why?
Asia Pacific itself leads with roughly 44% of global military unmanned vehicle revenue, ahead of North America at 24% and Europe at 18%. The region's lead rests on concurrent procurement cycles in China, India, Japan, South Korea and Australia, where unmanned platforms are funded as core force structure rather than experimental add-ons. China's estimated 2024 defense budget of about USD 314 billion and India's MQ-9B purchase of 31 airframes underpin that volume.
2. What disruptive technologies and emerging substitutes are reshaping this market?
AI-enabled autonomy stacks, attritable loitering munitions, and undersea gliders are displacing single-purpose manned platforms in surveillance and strike roles. Directed-energy counter-UAS systems are emerging as a substitute for kinetic interception economics, with per-shot cost falling from thousands of dollars to single-digit dollars per engagement at prototype maturity. Autonomous swarming also reduces the number of operators required per orbit, compressing the main cost driver of legacy UAV fleets.
3. How are raw material sourcing and supply chain constraints affecting production?
Airframe-grade carbon fiber, titanium forgings, and rare-earth magnets for electric propulsion remain the tightest inputs, with lead times for aerospace-grade composites stretching 20 to 40 weeks. Roughly 30 to 40% of regional programs still depend on imported engines, EO/IR payloads, or flight-control electronics, exposing buyers to export-control friction. Suppliers such as Elbit Systems and General Atomics manage this by localizing final assembly with partners like PT Dirgantara Indonesia and Hanwha.
4. Which geography is growing fastest and where are the emerging opportunities?
India, South Korea and the ASEAN bloc are the fastest-growing sub-geographies, with regional growth anchored by a 16.4% CAGR and the naval unmanned cluster expanding at about 20.1%. India's indigenous TAPAS and Ghatak programs plus a 31-unit MQ-9B order create a dual local-import pipeline, while Indonesia's Elang Hitam and Singapore's ST Engineering portfolio serve smaller sovereign requirements. Australia's MQ-28 Ghost Bat adds a credible attritable combat aircraft export base.
5. Who are the leading companies and how concentrated is the competitive landscape?
No single vendor exceeds 15% of Asia Pacific unmanned revenue, making the market moderately fragmented across primes and national champions. The Boeing Company, General Atomics, Lockheed Martin Corporation and Elbit Systems Ltd hold the export-facing share, while DRDO, Mitsubishi Heavy Industries Ltd, Hanwha Corporation, Hyundai Motor Group and Singapore Technologies Engineering Lt dominate domestic procurement. Chinese state primes absorb the single largest national block but remain largely closed to external competition.
6. What barriers to entry and competitive moats protect incumbent vendors?
Certification, ITAR and export-license regimes, and multi-year logistics sustainment contracts form the primary moats, with platform qualification cycles running 3 to 7 years. Incumbents also hold proprietary datalinks, mission software, and interoperability certification with allied command architectures, which are costly to replicate. New entrants typically enter through subsystem supply, autonomy software, or small UAS niches where qualification thresholds are lower and unit volumes are higher.