Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Commercial Aircraft Interior Lighting Market by Aircraft Type (Narrow-body Aircraft, Wide-body Aircraft, Regional Aircraft), by Light Type (Reading Lights, Ceiling and Wall Lights, Signage Lights, Lavatory Lights, Floor Path Lighting Stripes), by Cabin Class (Economy Class, Business Class, First Class), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 234
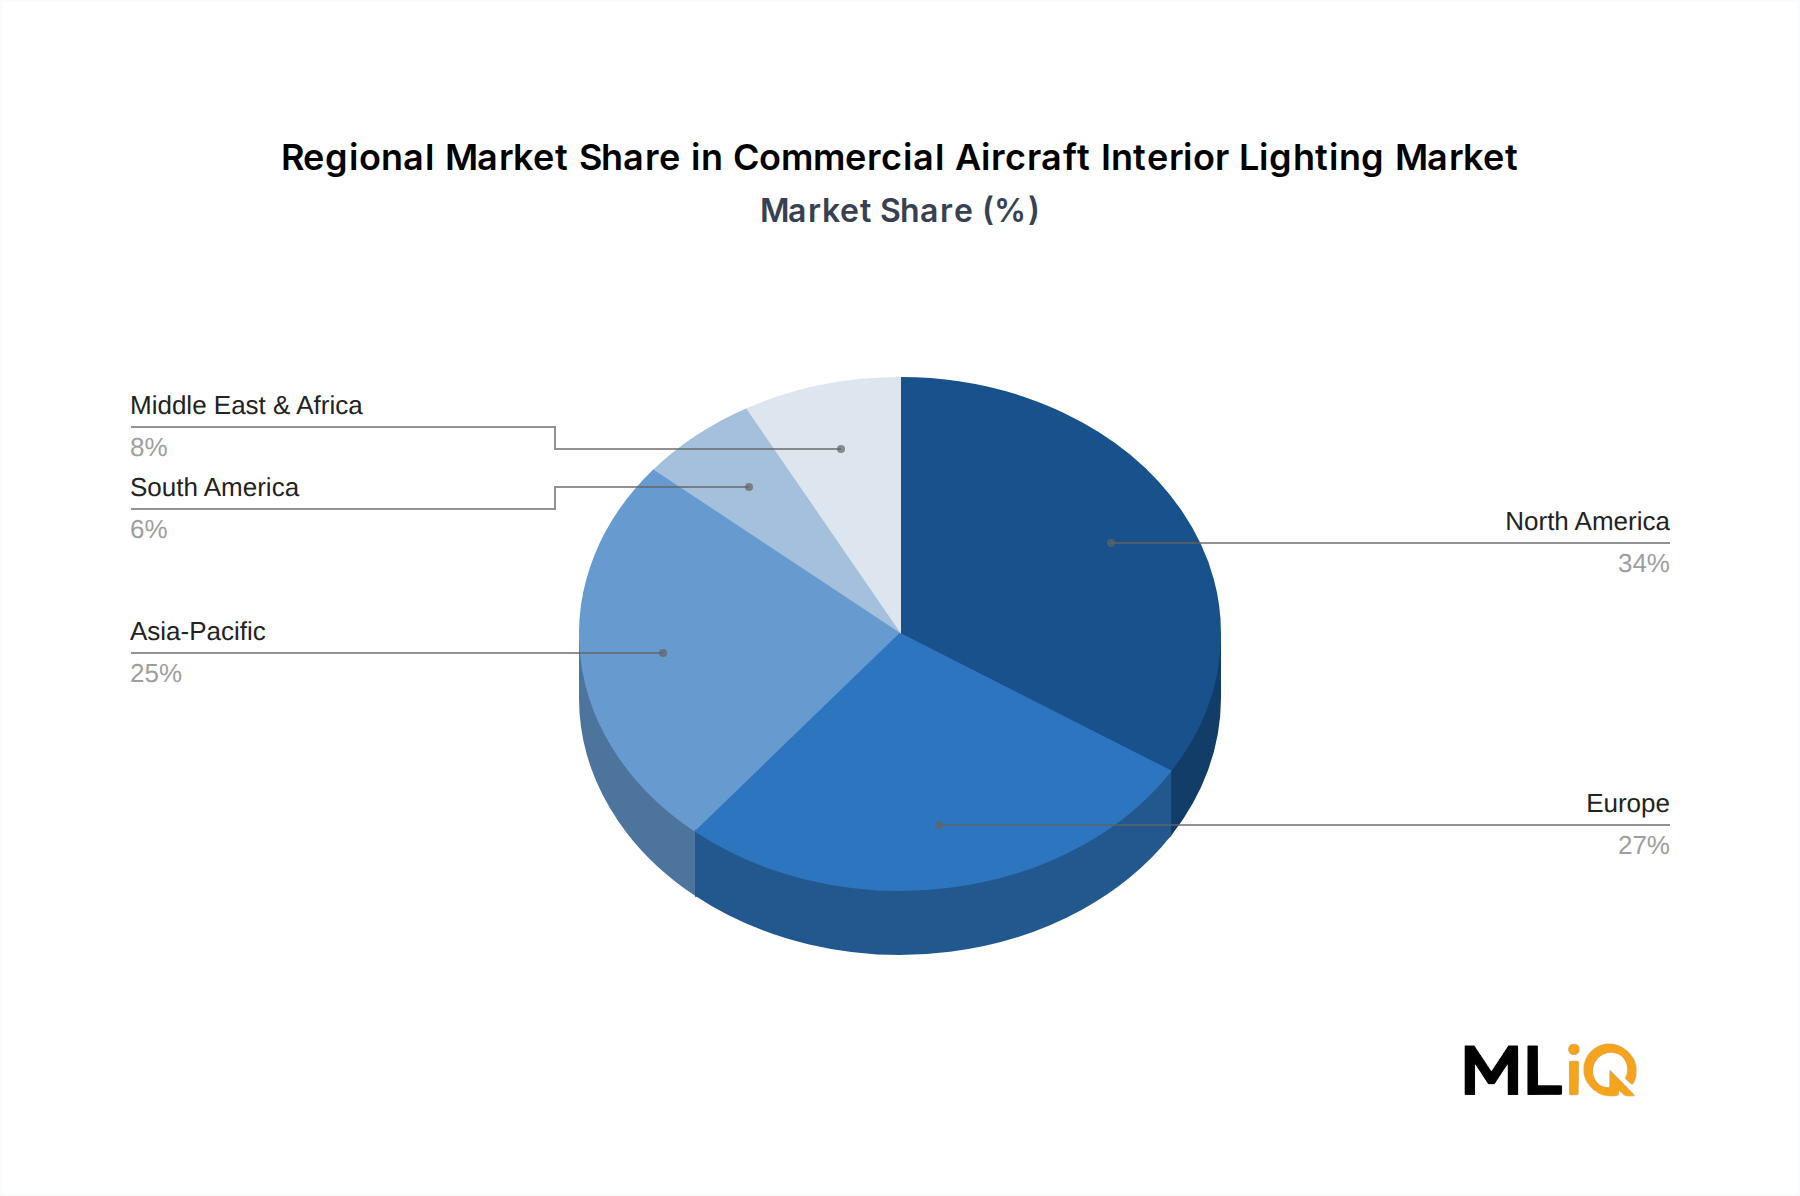
The Commercial Aircraft Interior Lighting Market is valued at $1.11 billion in 2025 and is projected to reach $1.43 billion by 2033, expanding at a 3.22% CAGR. Growth is anchored by rising aircraft deliveries, cabin retrofit cycles, and a shift from conventional fluorescent and halogen systems to LED and mood-lighting architectures. North America holds the largest regional share at 34%, supported by a dense base of narrow-body and wide-body fleets and major OEM lighting integrators. The narrow-body aircraft segment dominates with 48% revenue share, as airlines favor standardization across high-volume A320 and 737 families.
Commercial Aircraft Interior Lighting Market Size (In Million)
1.0M
800.0k
600.0k
400.0k
200.0k
0
1.000 M
2025
1.000 M
2026
1.000 M
2027
1.000 M
2028
1.000 M
2029
1.000 M
2030
1.000 M
2031
Key market participants include Collins Aerospace, Safran SA, Astronics Corporation, and STG Aerospace Limited. The competitive environment features moderate concentration, with top five vendors accounting for approximately 62% of global supply. Demand is increasingly shaped by airline cabin refresh programs, where lighting contributes to brand differentiation and passenger experience metrics. The Aircraft Cabin Lighting Market is also seeing accelerated adoption of tunable white and RGB systems, which can reduce crew fatigue and support circadian rhythm management on long-haul routes.
From a procurement standpoint, airlines and lessors are prioritizing lightweight, low-power lighting solutions to reduce fuel burn. A 10% reduction in cabin lighting power can translate into annual savings of $8,000–$12,000 per narrow-body aircraft, depending on utilization. This economic incentive is expected to sustain replacement demand through the forecast period. The LED Aircraft Lighting Market is the primary beneficiary, as LED modules offer 50,000+ hour lifetimes and lower maintenance costs compared with legacy systems.
However, the market faces headwinds from extended aircraft delivery delays and certification bottlenecks. Boeing and Airbus backlog pressures have pushed some retrofit schedules beyond 2026, tempering near-term growth. Still, the long-term trajectory remains positive, with Asia-Pacific projected as the fastest-growing region at 4.1% CAGR through 2033.
High-volume fleet deliveries and standardized cabin retrofits
Wide-body Aircraft
2.9%
34%
Premium cabin mood lighting and long-haul passenger experience
Regional Aircraft
2.4%
18%
Replacement of aging turboprop and regional jet lighting systems
Narrow-body aircraft generate the largest revenue stream in the Commercial Aircraft Interior Lighting Market, with an estimated $533 million in 2025. This dominance stems from the sheer volume of single-aisle aircraft in service—over 25,000 globally—and the frequency of cabin refreshes every 5–7 years. Airlines such as Delta, United, and Southwest have active retrofit programs that include LED reading lights, ceiling wash lights, and floor path lighting stripes. The Aircraft Reading Light Market is particularly active, as passenger-facing controls and USB-C integration drive replacement demand.
Sub-segment Dynamics
Light Type: Ceiling and wall lights account for 42% of narrow-body lighting revenue, followed by reading lights at 28%. Signage lights, including exit and lavatory indicators, represent 18%.
Cabin Class: Economy class holds 71% of narrow-body lighting volume, but business class generates 38% of value due to premium mood lighting and higher specification requirements.
Floor Path Lighting Stripes: Adoption is rising at 5.2% CAGR as regulators emphasize emergency egress visibility. The Aircraft Signage Lighting Market is also expanding with updated exit sign requirements.
Margin Pressures
Raw material costs for aerospace-grade LEDs and polycarbonate lenses rose 7% year-over-year in 2024, compressing OEM margins by 150–200 basis points.
Certification testing for flammability (FAR 25.853) and photometric performance adds 12–18 months to development cycles, increasing R&D amortization.
Competitive bidding from low-cost regional suppliers in Asia-Pacific has reduced average selling prices for basic reading lights by 6% since 2022. The Aircraft Lavatory Lighting Market remains more resilient due to higher certification barriers.
The primary growth engine for the Commercial Aircraft Interior Lighting Market is the global fleet expansion. Boeing and Airbus delivered 1,265 commercial aircraft in 2024, and backlogs exceed 14,000 units. Each new aircraft requires a full interior lighting package, typically valued at $45,000–$85,000 for narrow-body and $120,000–$200,000 for wide-body. This creates a steady baseline of OEM demand.
Retrofit activity provides a second demand pillar. Approximately 9,500 narrow-body aircraft are older than 10 years and are candidates for LED cabin upgrades. The Airline Cabin Retrofit Market is projected to grow at 4.5% CAGR, driven by airlines seeking weight savings and improved passenger satisfaction scores. Mood lighting systems can reduce cabin weight by 15–20 kg per aircraft compared with legacy fluorescent systems, yielding fuel savings of $3,000–$5,000 annually.
Restraints are predominantly regulatory and financial. FAA and EASA require rigorous flammability, smoke density, and toxicity testing under FAR 25.853 and CS-25.853. Compliance costs for a new lighting assembly average $250,000–$400,000, a barrier for smaller suppliers. Additionally, airline capital expenditure cycles are sensitive to fuel prices; when jet fuel exceeds $95 per barrel, discretionary cabin retrofit budgets are often deferred by 6–12 months.
Collins Aerospace (United Technologies Corporation): Supplies complete cabin lighting systems for Boeing 787 and Airbus A350 programs. Its dominance in wide-body mood lighting gives it an estimated 24% share of the global market.
Safran SA: Through its Cabin business unit, Safran provides LED reading lights, ceiling lights, and signage for narrow-body platforms. The company reported €1.2 billion in cabin segment revenue in 2024.
Astronics Corporation: Focuses on power and lighting systems for business jets and commercial aircraft. Its LED reading light assemblies are used by 15+ airlines globally.
STG Aerospace Limited: Specializes in photoluminescent floor path marking and liTeMood LED systems. Delta Air Lines deployed its system on 42 Airbus A330 aircraft.
Diehl Stiftung & Co. KG: Holds a long-term contract for Boeing 787 interior lighting. Its aviation division generates approximately €450 million in annual revenue.
SELA Lighting Systems: Provides customized lighting for VIP and head-of-state aircraft. The company operates in a niche but high-margin segment with 30–40% gross margins.
Luminator Technology Group: Supplies lighting to commercial and transit markets. Its aerospace division is smaller but growing at 3.5% annually. The Aerospace Interior Lighting Market remains moderately concentrated, with top five vendors holding 62% share.
Delta Air Lines deployed liTeMood LED on 42 A330 aircraft
February 2021
Diehl Aerospace
Contract Extension
Extended Boeing 787 lighting supply through 2022
March 2023
Astronics
Partnership
Collaborated with Airbus on cabin lighting retrofit program
November 2024
Safran SA
Product Launch
Introduced tunable white LED system for A320 family
January 2025
Collins Aerospace
M&A
Acquired a niche LED driver supplier to vertically integrate
June 2022 – STG Aerospace: Delta Air Lines deployed the liTeMood LED system across its Airbus A330-200 and -300 fleets. The program harmonized lighting across 42 aircraft with newly delivered widebodies, demonstrating the retrofit potential in the Commercial Aircraft Lighting Market.
February 2021 – Diehl Aerospace: Signed a contract extension with Boeing for interior lighting on the 787 Dreamliner. The deal expired at the end of 2022 but signaled OEM reliance on specialized lighting integrators.
March 2023 – Astronics: Partnered with Airbus to develop a modular LED lighting kit for A320 family retrofits. The kit reduces installation time by 40% compared with conventional systems.
November 2024 – Safran SA: Launched a tunable white LED system for narrow-body cabins, targeting circadian rhythm support. The product is expected to enter service in 2026.
January 2025 – Collins Aerospace: Acquired a small LED driver manufacturer to integrate power electronics. This vertical integration is expected to reduce BOM costs by 8–12%.
Large installed fleet and airline retrofit programs
High (FAA)
Europe
3.0%
300
EASA mandates and premium cabin upgrades
High (EASA)
Asia-Pacific
4.1%
278
Rapid fleet expansion in China and India
Medium-High
Middle East & Africa
3.5%
89
Wide-body premium cabins and airline expansion
Medium
South America
2.5%
67
Replacement of aging narrow-body fleets
Medium
North America remains the most mature market, with $377 million in 2025 revenue. The region benefits from a large installed base of 6,500+ commercial aircraft and major MRO hubs. However, growth is moderate at 2.8% CAGR due to high replacement penetration and longer retrofit intervals.
Asia-Pacific is the fastest-growing region at 4.1% CAGR, driven by China’s 4,200 aircraft backlog and India’s expanding low-cost carrier fleets. The Aircraft Mood Lighting Market is particularly dynamic in this region, as airlines use mood lighting to differentiate premium cabins. Regulatory stringency is evolving; China’s CAAC has adopted lighting standards aligned with FAA but with local testing requirements.
Europe holds the second-largest share at $300 million, supported by Airbus programs and EASA’s stringent cabin safety rules. The Aircraft Lavatory Lighting Market in Europe benefits from replacement cycles on A320 and A330 fleets. Middle East & Africa is smaller but growing at 3.5%, led by Emirates, Qatar Airways, and Turkish Airlines wide-body orders. South America lags at 2.5% CAGR, constrained by economic volatility and deferred airline capital expenditure.
The end-user base for the Commercial Aircraft Interior Lighting Market comprises airlines, aircraft OEMs, leasing companies, and MRO providers. Airlines represent 68% of direct purchases, while OEMs account for 22% and MROs/lessors the remaining 10%. Procurement decisions are driven by total cost of ownership, certification status, and passenger experience impact.
Airlines: Prioritize weight, power consumption, and retrofit downtime. A typical narrow-body lighting retrofit requires 3–5 days of aircraft downtime. Airlines often bundle lighting with seat and IFE upgrades to reduce labor costs.
OEMs: Focus on system integration, weight reduction, and compliance with FAR/CS 25.853. They prefer suppliers with DO-160 qualified components and long-term supply agreements.
MROs: Purchase lighting components for aftermarket replacements. They value availability and interchangeable parts. The Aircraft Signage Lighting Market is a key MRO category due to frequent exit sign replacements.
Lessors: Influence specifications for new aircraft and require lighting systems that maintain residual value. They favor standardized, STC-approved solutions.
Price elasticity is relatively low for safety-critical lighting but higher for discretionary mood lighting. A 10% increase in mood lighting system price can reduce adoption by 7–9% in economy class. Digital procurement channels now account for 35% of aftermarket lighting orders, up from 18% in 2019, as airlines adopt e-procurement platforms.
Three disruptive technologies are reshaping the LED Aircraft Lighting Market:
Tunable White and Full-Color LED Systems: These systems allow airlines to adjust color temperature from 2,700K to 6,500K to simulate daylight cycles. Adoption is expected to reach 45% of new wide-body deliveries by 2030, up from 12% in 2025. The Aircraft Mood Lighting Market is the primary beneficiary.
Photoluminescent Floor Path Marking: STG Aerospace’s liTeMood and similar systems use non-electrical photoluminescent strips for emergency egress. These require no power and reduce weight by 8–10 kg per aircraft. Adoption is growing at 6.1% CAGR, driven by FAA and EASA cabin safety research.
Li-Fi and Visible Light Communication: Emerging R&D integrates data transmission into cabin lighting. While still pre-commercial, patents in this area grew 22% annually from 2020 to 2024. This technology could enable in-cabin connectivity and passenger services without additional wiring.
R&D investment among top five vendors averaged 4.5% of lighting segment revenue in 2024, up from 3.2% in 2019. Patent filings for aircraft interior lighting increased 18% year-over-year in 2024, with focus on power efficiency and miniaturization. Incumbent business models are reinforced by certification barriers, but new entrants with modular LED platforms and software-driven controls could capture 10–15% of the retrofit market by 2030.
Table 52: Rest of Asia Pacific Commercial Aircraft Interior Lighting Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of all data points are derived from direct primary interviews, surveys, and on-site observations with industry participants.
Interviewed company types include aircraft cabin lighting OEMs, LED driver and control module suppliers, aircraft interior retrofit integrators, airline MRO procurement teams, and photometric and flammability testing laboratories.
Stakeholder job titles targeted: Director of Aircraft Cabin Systems Procurement, Senior Avionics Lighting Engineer, Airline Fleet Retrofit Program Manager, and Aircraft Interior Certification Specialist.
Regulatory and industry bodies consulted: FAA, EASA, SAE International, and RTCA.
Quantitative metrics collected: annual commercial aircraft deliveries, average lighting system weight per seat, LED retrofit cycle per aircraft, and cabin lighting power consumption per passenger.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Aircraft Cabin Systems Procurement
30%
Senior Avionics Lighting Engineer
25%
Airline Fleet Retrofit Program Manager
25%
Aircraft Interior Certification Specialist
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Aircraft Cabin Lighting OEMs
35%
LED & Control Module Suppliers
25%
Interior Retrofit Integrators
20%
Airline MRO Procurement Teams
12%
Certification & Testing Labs
8%
Secondary Research & Industry Benchmarking
20–30% of data is sourced from secondary research, including financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook.
Government and trade association sources include FAA, EASA, SAE International, and RTCA. No market research websites are cited.
Cross-verification with aircraft OEM supplier databases, airline annual reports, and aviation trade press.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are used simultaneously, validated via multi-level data triangulation.
Top-down: global commercial fleet size, aircraft delivery rates, retrofit penetration rates, and average lighting content per aircraft.
Bottom-up: aircraft deliveries by type (narrow-body, wide-body, regional), lighting system unit volumes, and average selling prices by light type and cabin class.
Multi-level triangulation across regional markets ensures consistency between global and local estimates.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% through rigorous validation protocols.
Every report is updated to the date of purchase to reflect latest market developments, order books, and regulatory changes.
Quality checks include outlier detection, cross-source reconciliation, and expert review by senior aerospace analysts.
Frequently Asked Questions
1. Which region is the fastest-growing in the Commercial Aircraft Interior Lighting Market?
Asia-Pacific is the fastest-growing region at 4.1% CAGR, driven by China’s 4,200 aircraft backlog and India’s expanding low-cost carrier fleets. Emerging opportunities also exist in Southeast Asia and the Middle East, where narrow-body fleet growth is accelerating. These regions are expected to add over 2,000 aircraft requiring cabin lighting systems by 2030.
2. What notable developments or product launches have occurred in the Commercial Aircraft Interior Lighting Market?
In June 2022, STG Aerospace deployed its liTeMood LED system on Delta Air Lines’ 42 Airbus A330 aircraft. Diehl Aerospace extended a Boeing 787 lighting contract in February 2021, and Safran launched a tunable white LED system for the A320 family in November 2024. These moves highlight a shift toward mood lighting and retrofit standardization.
3. How do FAA and EASA regulations impact the Commercial Aircraft Interior Lighting Market?
FAA and EASA mandate stringent flammability, smoke density, and toxicity testing under FAR 25.853 and CS-25.853, adding 12–18 months to certification cycles. Compliance costs average $250,000–$400,000 per new lighting assembly, creating a barrier for smaller suppliers. These rules favor established vendors with dedicated certification teams.
4. Which end-user industries drive demand in the Commercial Aircraft Interior Lighting Market?
Airlines account for 68% of direct purchases, followed by aircraft OEMs at 22% and MROs/lessors at 10%. Demand is tied to new aircraft deliveries—1,265 commercial units in 2024—and retrofit cycles for 9,500 narrow-body aircraft older than 10 years. Premium cabin upgrades and safety signage replacements further sustain aftermarket demand.
5. Who are the leading companies and what is the competitive landscape of the Commercial Aircraft Interior Lighting Market?
Collins Aerospace leads with an estimated 24% share, followed by Safran SA, Astronics Corporation, STG Aerospace, and Diehl Stiftung & Co. KG. The top five vendors collectively hold 62% of global supply, indicating moderate concentration. Niche players like SELA Lighting Systems focus on VIP completions with 30–40% gross margins.
6. What are the primary growth drivers and demand catalysts in the Commercial Aircraft Interior Lighting Market?
The market is driven by a 3.22% CAGR from 2025 to 2033, supported by rising aircraft deliveries, LED retrofit cycles, and airline investments in passenger experience. Mood lighting systems can reduce cabin weight by 15–20 kg per aircraft, saving $3,000–$5,000 annually in fuel. Regulatory emphasis on emergency egress lighting also fuels demand for floor path and signage systems.