Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Latin America Inflight Services Market Forecast to 2033
Latin America Inflight Services Market
Latin America Inflight Services Market Forecast to 2033
Latin America Inflight Services Market by Food Type (Meals, Bakery and Confectionary, Beverages, Other Food Types), by Flight Service Type (Full Service Carriers, Low-Cost Carriers, Hybrid and Other Service Types), by Aircraft Seating Class (Economy Class, Business Class, First Class), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 14, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: Latin America Inflight Services Market
The Latin America inflight services market is projected to grow from USD 1.22 billion in 2025 to USD 2.60 billion by 2033, registering a 9.91% CAGR. This expansion is tied to airline capacity restoration, rising international passenger traffic, and higher premium cabin penetration on regional routes. The Inflight Catering Services Market remains the core revenue engine, with meals accounting for over 60% of food-type spend.
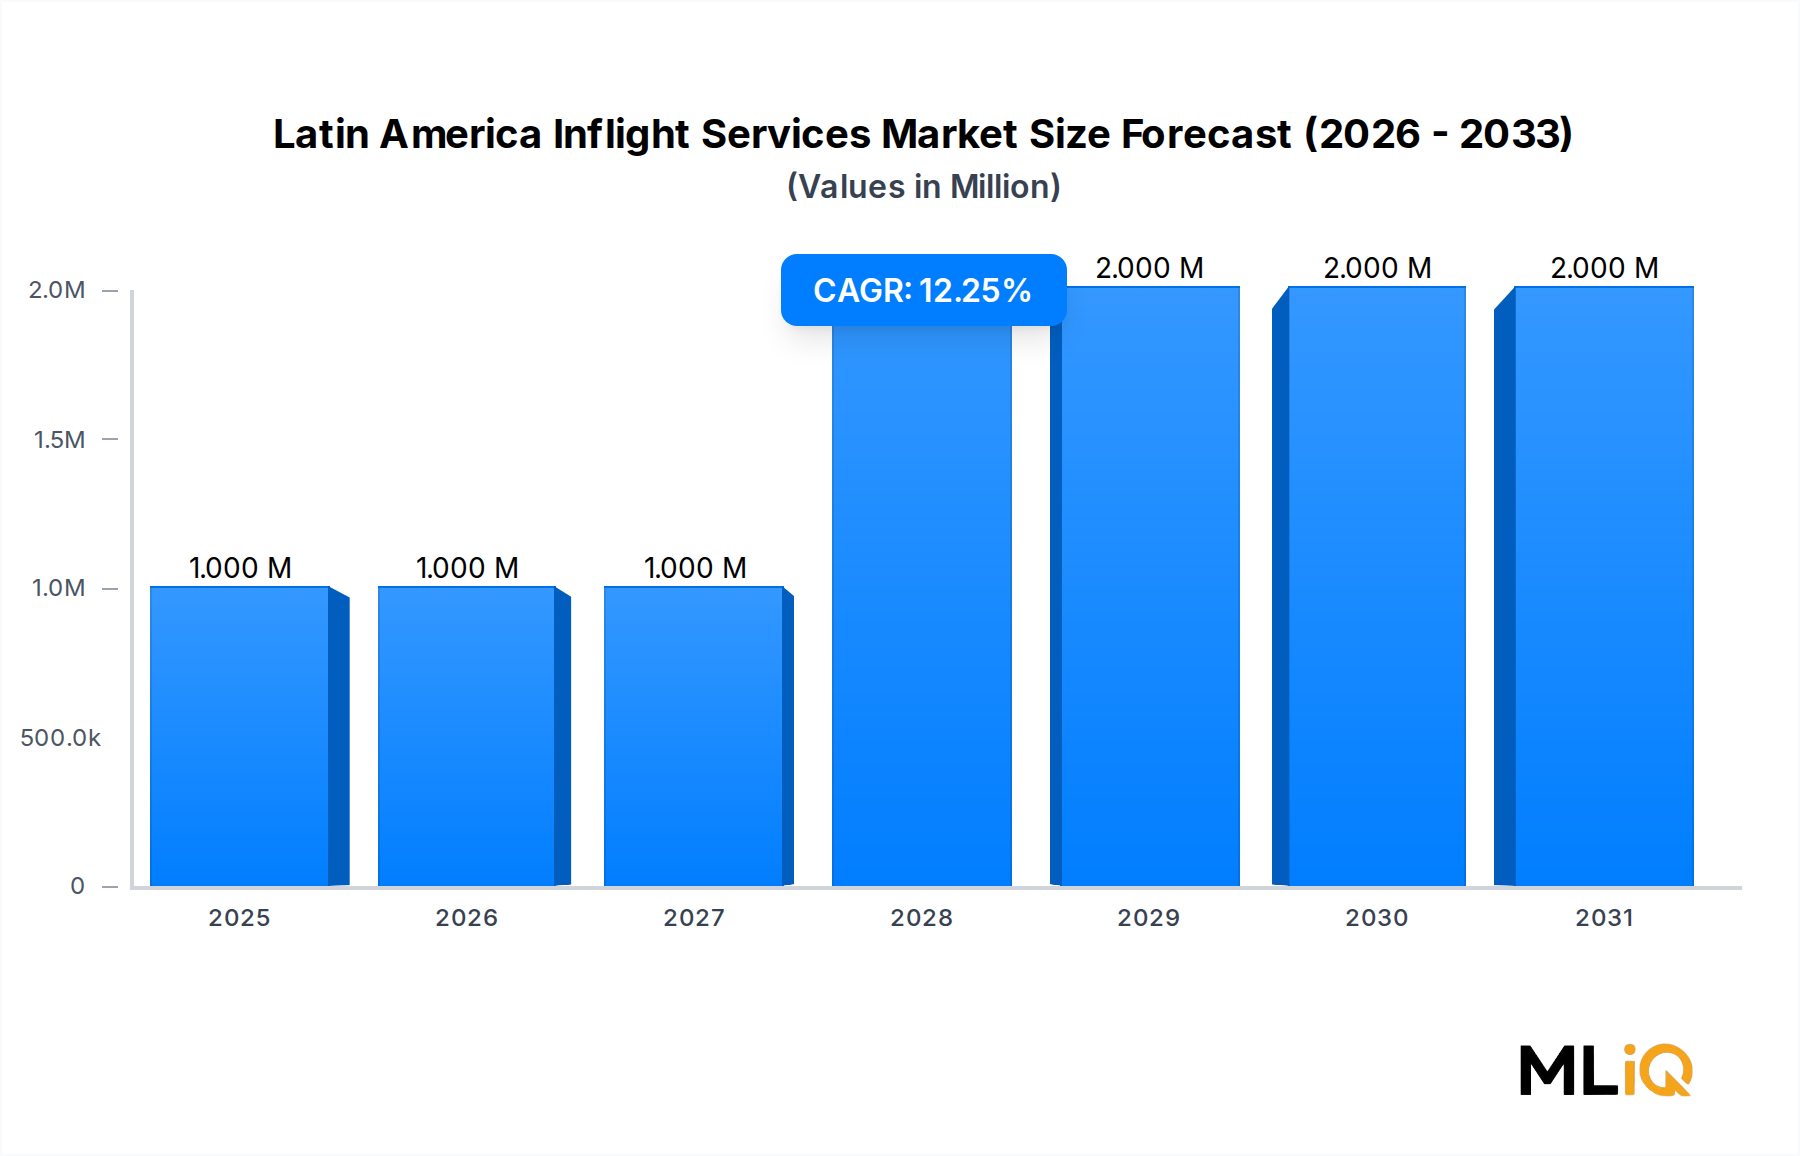
Latin America Inflight Services Market Size (In Million)
2.0M
1.5M
1.0M
500.0k
0
1.000 M
2025
1.000 M
2026
1.000 M
2027
2.000 M
2028
2.000 M
2029
2.000 M
2030
2.000 M
2031
Airlines in Brazil, Mexico, Colombia, and Chile are expanding catering contracts as fleet modernization adds narrow-body and wide-body aircraft. The Airline Meal Services Market benefits from longer average stage lengths on routes such as São Paulo–Bogotá and Santiago–Lima. The Inflight Beverage Services Market is also gaining traction as carriers upsell premium beverages in business cabins. Full Service Carrier Catering Market demand is rising faster than Low-Cost Carrier Inflight Services Market demand, though low-cost carriers are increasing buy-on-board food sales.
Key strategic takeaways:
South America will contribute the largest share, with Brazil and Argentina representing 58% of regional inflight services revenue.
Economy Class Catering Market remains volume-heavy, but Business Class Dining Market generates higher per-passenger margins.
Aircraft Galley Equipment Market innovation, including lighter carts and IoT temperature sensors, improves operational efficiency.
Airline Food Safety Compliance Market requirements, led by ANVISA and SENASA, raise supplier qualification costs but reduce recall risk.
The market faces cost inflation in labor and cold-chain logistics, yet airlines continue outsourcing to LSG Sky Chefs, gategroup, and Newrest Group to control fixed costs. For 2025–2033, we expect 9.91% CAGR, with upside from premium leisure travel and corporate travel recovery. Regional consolidation remains likely as global caterers seek hub density in São Paulo, Santiago, Bogotá, and Mexico City.
Segment Deep-Dive: Meals Dominance in Latin America Inflight Services Market
"Segment Analysis Matrix"
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Meals
10.4%
61%
Full-service carrier long-haul and premium cabin demand
Bakery and Confectionary
9.1%
22%
Low-cost carrier snack sales and onboard retail
Beverages
8.7%
17%
Premium beverage upsell and business class service
Meals represent the largest revenue pool within the Latin America inflight services market, generating an estimated USD 744 million in 2025. This dominance stems from full-service carriers such as LATAM Airlines, Avianca, and Aeromexico, which provide complimentary meal service on domestic and international routes. The Full Service Carrier Catering Market accounts for nearly 70% of meal demand, while low-cost carriers rely on pre-purchased snack boxes.
Sub-Segment Dynamics
Economy meals remain volume leaders, with average spend per passenger of USD 4.80 on regional flights.
Business class meals command USD 18–25 per passenger and carry higher margins due to premium ingredients and service labor.
First class is limited to a few long-haul routes, but generates USD 35+ per passenger in catering revenue.
The Business Class Dining Market is expanding at 11.2% CAGR, faster than economy, as airlines retrofit cabins to capture premium leisure demand. The Economy Class Catering Market grows at 9.3% CAGR, supported by passenger traffic recovery and longer average stage lengths.
Margin Pressures
Food inflation for proteins and dairy rose 7–9% in 2024, squeezing gross margins by 150–200 basis points.
Cold-chain logistics in tropical climates raises spoilage costs by 4–6% of total meal cost.
Airline procurement teams demand annual price reductions of 2–4%, forcing caterers to automate kitchen workflows.
Bakery and confectionary is the second-largest segment, with 22% share, driven by low-cost carriers selling croissants, cookies, and local pastries. The Inflight Beverage Services Market holds 17% share but grows slower at 8.7% CAGR due to limited alcohol service on short-haul routes. Overall, Meals will remain the anchor segment, though premium beverage and bakery attach rates present margin upside.
Primary Market Drivers & Growth Restraints in Latin America Inflight Services Market
"Market Dynamics Impact Analysis"
Factor Type
Description
Impact Level
Timeline
Driver
Passenger traffic recovery: Latin America RPKs grew 12.4% in 2024, boosting meal volumes
High
Short term
Driver
Fleet expansion: 380+ new narrow-body deliveries scheduled 2025–2027
High
Medium term
Driver
Premium cabin demand: business class load factors up 5.2 percentage points
Medium
Short term
Restraint
Food inflation: protein and produce costs up 7–9% annually
High
Short term
Restraint
Labor shortages: catering kitchen staff turnover at 22% in Brazil
Medium
Medium term
Restraint
Regulatory complexity: ANVISA, SENASA, and FDA-equivalent audits raise compliance costs
Medium
Long term
Quantitative Catalysts
Passenger traffic: Latin American airlines carried 485 million passengers in 2024, up 9.8% year over year, directly increasing inflight meal demand.
Fleet modernization: Airbus and Boeing backlog for Latin American carriers includes 420 aircraft through 2028, adding galley capacity and requiring new catering contracts.
Outsourcing rates: 78% of full-service carriers in the region outsource catering, up from 71% in 2020, creating vendor opportunity.
Bottlenecks
Cold-chain infrastructure: Only 62% of regional catering kitchens have validated temperature-controlled storage, limiting supplier scalability.
Airport slot constraints: São Paulo GRU and Mexico City MEX operate near capacity, delaying kitchen expansions.
Currency volatility: Brazilian real and Argentine peso swings raise imported ingredient costs by 10–15% in some quarters.
Regulatory bodies such as ANVISA in Brazil and SENASA in Argentina enforce strict food safety standards. Compliance costs add 3–5% to operating expenses but reduce contamination risks. The net effect is a market that rewards scale players with hub-density kitchens and penalizes small regional caterers.
Competitive Ecosystem & Key Vendor Profiles: Latin America Inflight Services Market
"Vendor Benchmarking Matrix"
Company Name
Core Strength
Target Audience
Market Position
LSG Sky Chefs
Hub kitchen density in São Paulo, Fortaleza, Rio de Janeiro
Cost-efficient catering in Andean and Caribbean markets
Low-cost and regional carriers
Challenger
Air Culinaire Worldwide LLC
Premium private jet and first-class catering
Business aviation, first class
Niche
GCG Catering
Local Brazilian cuisine and logistics flexibility
Domestic Brazilian carriers
Niche
Gate Gournet
Bakery and confectionary supply chain
Low-cost carriers
Challenger
Bullet profiles:
LSG Sky Chefs: Retained LATAM's domestic Brazil catering business in 2021 and expanded to São Paulo CGH, Rio GIG, and SDU, catering an average of 140 daily flights.
gategroup: Signed a five-year agreement with LATAM Airlines in July 2021 covering 14 locations plus new domestic stations in Bogotá and Santiago, consolidating its regional leadership.
Newrest Group: Focuses on Andean markets and low-cost carriers, leveraging local sourcing to offer 10–15% lower meal costs than global peers.
Air Culinaire Worldwide LLC: Serves private aviation and first-class cabins with high-touch, low-volume catering, generating USD 45+ per passenger.
GCG Catering: A Brazilian operator with flexibility for last-minute menu changes and regional cuisine, serving domestic routes.
Gate Gournet: Specializes in bakery and confectionary for low-cost carriers, with a growing presence in Mexico and Colombia.
These vendors compete on food safety certifications, cold-chain reliability, and price. LSG Sky Chefs and gategroup control an estimated 55% of the Latin America inflight services market revenue. The Inflight Catering Services Market remains concentrated, but Newrest and local players are gaining share through cost leadership.
Strategic Milestones & Recent Developments in Latin America Inflight Services Market
"Latest Strategic Moves"
Date
Company
Event Type
Impact
Feb 2021
LSG Sky Chefs / LATAM Airlines
Partnership expansion
Added São Paulo CGH, Rio GIG, and SDU; 140 daily flights catered
Jul 2021
gategroup / LATAM Airlines
Five-year agreement
Covered 14 locations plus Bogotá and Santiago
2023
Newrest Group
Contract win
Secured low-cost carrier catering in Colombia and Peru
2024
Air Culinaire Worldwide LLC
Service launch
Expanded private jet catering in Mexico City and São Paulo
Chronological details:
February 2021: LATAM Airlines awarded its domestic Brazil catering business to LSG Sky Chefs. The deal retained São Paulo GRU and Fortaleza FOR for three years and expanded to São Paulo CGH and Rio de Janeiro GIG and SDU, representing 140 daily flights in 2021.
July 2021: gategroup signed a five-year agreement with LATAM Airlines covering 14 airports where it had served the carrier for over 20 years. The deal added Bogotá, Colombia and Santiago, Chile as new strategic domestic locations, strengthening gategroup's Latin America leadership.
2023: Newrest Group won contracts with two low-cost carriers in Colombia and Peru, targeting buy-on-board snack and beverage service.
2024: Air Culinaire Worldwide LLC launched private jet catering in Mexico City and São Paulo, aiming at business aviation and first-class passengers.
These moves show that airline catering contracts are long-term and hub-centric. Incumbents with kitchen real estate at GRU, BOG, SCL, and MEX hold structural advantages. The Full Service Carrier Catering Market remains the primary battleground, but low-cost carrier growth creates new volume for bakery and beverage suppliers.
Regional Market Analysis & Growth Corridors for Latin America Inflight Services Market
"Regional Growth Comparison"
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
South America
10.8%
USD 0.46 Billion
Brazil and Argentina traffic recovery; LATAM contracts
High (ANVISA, SENASA)
North America
8.2%
USD 0.27 Billion
Mexico nearshoring; US-Mexico route expansion
High (FDA, USDA)
Europe
7.5%
USD 0.22 Billion
EU-Latin America long-haul premium demand
Very High (EFSA, EASA)
Asia-Pacific
6.9%
USD 0.18 Billion
China-Latin America trade and passenger flows
High (CAAC, FSSAI)
Middle East & Africa
6.1%
USD 0.09 Billion
Turkish and Gulf carrier connections
Medium (GCC, local authorities)
Fastest-Growing vs. Most Mature
South America is the fastest-growing region at 10.8% CAGR, driven by Brazil's 210 million domestic passengers and Argentina's deregulation of airline routes.
North America is mature but benefits from Mexico's nearshoring boom, with Mexico City MEX and Cancún CUN adding catering capacity.
Europe remains a premium long-haul source market, but European caterers face high labor costs and strict EFSA rules.
Asia-Pacific has slower growth due to distance and limited direct routes, though China's trade with Brazil creates cargo and passenger opportunities.
Brazil alone represents 42% of South America inflight services revenue, followed by Argentina at 16% and Chile at 12%. The Low-Cost Carrier Inflight Services Market is expanding fastest in Colombia and Peru, where Viva and SKY Airline add routes. The Aircraft Galley Equipment Market in Latin America is also growing as airlines retrofit older A320 and 737 cabins with lighter carts and improved chillers.
Technology Innovation & R&D Trajectory in Latin America Inflight Services Market
Three disruptive technologies are reshaping airline catering in the region:
IoT cold-chain sensors: Real-time temperature monitoring reduces spoilage by 12–18% and provides audit trails for ANVISA and SENASA. LSG Sky Chefs piloted sensors in São Paulo, achieving 99.2% compliance.
AI menu demand forecasting: Machine learning predicts passenger meal preferences by route and season, cutting food waste by up to 20%. gategroup has tested AI in Santiago and Bogotá.
Sustainable packaging and lightweight galley equipment: Biodegradable containers and composite carts reduce weight, lowering fuel burn by 1–2% per flight. The Aircraft Galley Equipment Market is seeing R&D from Safran and Zodiac.
Adoption timelines vary. IoT sensors are already in 35% of large catering kitchens, while AI forecasting will reach 50% penetration by 2027. R&D investment among top caterers is 2–3% of revenue, focused on shelf-stable meals and local ingredient sourcing. Emerging tech reinforces incumbent moats because scale players can afford digital infrastructure. Smaller caterers risk exclusion from airline tenders that require traceability.
Pricing Dynamics, Cost Structures & Margin Pressure in Latin America Inflight Services Market
Average selling prices (ASP) for inflight meals rose 6.8% in 2024, driven by protein and dairy inflation. Cost breakdown for a typical economy meal:
Cost Component
Share of Total Cost
Raw materials
42%
Labor
32%
Logistics and cold chain
14%
Energy and overhead
8%
Packaging
4%
Margins are thin. Gross margins range from 12–18% for economy meals and 22–28% for business class dining. Airlines hold pricing power because contracts are re-tendered every 3–5 years. Caterers respond by indexing 20–25% of raw material costs to commodity indices and by consolidating kitchens.
The Airline Food Safety Compliance Market adds 3–5% to operating costs but avoids recalls that can exceed USD 10 million. Inflation remains the top margin threat, followed by labor strikes in Argentina and Chile. Premium cabin and private jet catering offer the best margin insulation, with Air Culinaire Worldwide LLC charging USD 45+ per passenger.
Latin America Inflight Services Market Segmentation
1. Food Type
1.1. Meals
1.2. Bakery and Confectionary
1.3. Beverages
1.4. Other Food Types
2. Flight Service Type
2.1. Full Service Carriers
2.2. Low-Cost Carriers
2.3. Hybrid and Other Service Types
3. Aircraft Seating Class
3.1. Economy Class
3.2. Business Class
3.3. First Class
Latin America Inflight Services Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Latin America Inflight Services Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.91% from 2020-2034
Segmentation
By Food Type
Meals
Bakery and Confectionary
Beverages
Other Food Types
By Flight Service Type
Full Service Carriers
Low-Cost Carriers
Hybrid and Other Service Types
By Aircraft Seating Class
Economy Class
Business Class
First Class
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Food Type
5.1.1. Meals
5.1.2. Bakery and Confectionary
5.1.3. Beverages
5.1.4. Other Food Types
5.2. Market Analysis, Insights and Forecast - by Flight Service Type
5.2.1. Full Service Carriers
5.2.2. Low-Cost Carriers
5.2.3. Hybrid and Other Service Types
5.3. Market Analysis, Insights and Forecast - by Aircraft Seating Class
5.3.1. Economy Class
5.3.2. Business Class
5.3.3. First Class
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Food Type
6.1.1. Meals
6.1.2. Bakery and Confectionary
6.1.3. Beverages
6.1.4. Other Food Types
6.2. Market Analysis, Insights and Forecast - by Flight Service Type
6.2.1. Full Service Carriers
6.2.2. Low-Cost Carriers
6.2.3. Hybrid and Other Service Types
6.3. Market Analysis, Insights and Forecast - by Aircraft Seating Class
6.3.1. Economy Class
6.3.2. Business Class
6.3.3. First Class
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Food Type
7.1.1. Meals
7.1.2. Bakery and Confectionary
7.1.3. Beverages
7.1.4. Other Food Types
7.2. Market Analysis, Insights and Forecast - by Flight Service Type
7.2.1. Full Service Carriers
7.2.2. Low-Cost Carriers
7.2.3. Hybrid and Other Service Types
7.3. Market Analysis, Insights and Forecast - by Aircraft Seating Class
7.3.1. Economy Class
7.3.2. Business Class
7.3.3. First Class
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Food Type
8.1.1. Meals
8.1.2. Bakery and Confectionary
8.1.3. Beverages
8.1.4. Other Food Types
8.2. Market Analysis, Insights and Forecast - by Flight Service Type
8.2.1. Full Service Carriers
8.2.2. Low-Cost Carriers
8.2.3. Hybrid and Other Service Types
8.3. Market Analysis, Insights and Forecast - by Aircraft Seating Class
8.3.1. Economy Class
8.3.2. Business Class
8.3.3. First Class
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Food Type
9.1.1. Meals
9.1.2. Bakery and Confectionary
9.1.3. Beverages
9.1.4. Other Food Types
9.2. Market Analysis, Insights and Forecast - by Flight Service Type
9.2.1. Full Service Carriers
9.2.2. Low-Cost Carriers
9.2.3. Hybrid and Other Service Types
9.3. Market Analysis, Insights and Forecast - by Aircraft Seating Class
9.3.1. Economy Class
9.3.2. Business Class
9.3.3. First Class
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Food Type
10.1.1. Meals
10.1.2. Bakery and Confectionary
10.1.3. Beverages
10.1.4. Other Food Types
10.2. Market Analysis, Insights and Forecast - by Flight Service Type
10.2.1. Full Service Carriers
10.2.2. Low-Cost Carriers
10.2.3. Hybrid and Other Service Types
10.3. Market Analysis, Insights and Forecast - by Aircraft Seating Class
10.3.1. Economy Class
10.3.2. Business Class
10.3.3. First Class
11. Competitive Analysis
11.1. Company Profiles
11.1.1. GCG Catering
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Gate Gournet
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. LSG Sky Chefs
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Air Culinaire Worldwide LLC
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Newrest Group
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Marcia's Catering
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Manny Caterin
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
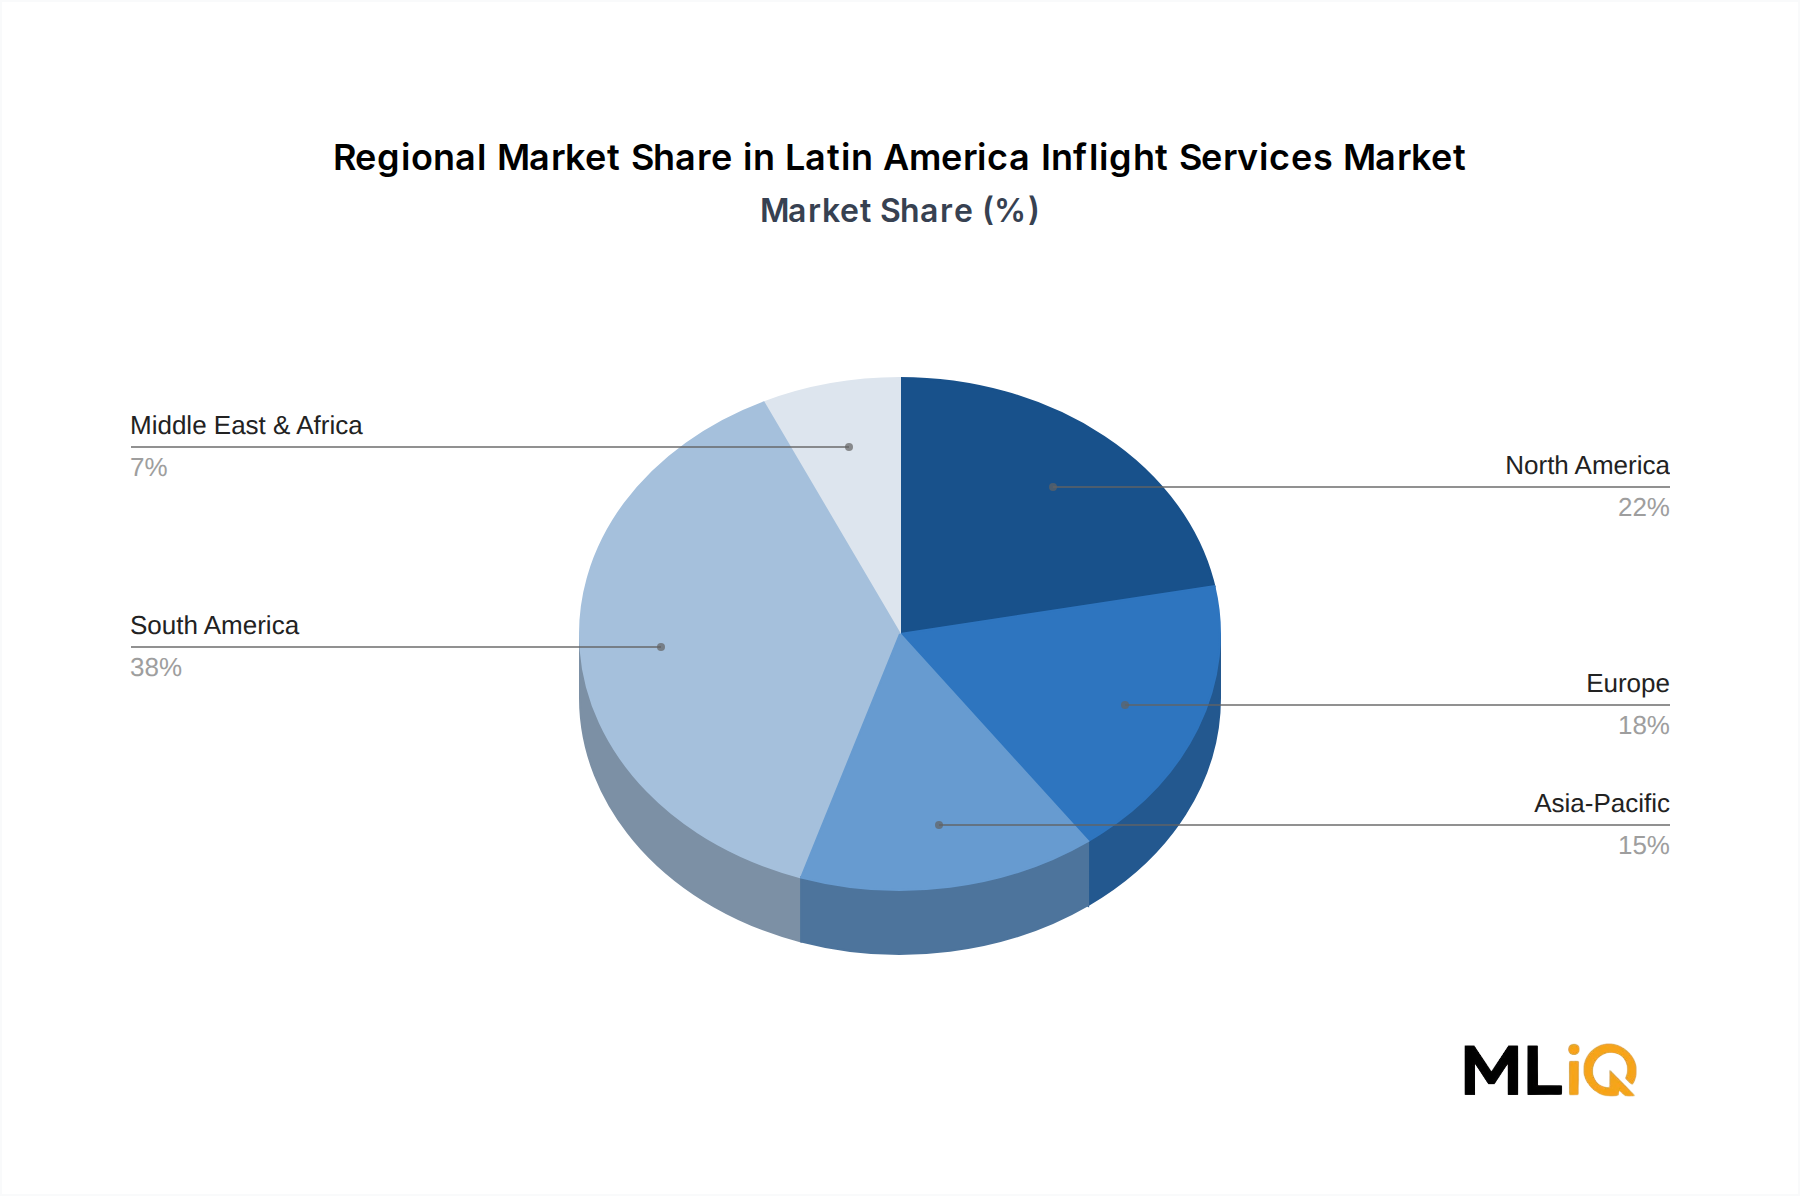
Figure 1: Latin America Inflight Services Market Revenue Breakdown (billionusdbillion, %) by Region 2026 & 2034
Figure 2: North America Latin America Inflight Services Market Revenue (billionusdbillion), by Food Type 2026 & 2034
Figure 3: North America Latin America Inflight Services Market Revenue Share (%), by Food Type 2026 & 2034
Figure 4: North America Latin America Inflight Services Market Revenue (billionusdbillion), by Flight Service Type 2026 & 2034
Figure 5: North America Latin America Inflight Services Market Revenue Share (%), by Flight Service Type 2026 & 2034
Figure 6: North America Latin America Inflight Services Market Revenue (billionusdbillion), by Aircraft Seating Class 2026 & 2034
Figure 7: North America Latin America Inflight Services Market Revenue Share (%), by Aircraft Seating Class 2026 & 2034
Figure 8: North America Latin America Inflight Services Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 9: North America Latin America Inflight Services Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Latin America Inflight Services Market Revenue (billionusdbillion), by Food Type 2026 & 2034
Figure 11: South America Latin America Inflight Services Market Revenue Share (%), by Food Type 2026 & 2034
Figure 12: South America Latin America Inflight Services Market Revenue (billionusdbillion), by Flight Service Type 2026 & 2034
Figure 13: South America Latin America Inflight Services Market Revenue Share (%), by Flight Service Type 2026 & 2034
Figure 14: South America Latin America Inflight Services Market Revenue (billionusdbillion), by Aircraft Seating Class 2026 & 2034
Figure 15: South America Latin America Inflight Services Market Revenue Share (%), by Aircraft Seating Class 2026 & 2034
Figure 16: South America Latin America Inflight Services Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 17: South America Latin America Inflight Services Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Latin America Inflight Services Market Revenue (billionusdbillion), by Food Type 2026 & 2034
Figure 19: Europe Latin America Inflight Services Market Revenue Share (%), by Food Type 2026 & 2034
Figure 20: Europe Latin America Inflight Services Market Revenue (billionusdbillion), by Flight Service Type 2026 & 2034
Figure 21: Europe Latin America Inflight Services Market Revenue Share (%), by Flight Service Type 2026 & 2034
Figure 22: Europe Latin America Inflight Services Market Revenue (billionusdbillion), by Aircraft Seating Class 2026 & 2034
Figure 23: Europe Latin America Inflight Services Market Revenue Share (%), by Aircraft Seating Class 2026 & 2034
Figure 24: Europe Latin America Inflight Services Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 25: Europe Latin America Inflight Services Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Latin America Inflight Services Market Revenue (billionusdbillion), by Food Type 2026 & 2034
Figure 27: Middle East & Africa Latin America Inflight Services Market Revenue Share (%), by Food Type 2026 & 2034
Figure 28: Middle East & Africa Latin America Inflight Services Market Revenue (billionusdbillion), by Flight Service Type 2026 & 2034
Figure 29: Middle East & Africa Latin America Inflight Services Market Revenue Share (%), by Flight Service Type 2026 & 2034
Figure 30: Middle East & Africa Latin America Inflight Services Market Revenue (billionusdbillion), by Aircraft Seating Class 2026 & 2034
Figure 31: Middle East & Africa Latin America Inflight Services Market Revenue Share (%), by Aircraft Seating Class 2026 & 2034
Figure 32: Middle East & Africa Latin America Inflight Services Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 33: Middle East & Africa Latin America Inflight Services Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Latin America Inflight Services Market Revenue (billionusdbillion), by Food Type 2026 & 2034
Figure 35: Asia Pacific Latin America Inflight Services Market Revenue Share (%), by Food Type 2026 & 2034
Figure 36: Asia Pacific Latin America Inflight Services Market Revenue (billionusdbillion), by Flight Service Type 2026 & 2034
Figure 37: Asia Pacific Latin America Inflight Services Market Revenue Share (%), by Flight Service Type 2026 & 2034
Figure 38: Asia Pacific Latin America Inflight Services Market Revenue (billionusdbillion), by Aircraft Seating Class 2026 & 2034
Figure 39: Asia Pacific Latin America Inflight Services Market Revenue Share (%), by Aircraft Seating Class 2026 & 2034
Figure 40: Asia Pacific Latin America Inflight Services Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 41: Asia Pacific Latin America Inflight Services Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Food Type 2020 & 2034
Table 2: Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Flight Service Type 2020 & 2034
Table 3: Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Aircraft Seating Class 2020 & 2034
Table 4: Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Region 2020 & 2034
Table 5: North America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Food Type 2020 & 2034
Table 6: North America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Flight Service Type 2020 & 2034
Table 7: North America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Aircraft Seating Class 2020 & 2034
Table 8: North America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 9: United States Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 10: Canada Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 11: Mexico Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 12: South America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Food Type 2020 & 2034
Table 13: South America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Flight Service Type 2020 & 2034
Table 14: South America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Aircraft Seating Class 2020 & 2034
Table 15: South America Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 16: Brazil Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 17: Argentina Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 19: Europe Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Food Type 2020 & 2034
Table 20: Europe Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Flight Service Type 2020 & 2034
Table 21: Europe Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Aircraft Seating Class 2020 & 2034
Table 22: Europe Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 23: United Kingdom Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 24: Germany Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 25: France Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 26: Italy Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 27: Spain Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 28: Russia Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 29: Benelux Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 30: Nordics Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Food Type 2020 & 2034
Table 33: Middle East & Africa Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Flight Service Type 2020 & 2034
Table 34: Middle East & Africa Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Aircraft Seating Class 2020 & 2034
Table 35: Middle East & Africa Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 36: Turkey Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 37: Israel Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 38: GCC Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 39: North Africa Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 40: South Africa Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Food Type 2020 & 2034
Table 43: Asia Pacific Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Flight Service Type 2020 & 2034
Table 44: Asia Pacific Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Aircraft Seating Class 2020 & 2034
Table 45: Asia Pacific Latin America Inflight Services Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 46: China Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 47: India Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 48: Japan Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 49: South Korea Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 50: ASEAN Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 51: Oceania Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Latin America Inflight Services Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We allocate 70–80% of total research effort to primary research, conducting structured interviews and surveys with decision-makers across the Latin America inflight services value chain.
Primary participants include airline catering facility operators, inflight food and beverage manufacturers, aircraft galley equipment suppliers, cold-chain logistics providers for airline catering, and airline menu design and procurement consultancies.
We interview stakeholders such as Director of Inflight Catering Procurement, Airline Food Safety and Quality Assurance Manager, Inflight Services Operations Director, and Catering Logistics and Cold Chain Supervisor.
We also engage Airline Menu Development Chef roles to capture menu innovation and cost dynamics.
Interviews are conducted quarterly and refreshed at the date of purchase to reflect current contract awards and pricing.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Inflight Catering Procurement
30%
Airline Food Safety and Quality Assurance Manager
25%
Inflight Services Operations Director
20%
Catering Logistics and Cold Chain Supervisor
15%
Airline Menu Development Chef
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Airline catering facility operators
35%
Inflight food and beverage manufacturers
25%
Aircraft galley equipment suppliers
20%
Cold-chain logistics providers
15%
Airline procurement consultancies
5%
Secondary Research & Industry Benchmarking
We triangulate primary inputs with 20–30% secondary research from trade publications, airline annual reports, and regulatory filings.
We deploy top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up variables include number of daily departures per airline station, average meal cost per passenger, passenger load factor by seating class, and number of catering kitchens per hub airport.
We also use average cold chain temperature excursions per 1,000 meals to adjust spoilage and cost assumptions.
Segment splits are built by Food Type (Meals, Bakery and Confectionary, Beverages, Other Food Types), Flight Service Type (Full Service Carriers, Low-Cost Carriers, Hybrid and Other Service Types), and Aircraft Seating Class (Economy Class, Business Class, First Class).
Geographic coverage includes North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific).
Forecast period is 2026–2034, with historical baselines anchored to 2025.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-level data triangulation and expert validation.
Every report is updated to the date of purchase, ensuring current contract awards, pricing, and regulatory changes are reflected.
Cross-validation includes comparing primary interview responses against financial filings, government trade data, and association reports.
Outlier detection and sanity checks are applied to all quantitative metrics before final publication.
Where data gaps exist, we use proxy variables and clearly document assumptions in the model.
Frequently Asked Questions
1. How high are barriers to entry and what competitive moats exist in the Latin America Inflight Services Market?
Barriers are high due to cold-chain infrastructure, HACCP and ANVISA compliance, and multi-year airline contracts. Incumbents such as LSG Sky Chefs and gategroup control hub kitchens at São Paulo GRU and Bogotá, creating scale moats. A new entrant needs at least 12–18 months to obtain airline approvals and USDA/FDA-equivalent certifications.
2. What pricing trends and cost structure dynamics are shaping the Latin America Inflight Services Market?
Average meal costs rose 6–8% annually in 2023–2024 due to food inflation and labor increases. Labor represents 30–35% of catering costs, while raw materials are 40–45%. Airlines push for fixed-price contracts, but suppliers index 20–25% of costs to commodity baskets.
3. What is the current market size, valuation, and CAGR projection through 2033 for the Latin America Inflight Services Market?
The market is valued at USD 1.22 billion in 2025 and is forecast to reach USD 2.60 billion by 2033, growing at a 9.91% CAGR. South America accounts for the largest share, driven by Brazil and Argentina. Full-service carrier catering represents over 60% of revenue.
4. How are consumer behavior shifts and purchasing trends changing the Latin America Inflight Services Market?
Passengers increasingly pre-order meals and prefer healthier, plant-based, and local Latin American options. Buy-on-board spending rose 14% in 2024 for low-cost carriers such as Volaris and JetSMART. Business class travelers expect restaurant-quality dining, pushing premium beverage and bakery attachment rates above 35%.
5. What investment activity, funding rounds, and venture capital interest exists in the Latin America Inflight Services Market?
Venture capital interest is modest, with most funding directed to airline tech and food-tech adjacent startups. In 2024, cold-chain IoT startup LogiNext raised USD 15 million for Latin America expansion. Strategic M&A remains dominant, exemplified by gategroup's five-year LATAM agreement covering 14 locations.
6. Which technological innovations and R&D trends are shaping the Latin America Inflight Services Market?
Key innovations include IoT temperature sensors, AI-based menu demand forecasting, and lightweight galley carts. LSG Sky Chefs piloted AI forecasting in São Paulo, reducing food waste by 18%. R&D spending among top caterers is 2–3% of revenue, focused on sustainable packaging and shelf-stable meals.