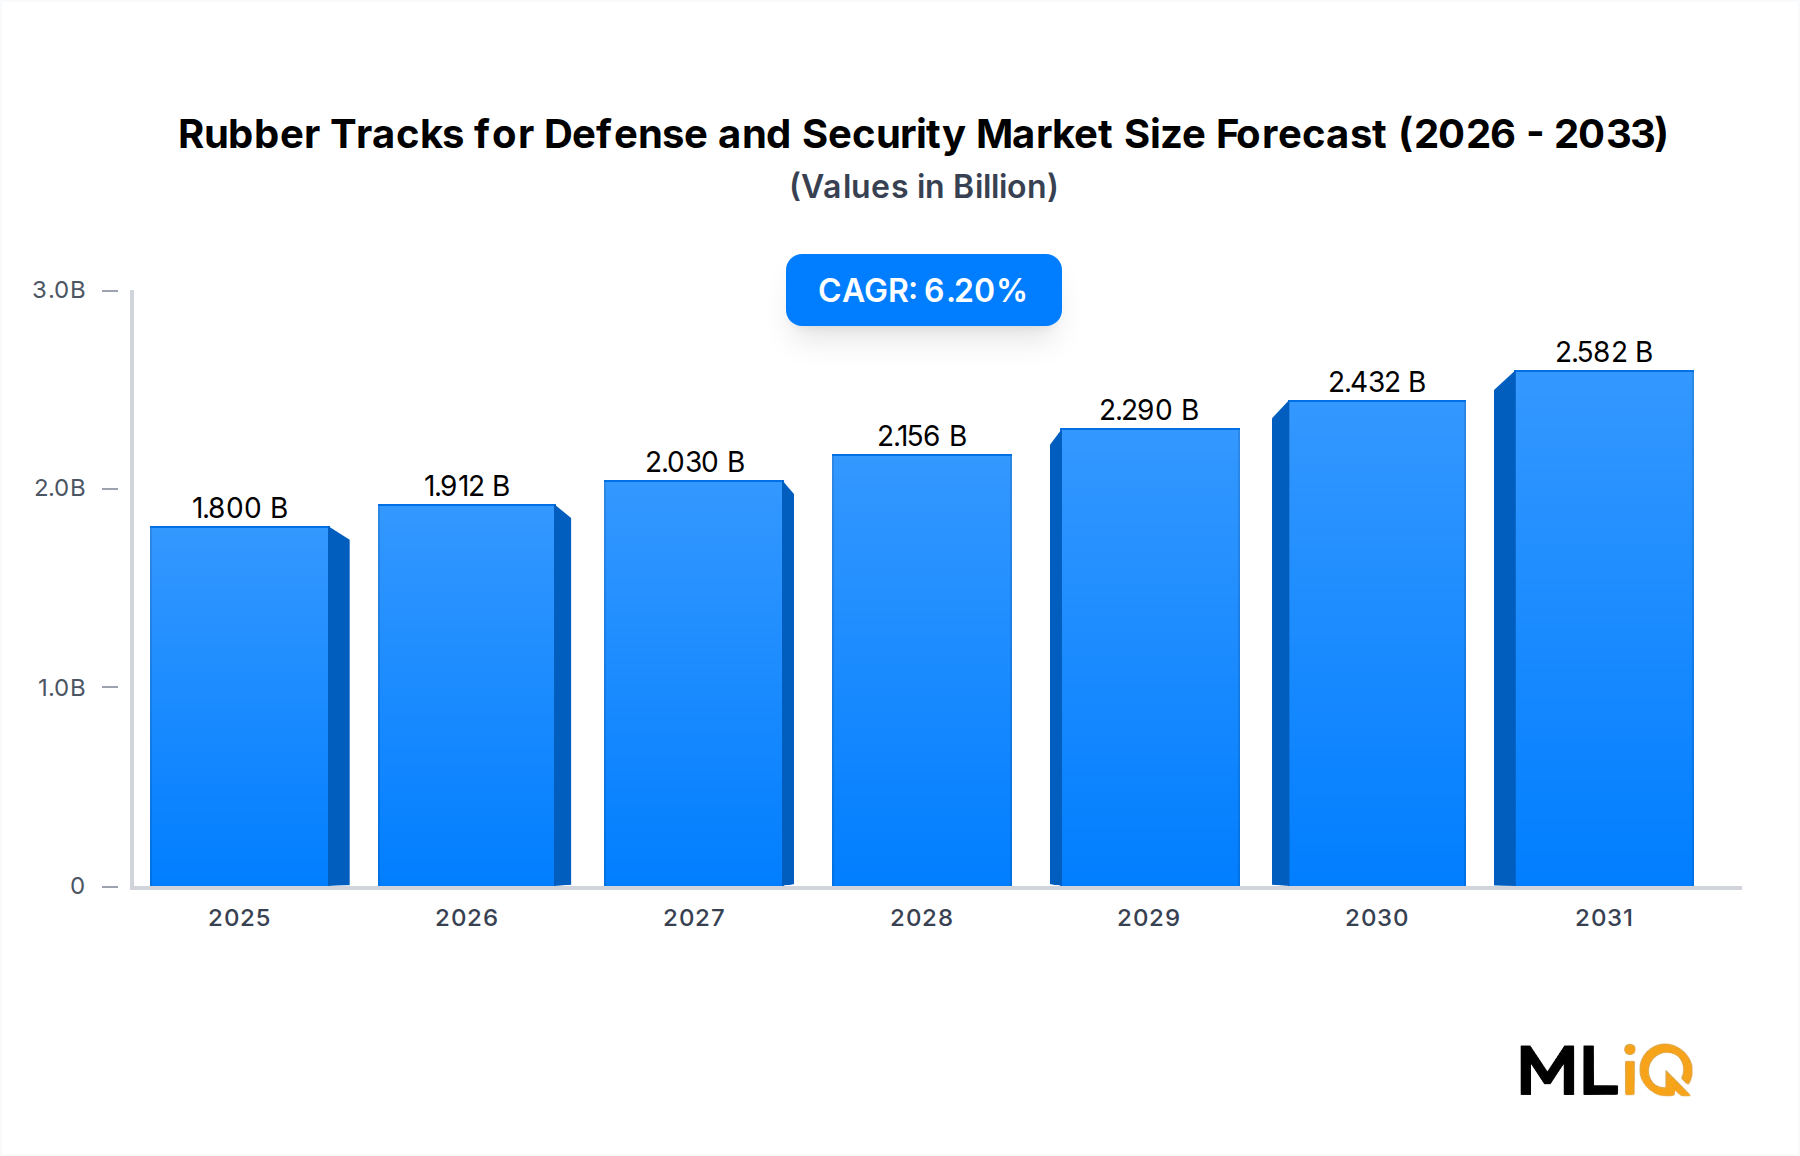
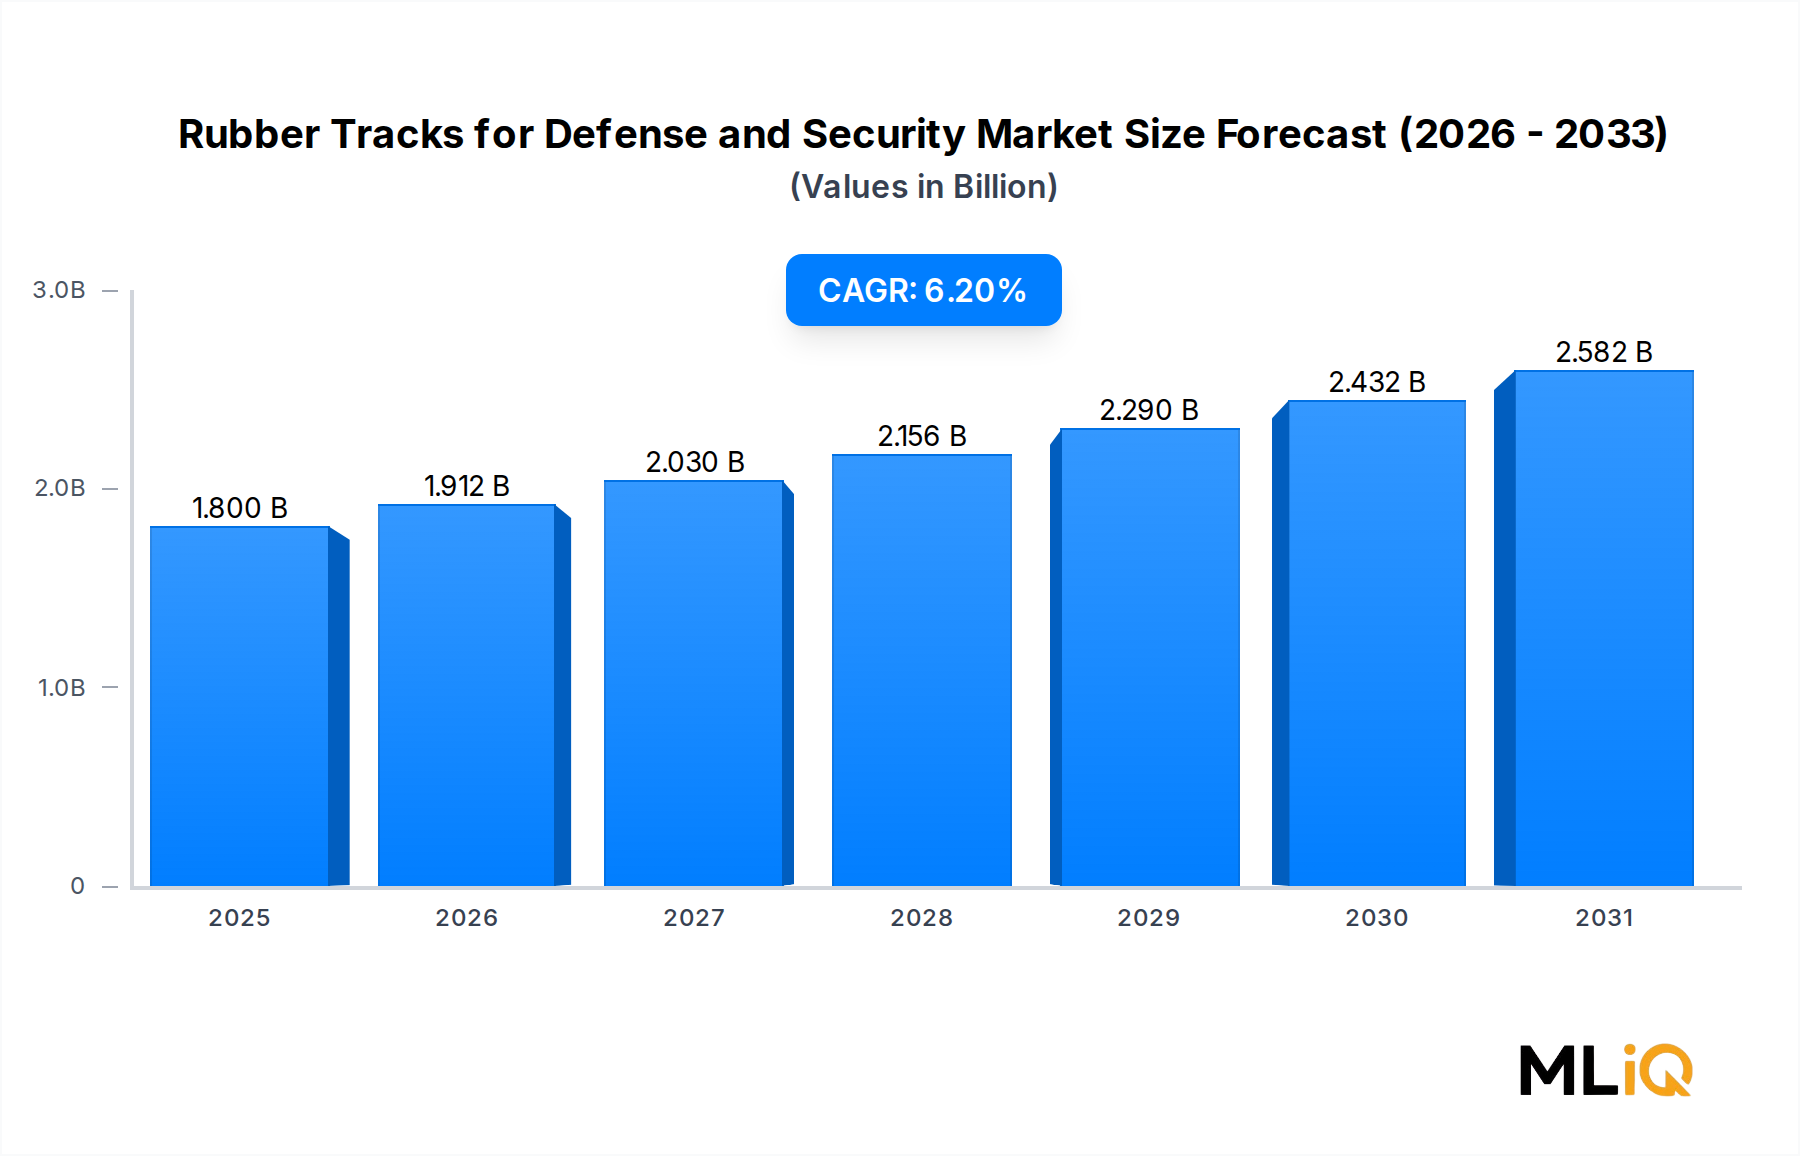
The global Rubber Tracks for Defense and Security Market is valued at $1.8 billion in 2025 and is projected to expand at a compound annual growth rate of 6.2% through 2033, reflecting sustained investment in ground mobility solutions across military and paramilitary organizations worldwide. This growth trajectory is underpinned by a confluence of geopolitical realignments, modernization budgets, and material science advancements that collectively elevate rubber tracks from a commodity consumable to a mission-critical component.
Rubber tracks offer decisive operational advantages over conventional steel track systems, including reduced acoustic signature, lower ground pressure, superior surface compatibility on paved and mixed terrain, and significantly decreased vibration transfer to vehicle crews. These attributes are increasingly prioritized in contemporary force doctrine, where rapid deployment in urban environments and peacekeeping operations is as operationally relevant as conventional battlefield maneuverability.
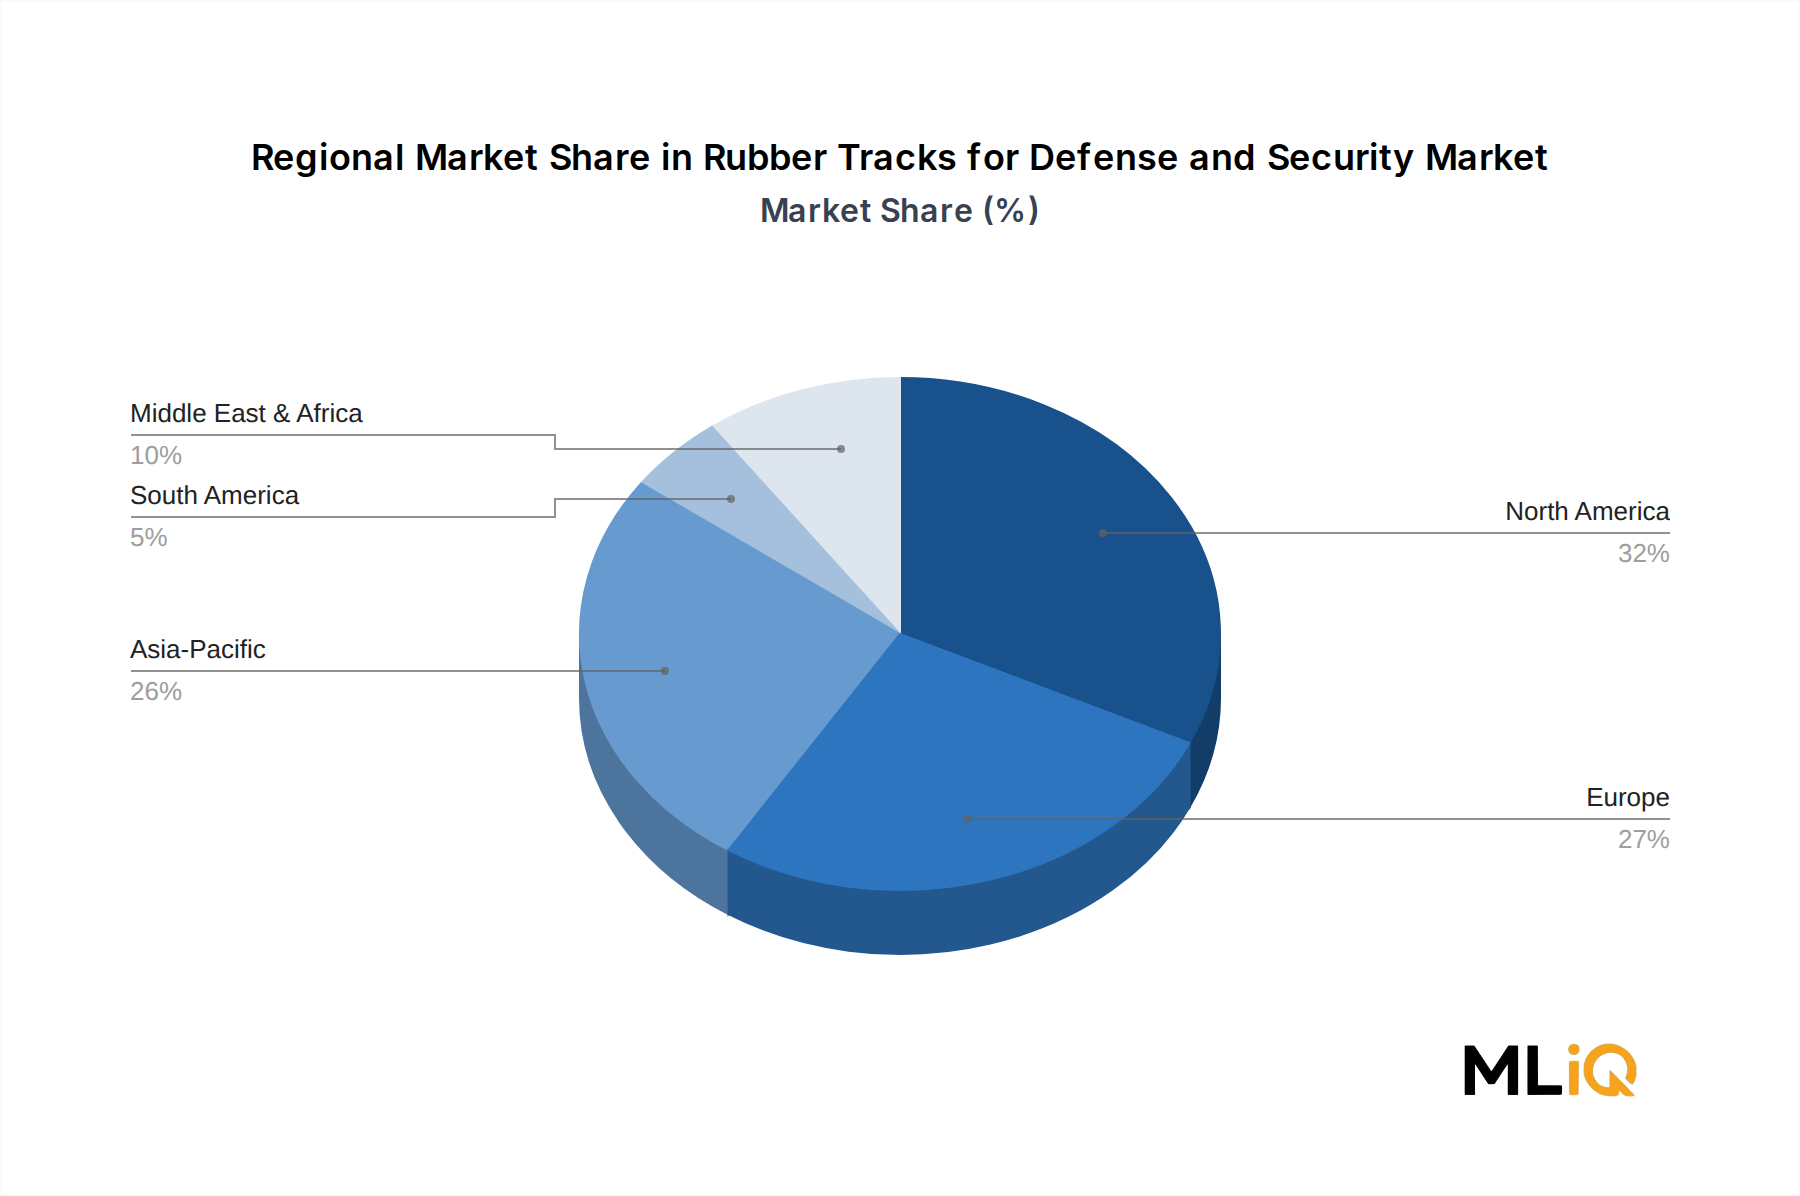
North America currently holds the largest revenue share, driven by the United States Department of Defense's expansive vehicle modernization programs and allied procurement pipelines. Europe represents the second-largest regional contributor, with NATO member states accelerating defense outlays following the Russia-Ukraine conflict. The Asia Pacific region is the fastest-growing market, led by China, India, South Korea, and ASEAN defense buildups.
Key demand drivers include rising global defense budgets, which crossed $2.2 trillion collectively in 2024 according to SIPRI estimates, growing adoption of lighter expeditionary vehicle platforms, and increasing procurement of armored personnel carriers and infantry fighting vehicles optimized for rubber track systems. Furthermore, the shift from legacy steel-track configurations in reconnaissance and support vehicle segments is creating incremental volume opportunities for rubber track manufacturers.
On the supply side, raw material dynamics—particularly the trajectory of the Synthetic Rubber Market and the Carbon Black Market—exert meaningful cost pressure on manufacturers, shaping margin profiles and procurement negotiations. Leading suppliers are investing in proprietary rubber compounding technologies and reinforced-fiber architectures to differentiate product performance and extend track service life beyond the current benchmark of 600–1,200 operational hours.
The competitive landscape is moderately consolidated, with Soucy International and William Cook Holding maintaining leadership positions through integrated design-to-delivery capabilities. Emerging players from Asia and the Middle East are progressively challenging established Western incumbents on price and regional supply chain proximity.
Looking ahead to 2033, the market is expected to reach approximately $2.9 billion, supported by next-generation platform programs, dual-use security vehicle procurement, and aftermarket replacement demand from aging fleets deployed globally.