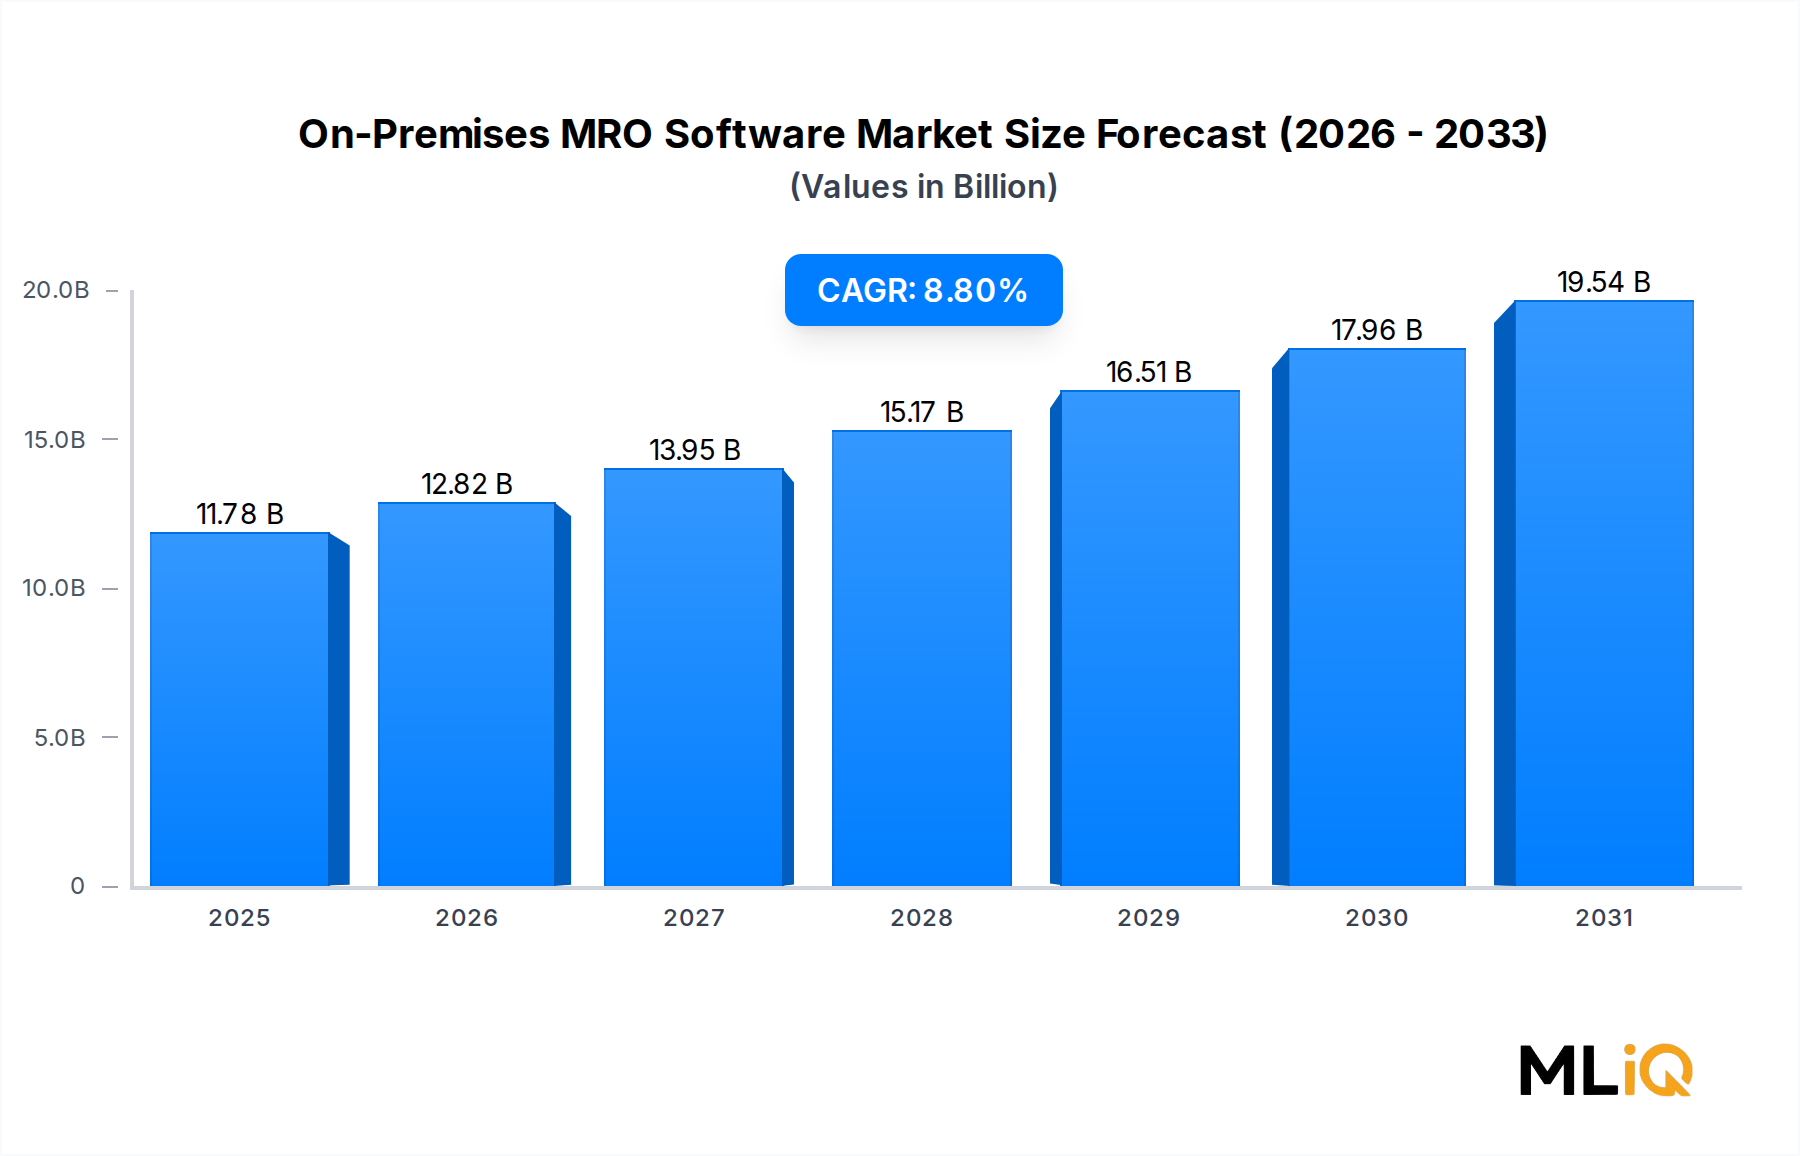
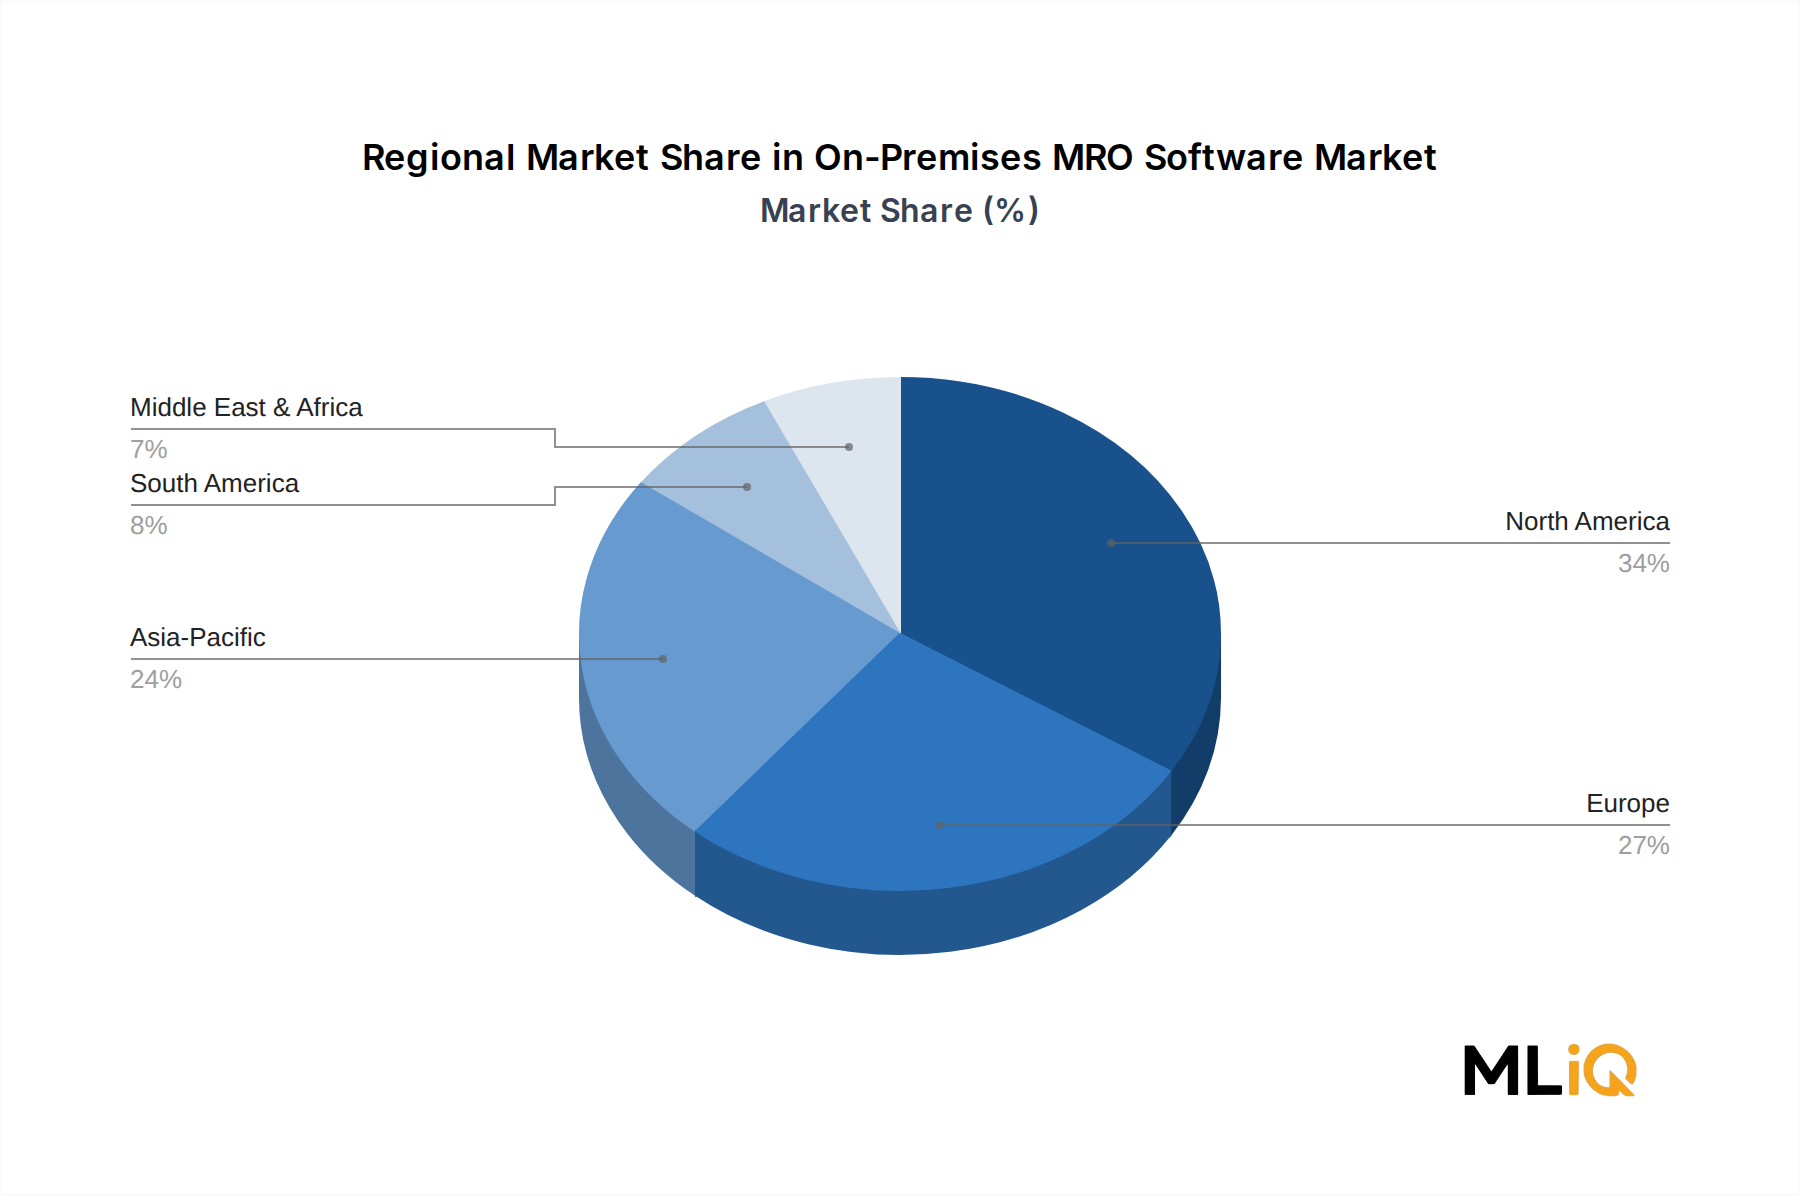
Several well-quantified forces are simultaneously propelling and constraining the On-Premises MRO Software Market, and a data-grounded analysis of each is essential for accurate market positioning.
On the demand side, the most significant driver is the ongoing recovery and expansion of global commercial air traffic. The International Air Transport Association (IATA) projects that global passenger numbers will exceed 4.7 billion by 2026, surpassing pre-pandemic peaks. This growth directly translates into expanded fleet utilization rates, which accelerates the frequency and complexity of scheduled and unscheduled maintenance events — all of which require robust software tracking. Airlines expanding their fleets are prioritizing on-premises MRO software that can be integrated with existing ERP deployments, citing data security and system reliability as the primary justification.
Defense budget escalation is a second major driver. NATO member states committed to defense spending targets of 2% of GDP by 2024, with several European nations — including Poland, Germany, and the United Kingdom — already exceeding or approaching this threshold. Elevated procurement cycles for new military aircraft platforms, combined with extended service life programs for legacy fleets, are generating demand for sophisticated on-premises maintenance management software capable of handling multi-aircraft-type configurations within classified network environments.
Regulatory compliance pressure constitutes a third driver. EASA's evolving Part-M and Part-145 frameworks impose increasingly granular documentation requirements on maintenance organizations. Organizations found non-compliant face operational certificate suspension, making the investment in certified, auditable MRO software not merely beneficial but operationally mandatory. The Aircraft Maintenance Management Software Market is expanding in direct correlation with these regulatory tightening cycles.
On the constraint side, the principal limiting factor is the high total cost of initial deployment. On-premises implementations require significant upfront capital expenditure in hardware infrastructure, IT staffing, and integration services. For mid-size MRO operators, this cost barrier can delay procurement decisions or divert purchasing toward subscription-based alternatives. Additionally, vendor consolidation is reducing the number of competing platforms, which constrains pricing competition and increases switching costs — particularly for operators deeply embedded in incumbent platforms.