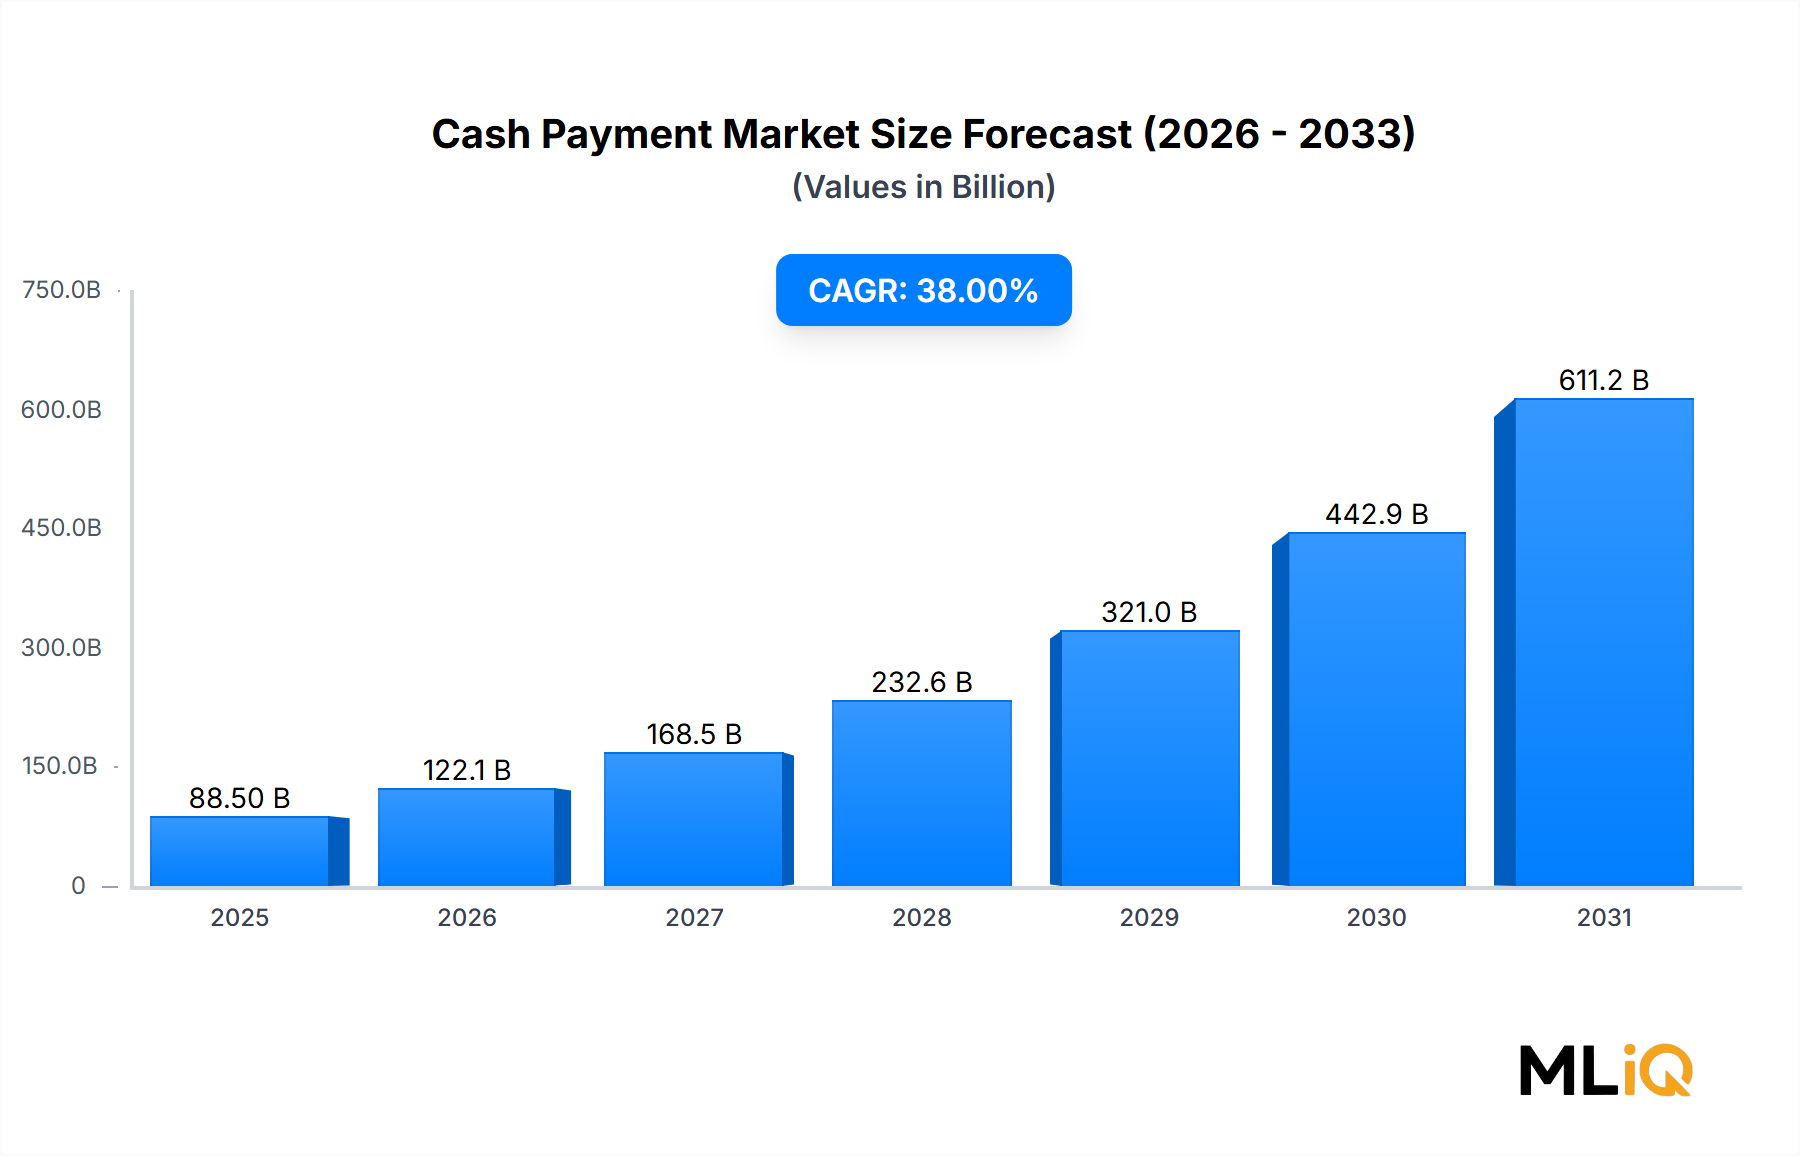
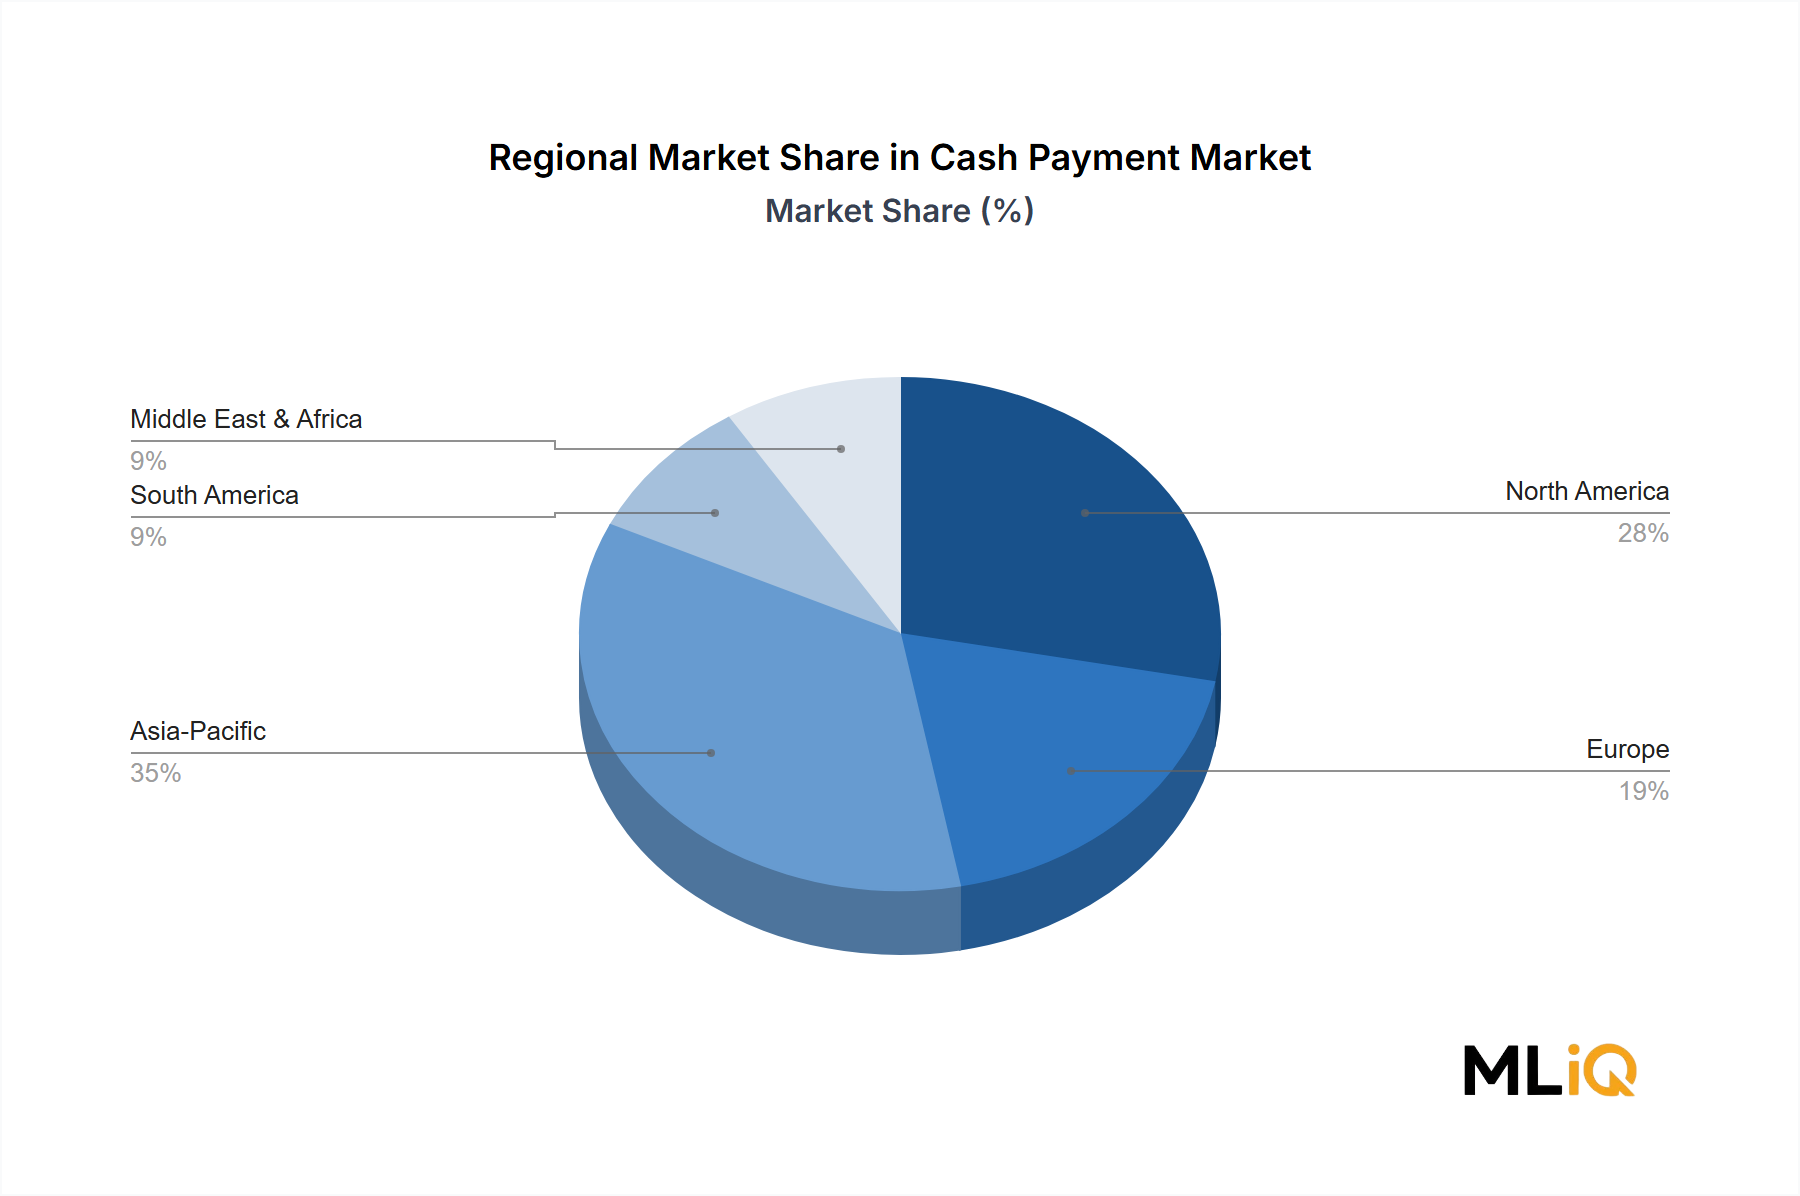
The Cash Payment Market's extraordinary 38% CAGR is underpinned by a specific constellation of quantifiable drivers and counterbalanced by identifiable structural constraints that will shape its trajectory through 2033.
Driver 1: Financial Inclusion Mandates — Approximately 1.4 billion adults globally remain unbanked as of recent estimates, according to World Bank data. In economies across Sub-Saharan Africa, South Asia, and Southeast Asia, governments and development agencies are investing in cash infrastructure as the primary vehicle for financial inclusion, given that digital payment adoption requires smartphone penetration and reliable internet connectivity that remains unavailable to significant rural populations.
Driver 2: Retail Sector Expansion in Emerging Markets — Retail GDP contribution in Asia Pacific economies grew at rates exceeding 7% annually in recent years, driving commensurately higher absolute volumes of cash transactions even as digital payment shares increase. The expansion of the Mobile Payment Market has paradoxically stimulated cash demand through agent banking models, where consumers convert cash to digital value and back at retail touchpoints.
Driver 3: Cash Resilience in High-Value Transaction Categories — Hospitality and travel sectors demonstrate persistent cash payment utilization for gratuities, incidental charges, and informal service payments. Hotel Bill Payments and Travel Bookings segments within the market represent high-growth application areas where hybrid cash-digital reconciliation platforms are being adopted at scale.
Driver 4: Technology Investment in Cash Automation — The Contactless Payment Market's growth has catalyzed parallel investment in cash automation as financial institutions seek to rebalance their payment infrastructure portfolios. Intelligent cash recyclers, AI-powered counterfeit detection, and real-time cash flow analytics represent a capital expenditure category growing at double-digit rates annually.
Constraint 1: Regulatory Pressure Toward Digital Payments — In the European Union and select North American jurisdictions, regulatory frameworks increasingly incentivize or mandate digital payment acceptance, creating structural headwinds for cash-centric business models.
Constraint 2: Cost of Cash Infrastructure — The operational cost of maintaining cash handling infrastructure — including ATM networks, vault management, armored transport, and counterfeit monitoring — imposes a significant cost burden estimated at 1.5–2% of total transaction value, compared to sub-1% for leading digital rails, creating economic pressure on cash-dependent business models.