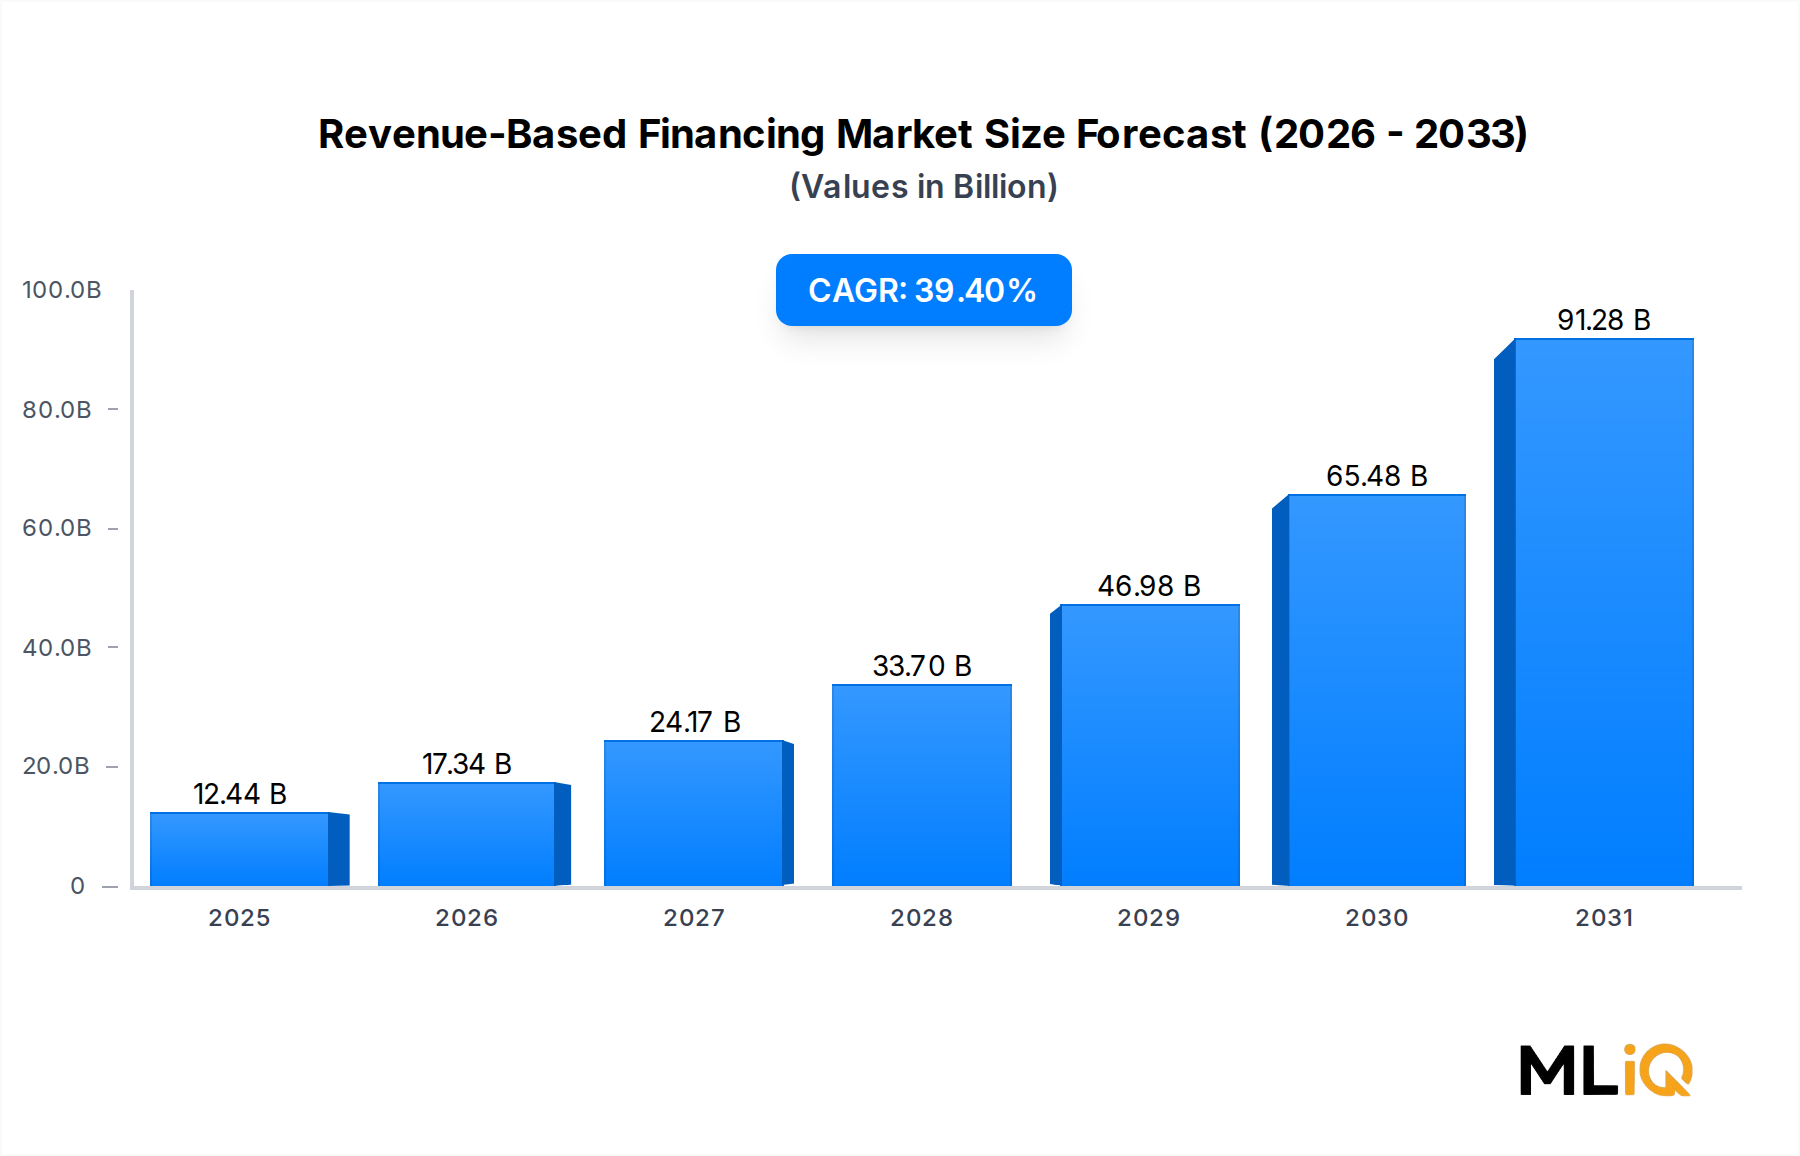
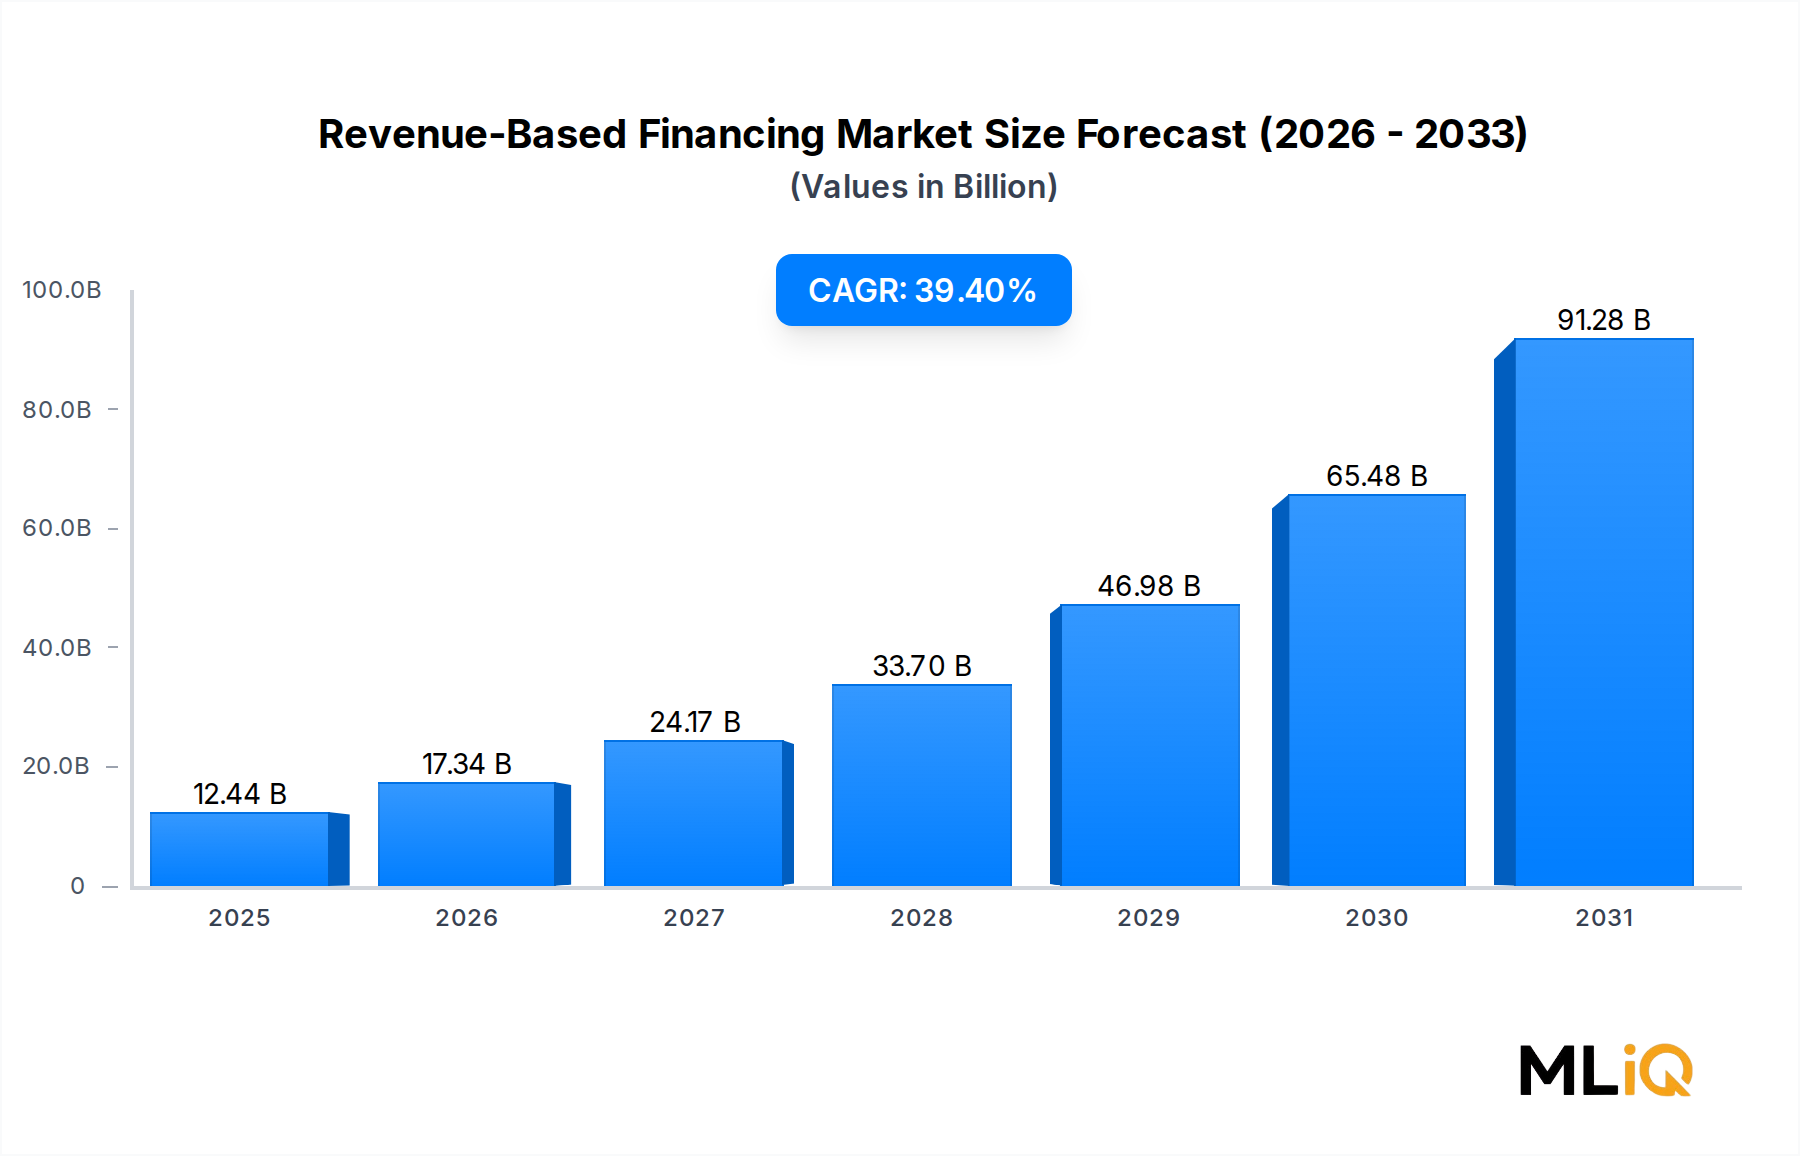
The global Revenue-Based Financing Market was valued at $12.44 billion in the base year and is projected to expand at a compound annual growth rate of 39.4% through 2033, making it one of the fastest-scaling segments within the broader BFSI landscape. This exceptional growth trajectory reflects a structural shift in how early-stage and growth-phase companies access capital, moving away from dilutive equity rounds and rigid bank loans toward flexible, revenue-aligned funding instruments.
At its core, revenue-based financing (RBF) allows businesses to receive upfront capital in exchange for a fixed percentage of future revenues until a predetermined repayment multiple is reached. This model aligns investor and operator incentives in ways traditional debt cannot, creating natural demand among subscription-heavy, digitally native businesses. The proliferation of software-as-a-service companies, direct-to-consumer brands, and platform-economy operators has created a vast and previously underserved addressable market for RBF providers.
Macro tailwinds are reinforcing this demand. Rising interest rates through 2022–2024 significantly increased the cost of traditional bank credit, pushing SMEs and mid-market firms toward non-dilutive alternatives. Simultaneously, venture capital dealmaking contracted meaningfully from its 2021 peak, leaving a funding gap that RBF providers have aggressively moved to fill. According to pipeline activity across leading platforms, average deal sizes have grown from sub-$500,000 to over $2 million across several major providers, signaling market maturation.
The proliferation of API-driven underwriting infrastructure has also accelerated deployment timelines dramatically. Providers now analyze real-time revenue data from Stripe, Shopify, QuickBooks, and similar platforms to underwrite deals in hours rather than weeks. This speed-to-capital advantage is particularly compelling for high-growth companies operating in fast-moving verticals.
Institutional capital flows into RBF vehicles have intensified, with pension funds, family offices, and alternative asset managers allocating to RBF-backed securitization structures. This institutional validation is compressing risk premiums and enabling providers to offer more competitive factor rates.
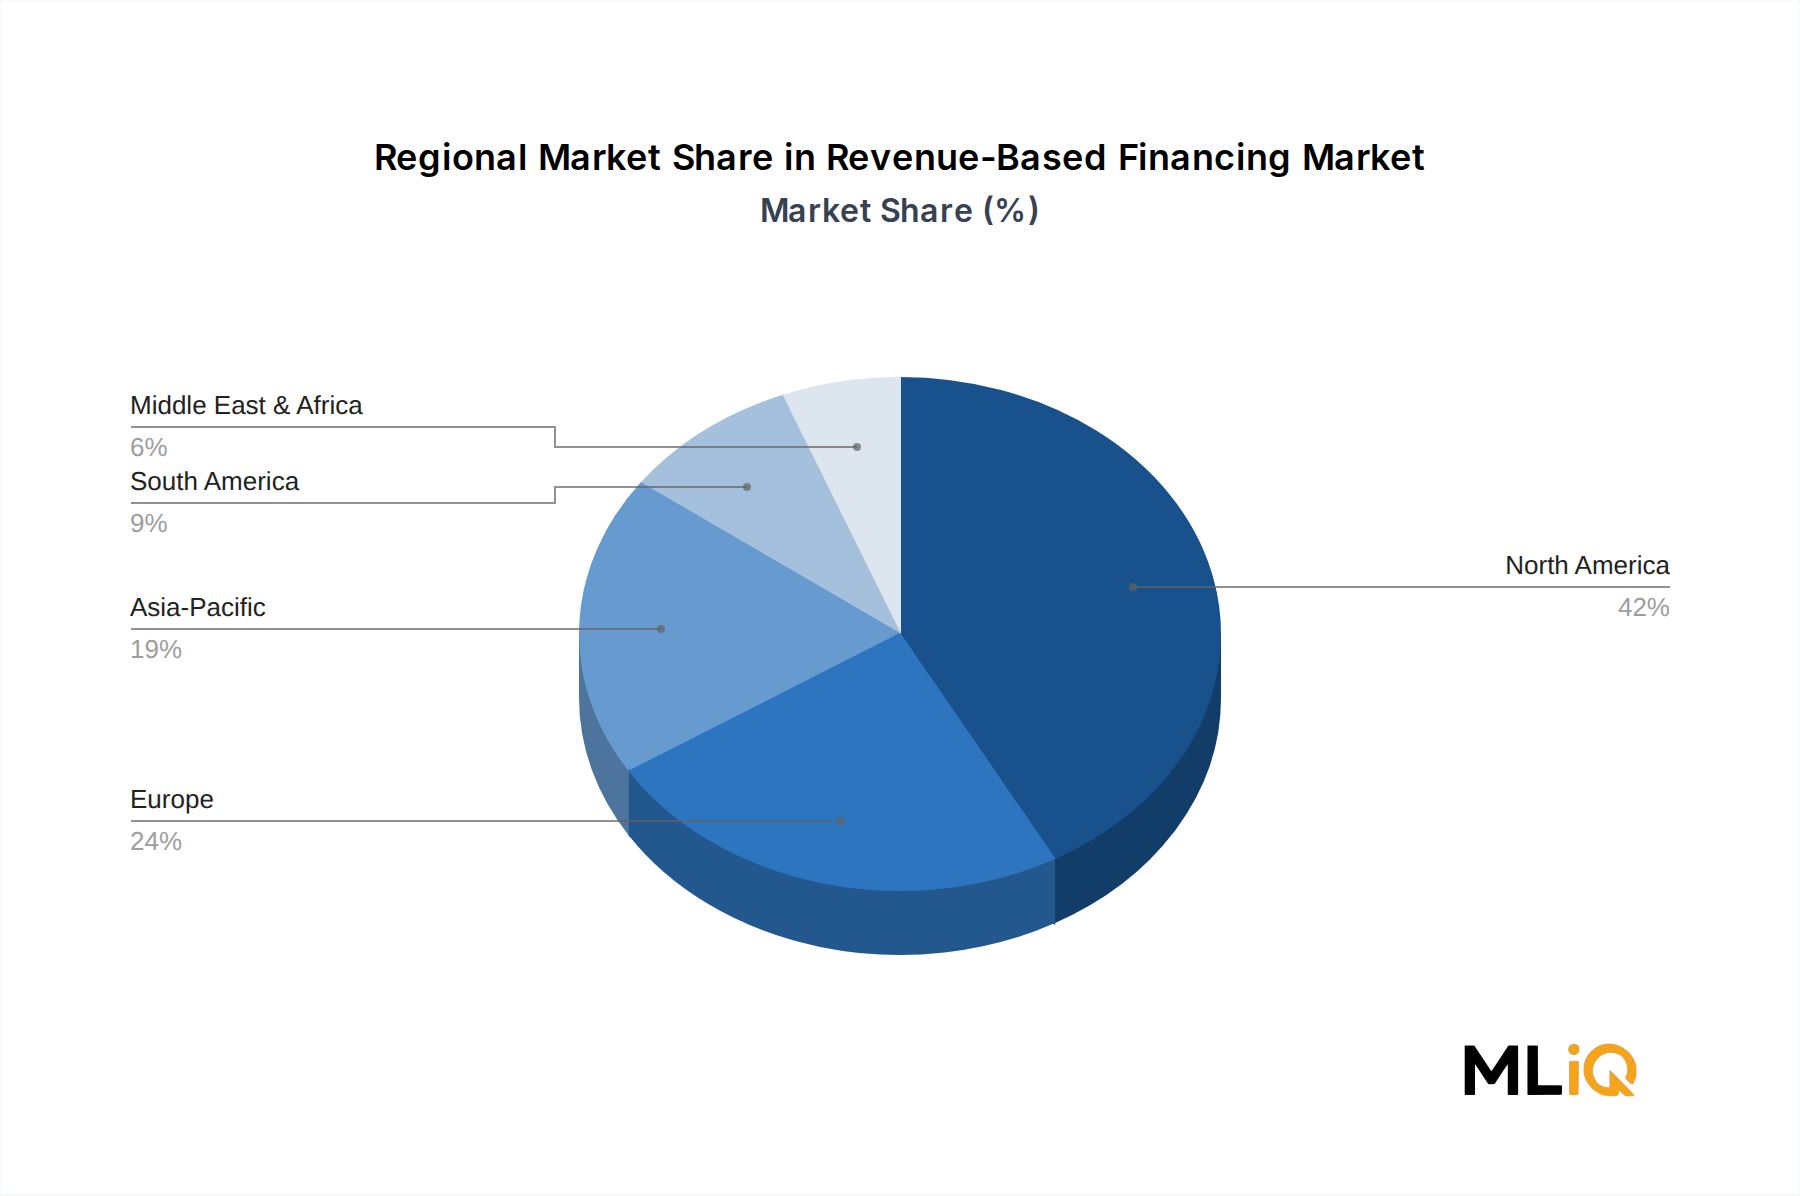
Geographically, North America leads in absolute dollar volumes, while Asia Pacific is emerging as the fastest-growing region, driven by the expansion of fintech ecosystems in India, Southeast Asia, and Australia. Europe is also witnessing accelerating adoption, particularly in the United Kingdom and Germany, where regulatory sandboxes have created favorable innovation environments.
Looking ahead to 2033, the Revenue-Based Financing Market is expected to surpass $150 billion in total facilitated capital, underpinned by continued digitization of SME finance, deepening data infrastructure, and the growing acceptance of RBF as a mainstream asset class among institutional allocators.