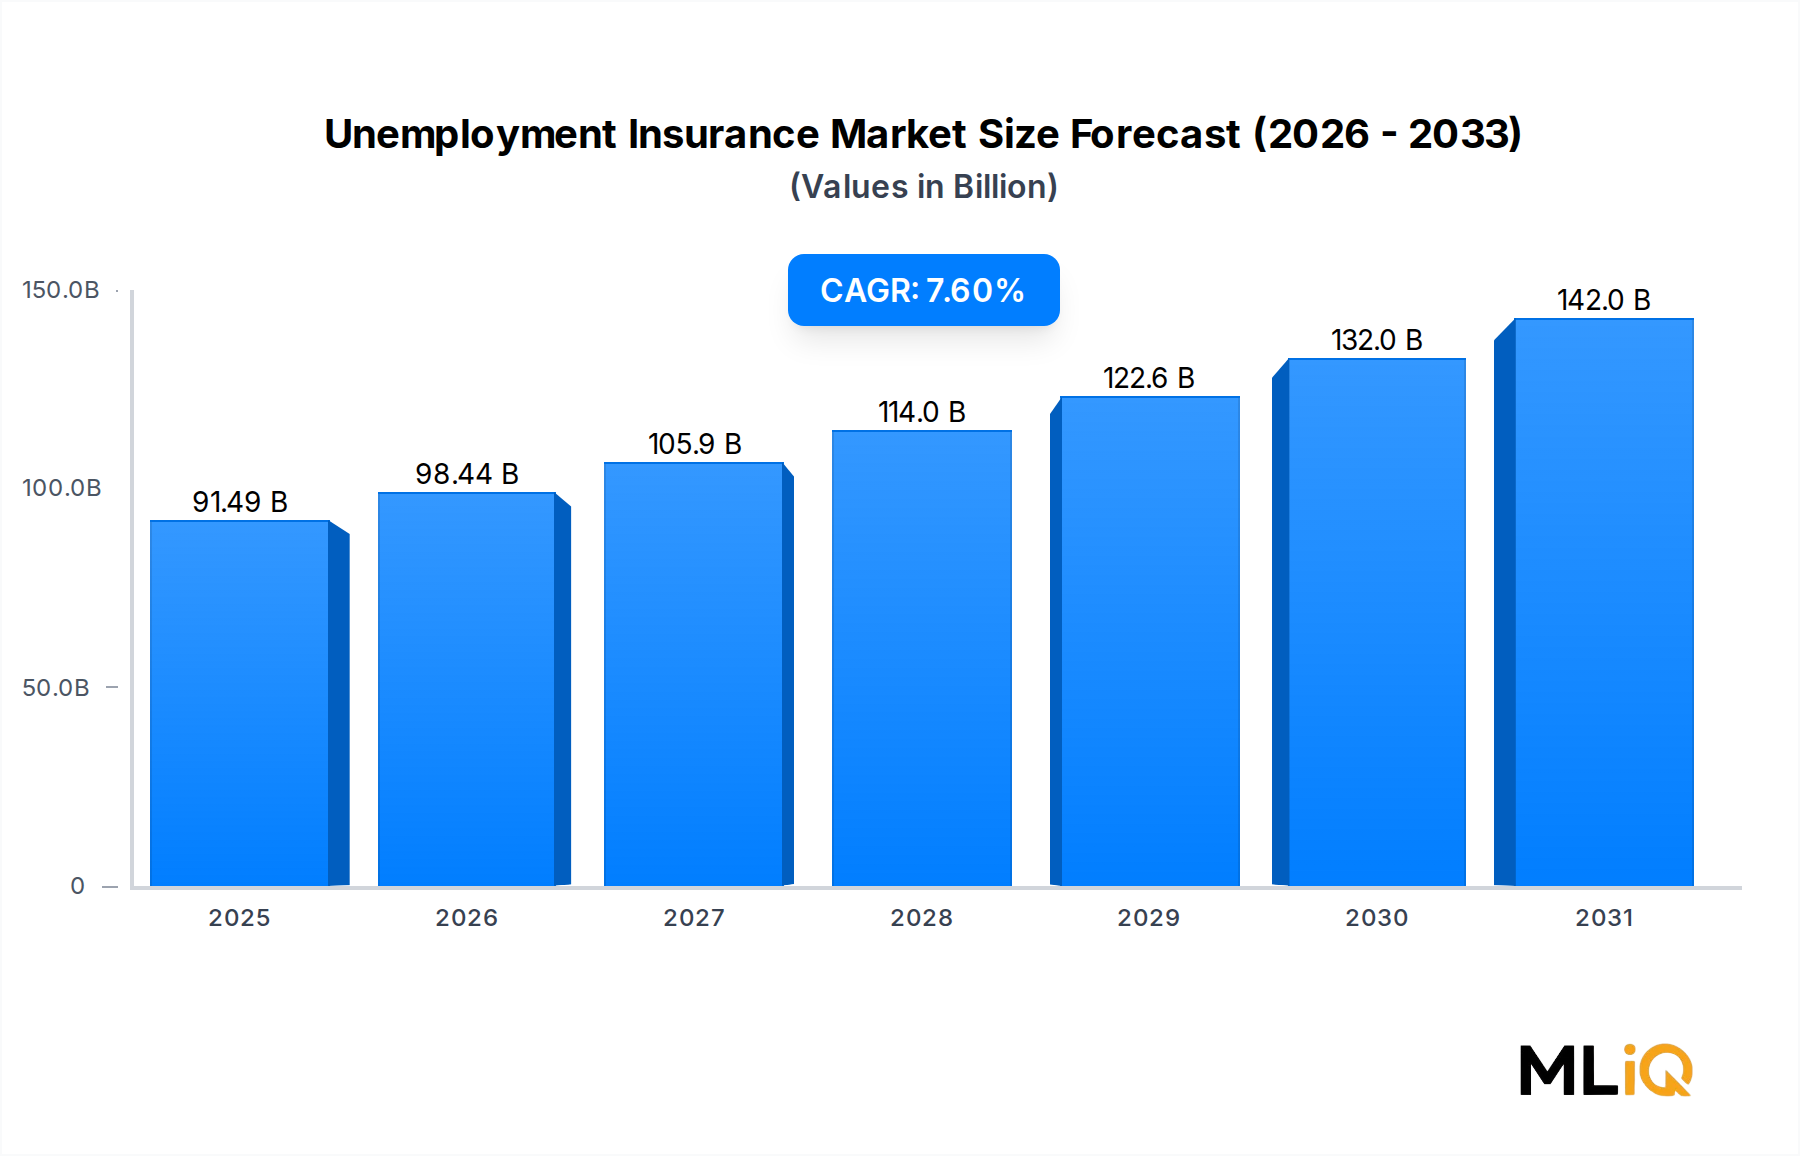
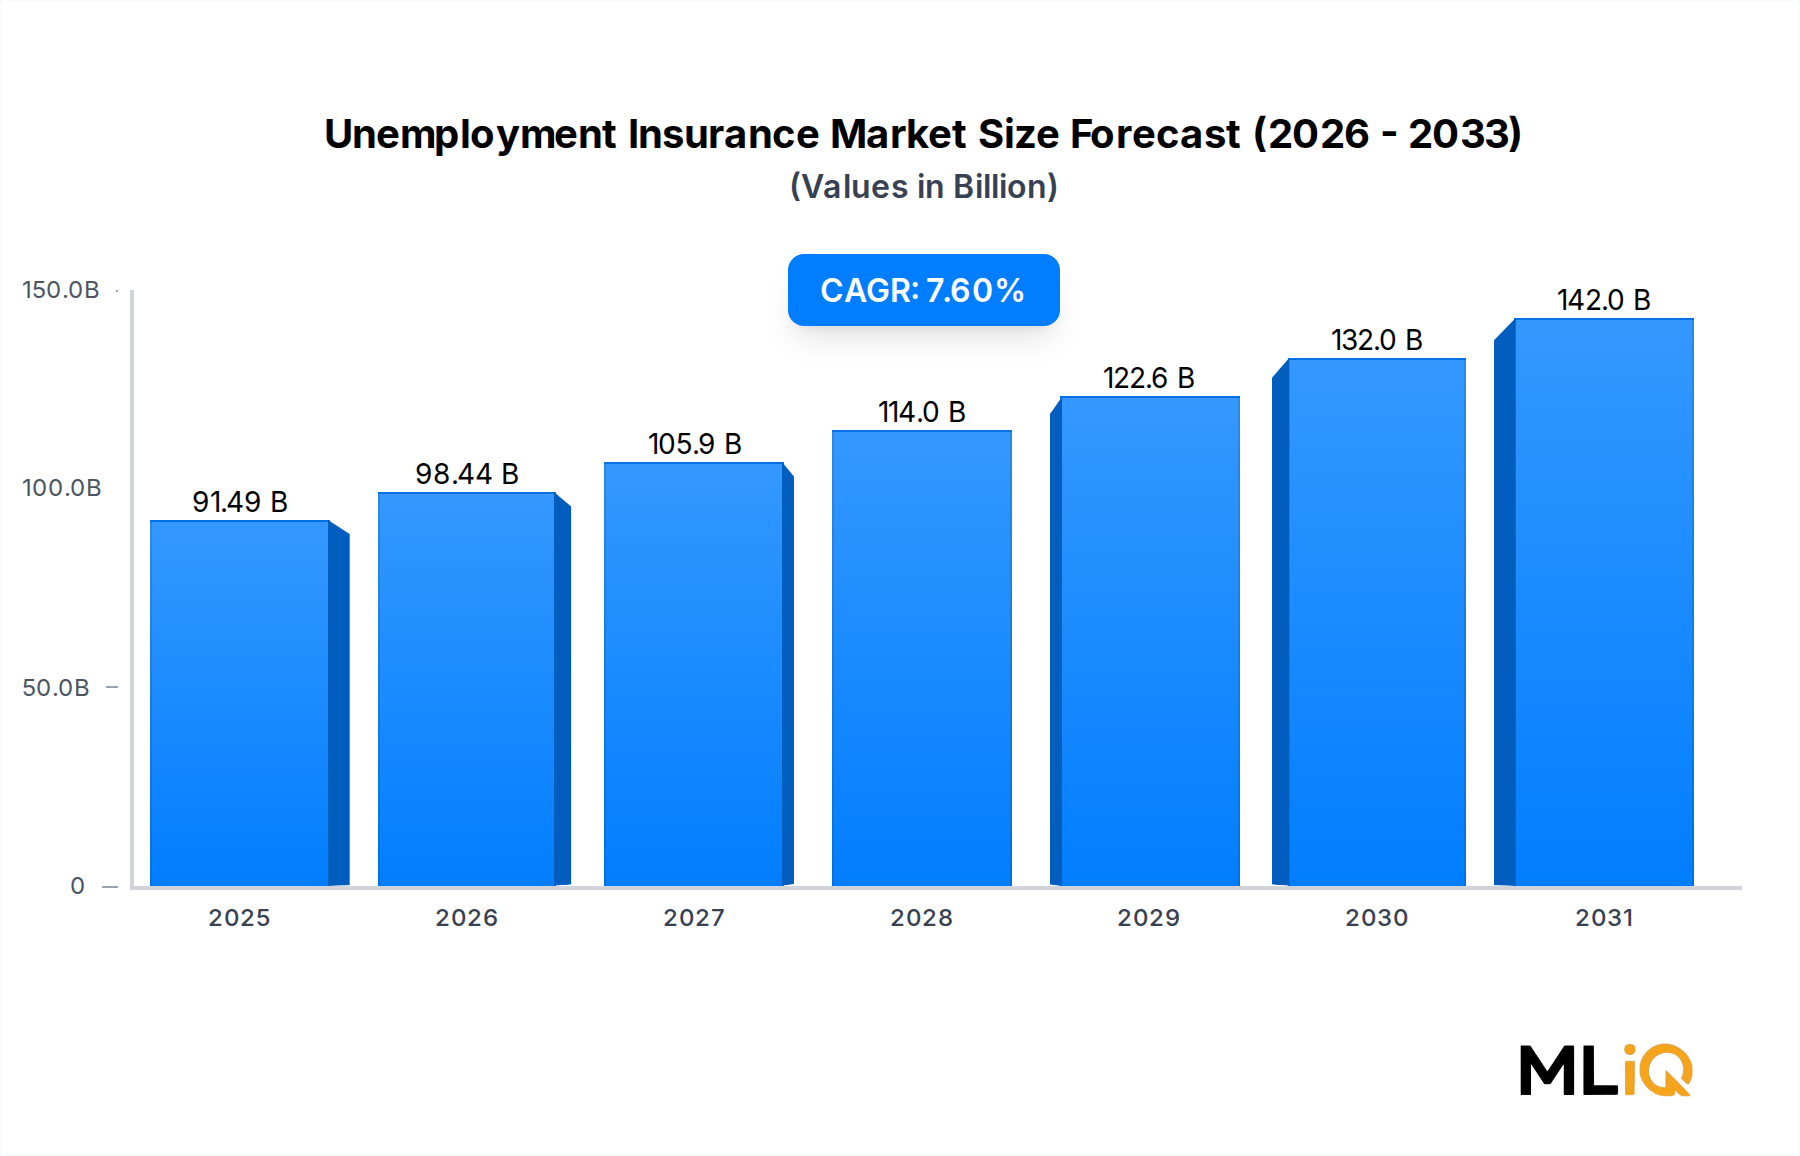
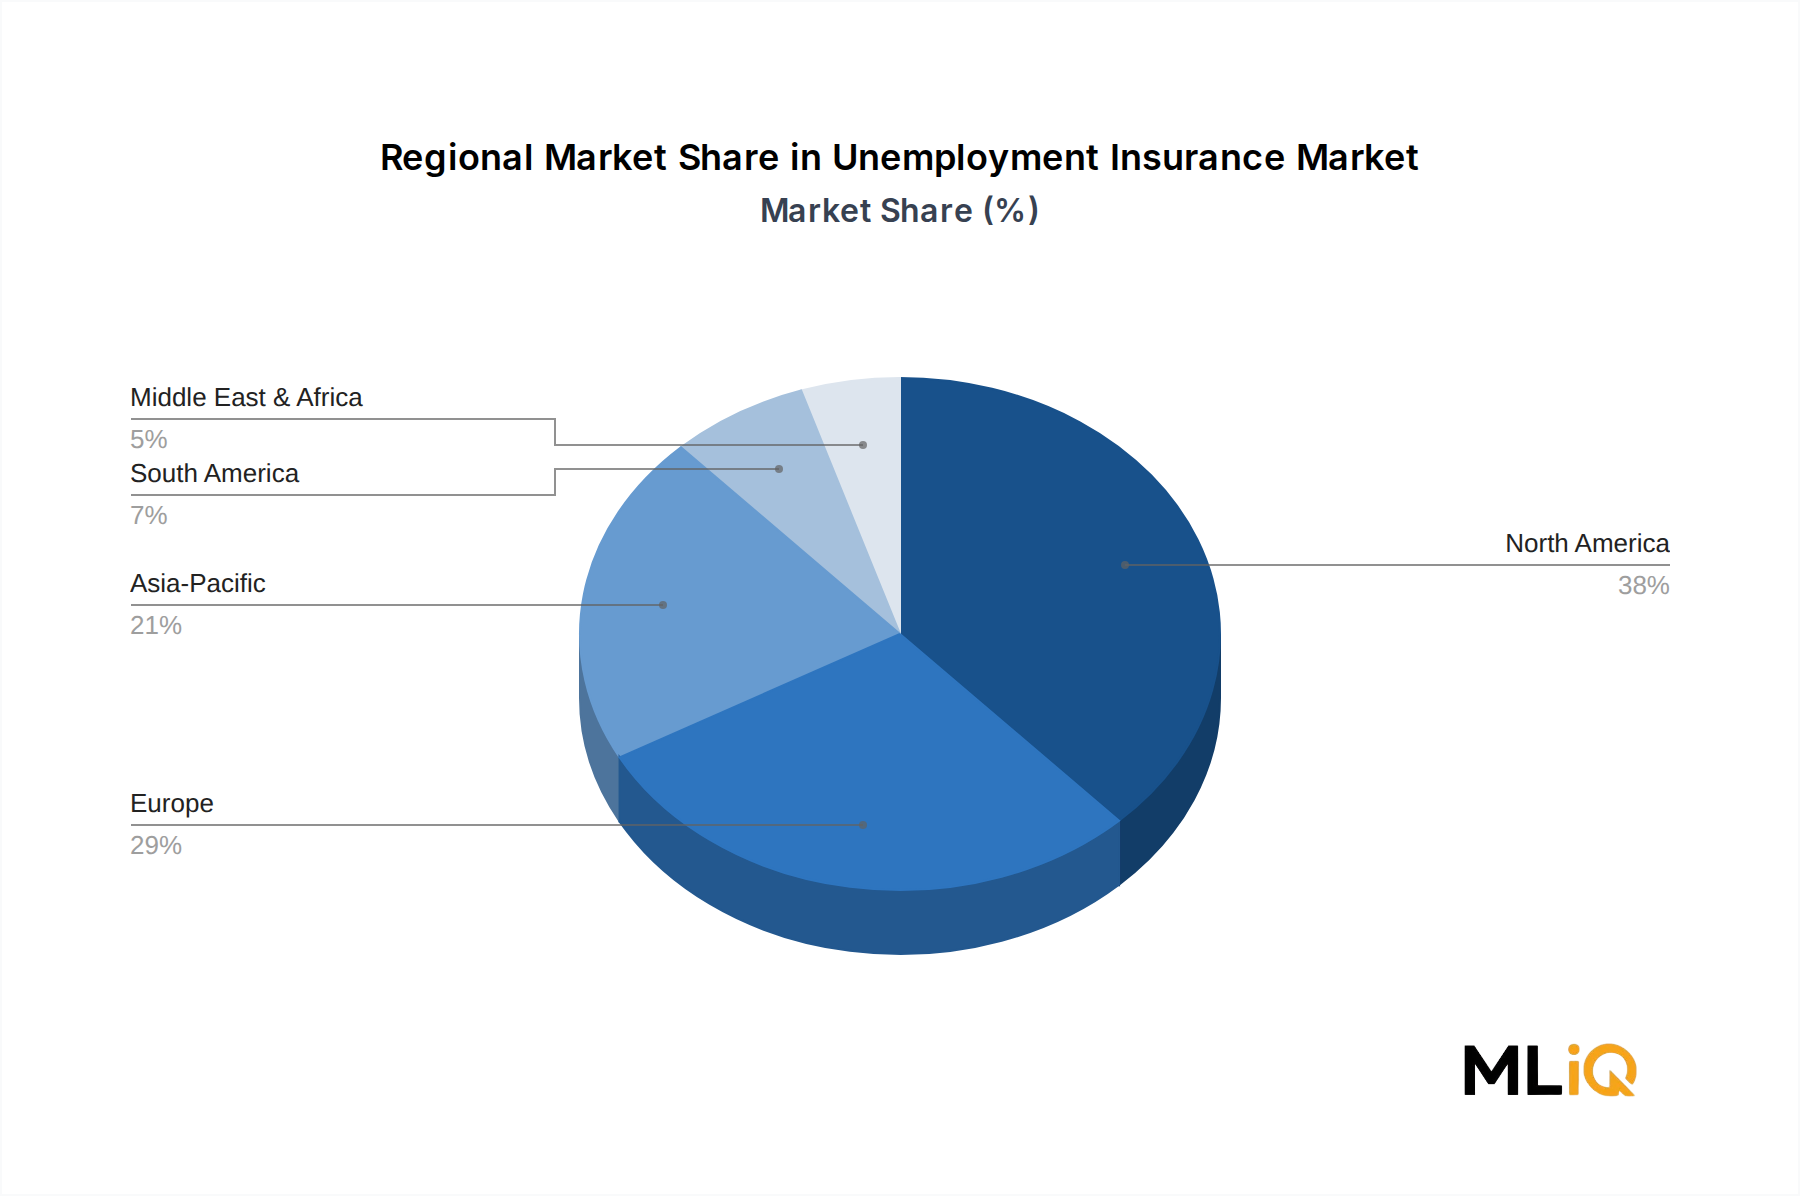
The Unemployment Insurance Market is propelled by a combination of legislative, macroeconomic, and technological drivers, alongside meaningful structural constraints that require careful navigation by market participants.
On the driver side, legislative expansion of eligibility criteria across the European Union represents one of the most significant near-term growth catalysts. Following the EU's 2019 directive on transparent and predictable working conditions, member states have progressively extended unemployment benefit eligibility to part-time workers, temporary contract employees, and platform-based gig workers, collectively adding tens of millions of potential beneficiaries to national unemployment insurance frameworks. This legislative broadening directly expands the addressable premium and administrative services market.
In the United States, the experience of administering over $800 billion in unemployment insurance benefits during the 2020–2021 pandemic period exposed systemic inefficiencies in legacy claims infrastructure, catalyzing multi-billion-dollar state-level investment in modernization. These investments are channeling capital toward digital claims portals, identity verification systems, and fraud detection platforms that interface with the broader Insurance Claims Management Market and the Insurance Analytics Platform Market.
Labor market formalization in South and Southeast Asia, where informal employment has historically excluded workers from statutory unemployment benefits, is creating greenfield expansion opportunities. Countries including India, Indonesia, and Vietnam are at various stages of developing or expanding unemployment insurance frameworks, with India's Employees' State Insurance scheme projected to extend coverage to an additional 50+ million workers by 2027.
On the constraint side, fraud and improper payments remain a persistent challenge. The U.S. Department of Labor estimated that improper unemployment payments exceeded $60 billion during the pandemic period, triggering heightened scrutiny, tighter eligibility verification requirements, and increased compliance costs for administrators. This fraud risk elevates operational expenditure and depresses net program efficiency metrics. Additionally, political resistance to expanding employer payroll tax contributions, which fund unemployment insurance reserves in most markets, limits the pace at which benefit levels and coverage breadth can be expanded without creating fiscal imbalance.