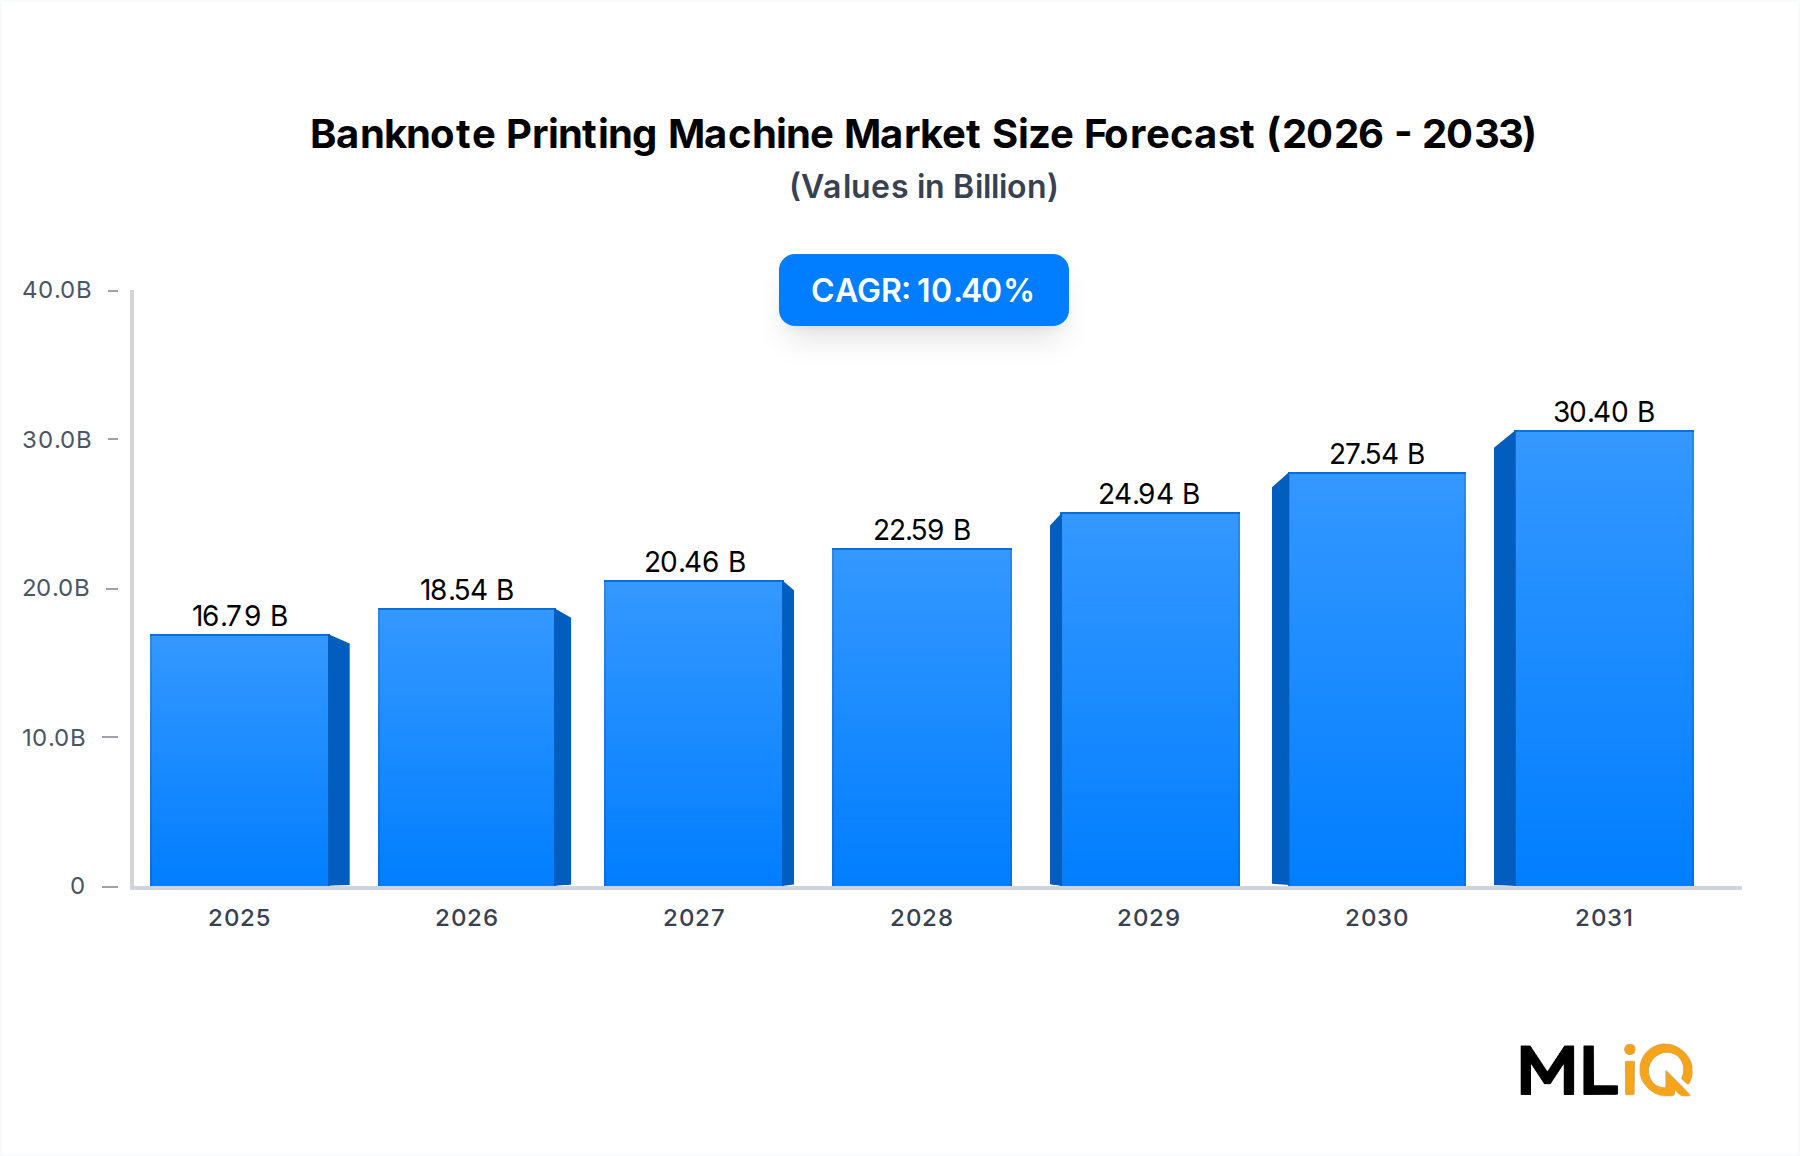
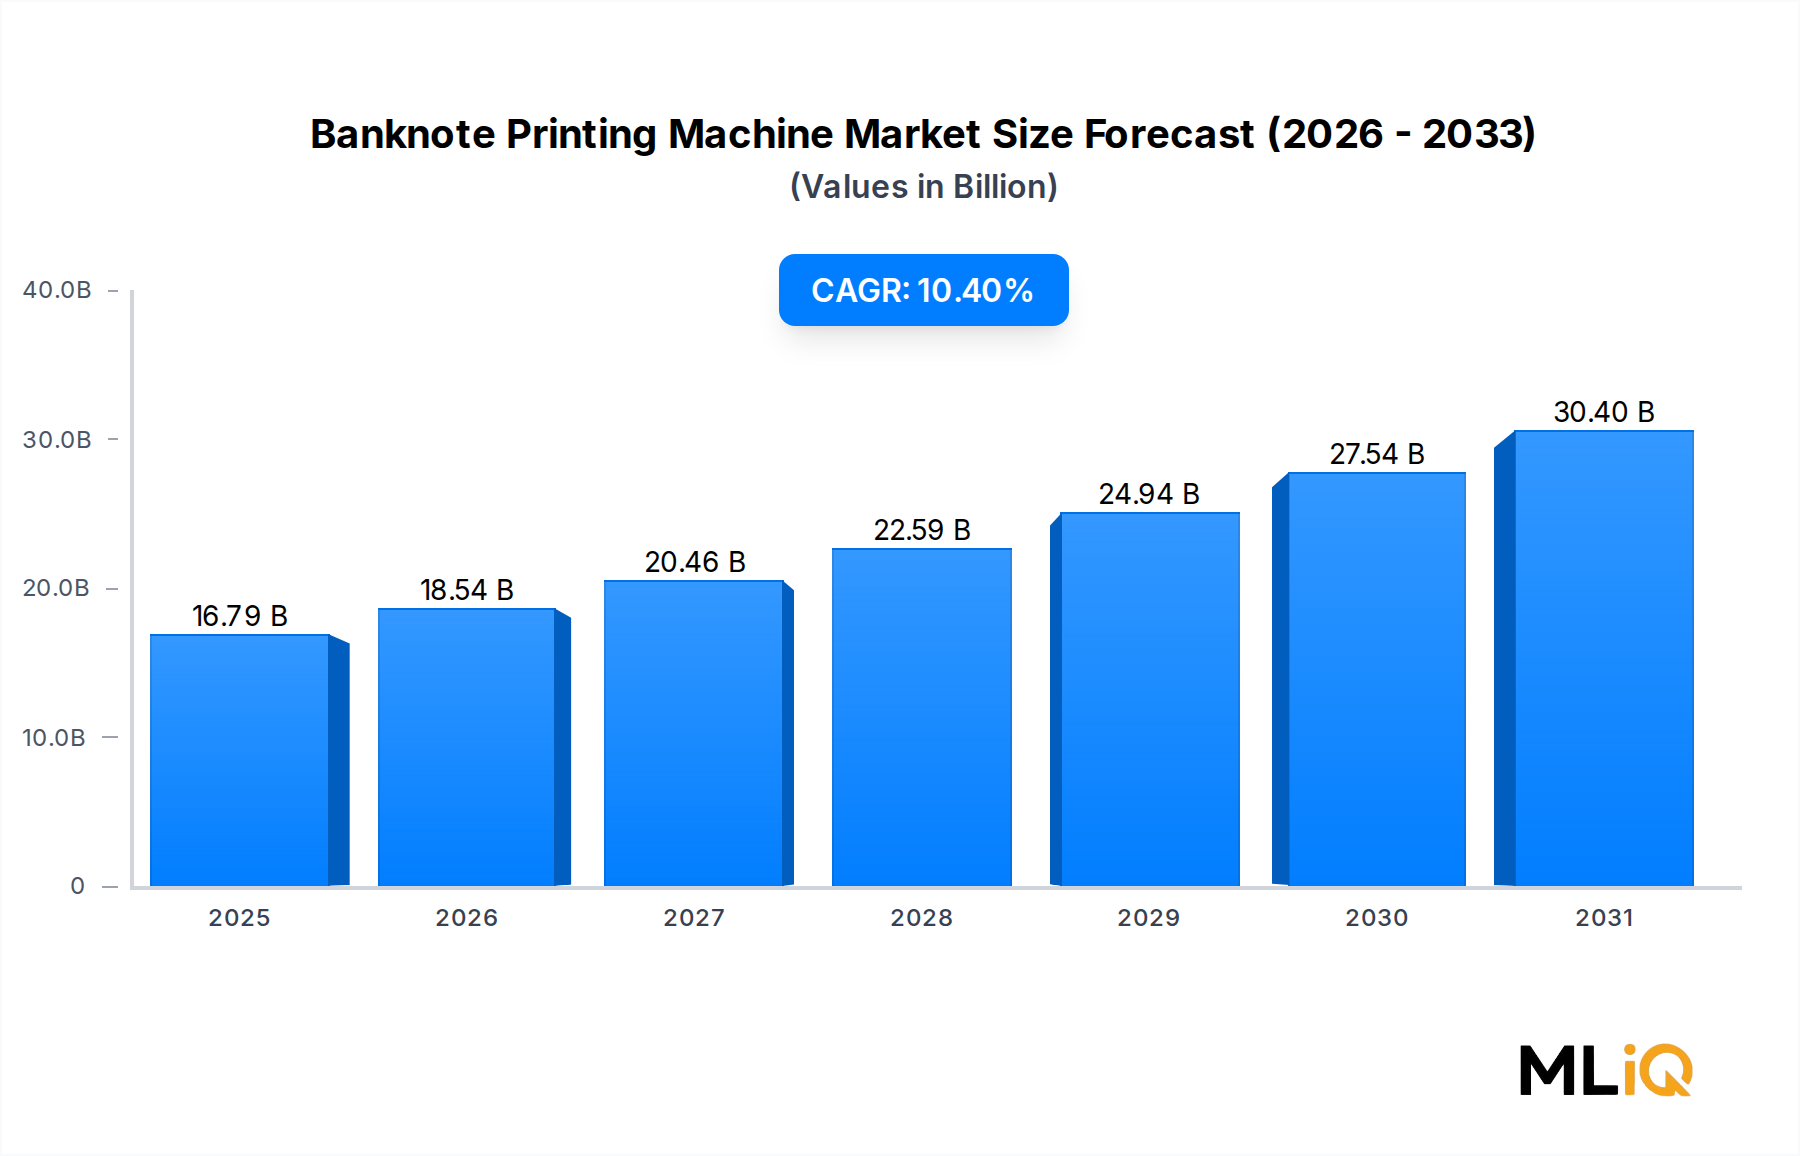
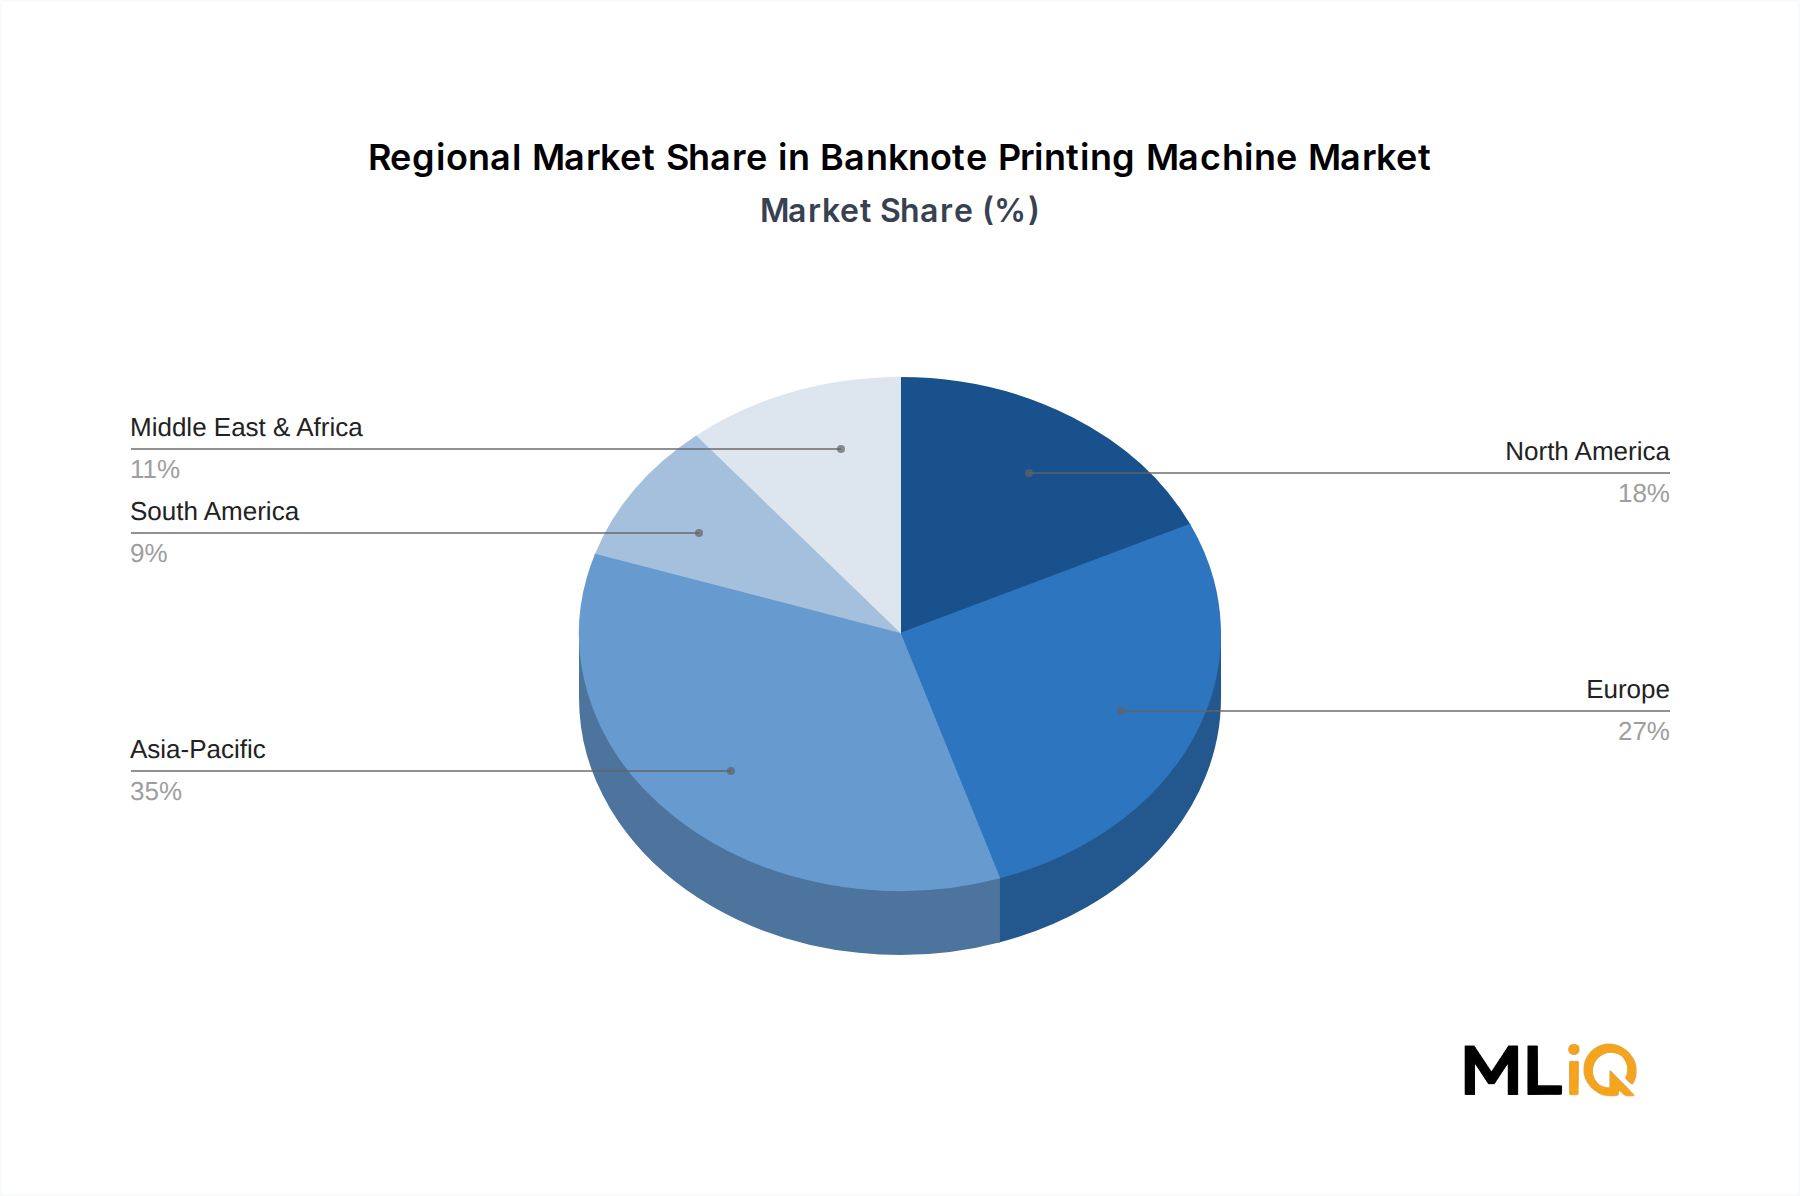
Several quantifiable drivers and measurable constraints define the current competitive and investment landscape of the Banknote Printing Machine Market.
Driver 1 — Rising Global Currency Circulation: The Bank for International Settlements (BIS) reports that global currency in circulation grew by approximately 5–8% annually across key emerging economies between 2018 and 2023. Nations such as India, Indonesia, Nigeria, and Brazil have experienced sustained CIC expansion driven by unbanked population segments and rural transaction preferences, directly fueling central bank procurement of new printing capacity.
Driver 2 — Counterfeiting Risk Escalation: Interpol and Europol have jointly reported that counterfeiting incidents involving high-denomination notes have increased by over 12% in select regions over the past five years. In response, central banks are accelerating note redesign cycles — historically averaging 7–10 years — compressing them to as few as 4–5 years, which significantly increases demand for press reconfiguration and new equipment procurement.
Driver 3 — Polymer Substrate Adoption: Over 40 countries have transitioned at least one denomination to polymer substrates as of 2024, according to the Currency Research organization. Polymer printing requires modified press systems with adapted ink delivery and drying configurations, creating a substantial equipment upgrade and replacement demand wave.
Constraint 1 — Extremely High Capital Expenditure: The per-unit cost of a full intaglio and offset printing line can exceed $30 million when integrated with inspection, numbering, and bundling systems. This limits procurement to well-capitalized sovereign entities and creates long sales cycles of 2–4 years, constraining revenue velocity for vendors.
Constraint 2 — Geopolitical Export Controls: Advanced printing technologies classified as dual-use goods are subject to export licensing regimes under frameworks such as the Wassenaar Arrangement. These controls can delay or block equipment delivery to certain markets, introducing revenue uncertainty for internationally active vendors.
Constraint 3 — Digital Currency Substitution Risk: 22 countries have launched fully operational Central Bank Digital Currencies (CBDCs) as of 2025, and while physical cash is not being displaced at pace, long-term demand forecasts for printed currency volumes carry heightened uncertainty, which may dampen multi-decade capital investment decisions by some central banks.