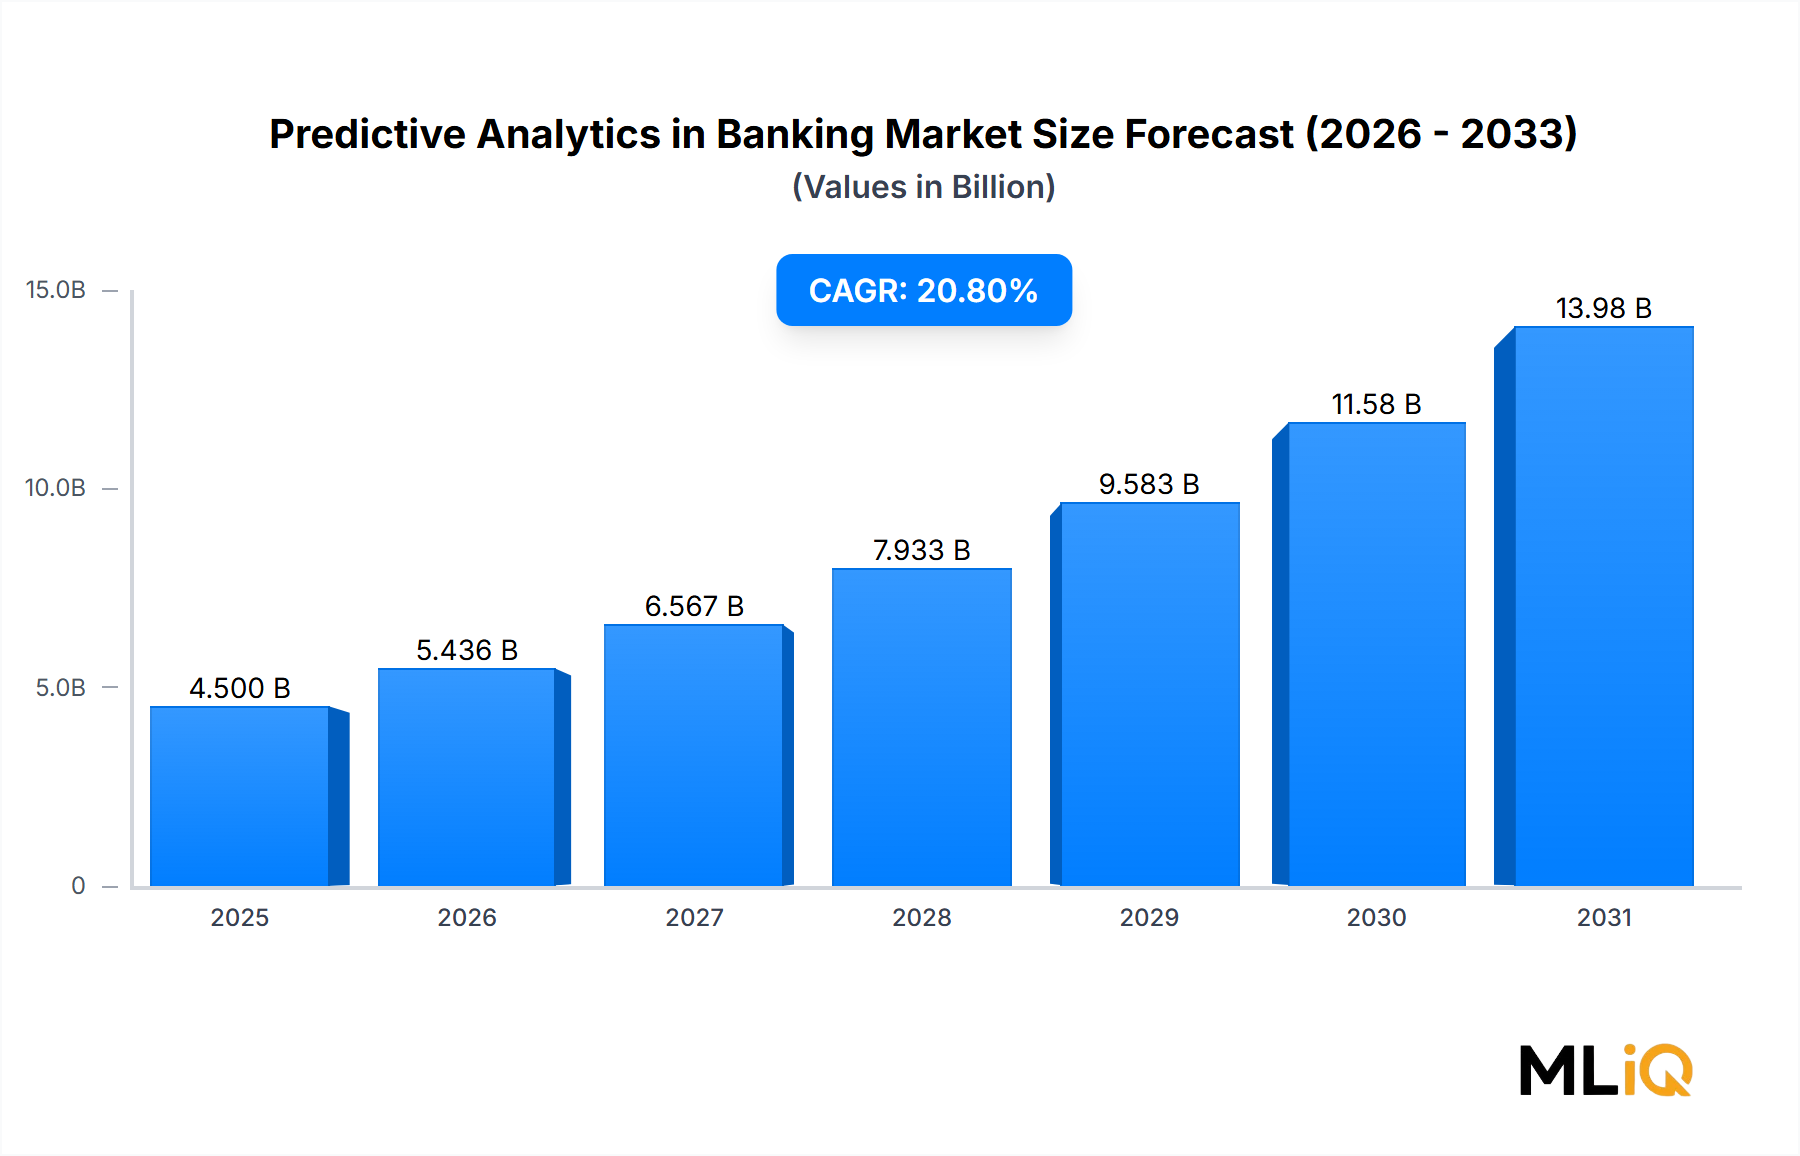
The global Predictive Analytics in Banking Market was valued at $4.50 billion in the base year and is projected to expand at a compound annual growth rate (CAGR) of 20.80% through the forecast period spanning 2025 to 2033. This robust trajectory places the market on course to surpass $22 billion by 2033, driven by an accelerating convergence of artificial intelligence, machine learning, and cloud-based data infrastructure within the banking sector.
Banking institutions worldwide are under mounting pressure to reduce non-performing assets, combat increasingly sophisticated financial fraud, and deliver hyper-personalized customer experiences at scale. Predictive analytics addresses all three imperatives simultaneously, making it one of the highest-priority technology investments across retail banking, commercial banking, and investment banking operations. Regulatory mandates across major economies — including Basel III capital adequacy requirements, anti-money laundering directives, and consumer data protection laws — further compel banks to adopt data-driven decision frameworks, reinforcing demand.
Macro tailwinds include the exponential growth in structured and unstructured financial data, declining costs of cloud storage and computational power, and an expanding ecosystem of open banking APIs that enrich model training datasets. The proliferation of digital banking channels — mobile apps, online portals, and embedded finance platforms — generates real-time transaction streams that feed predictive models with previously unavailable behavioral signals.
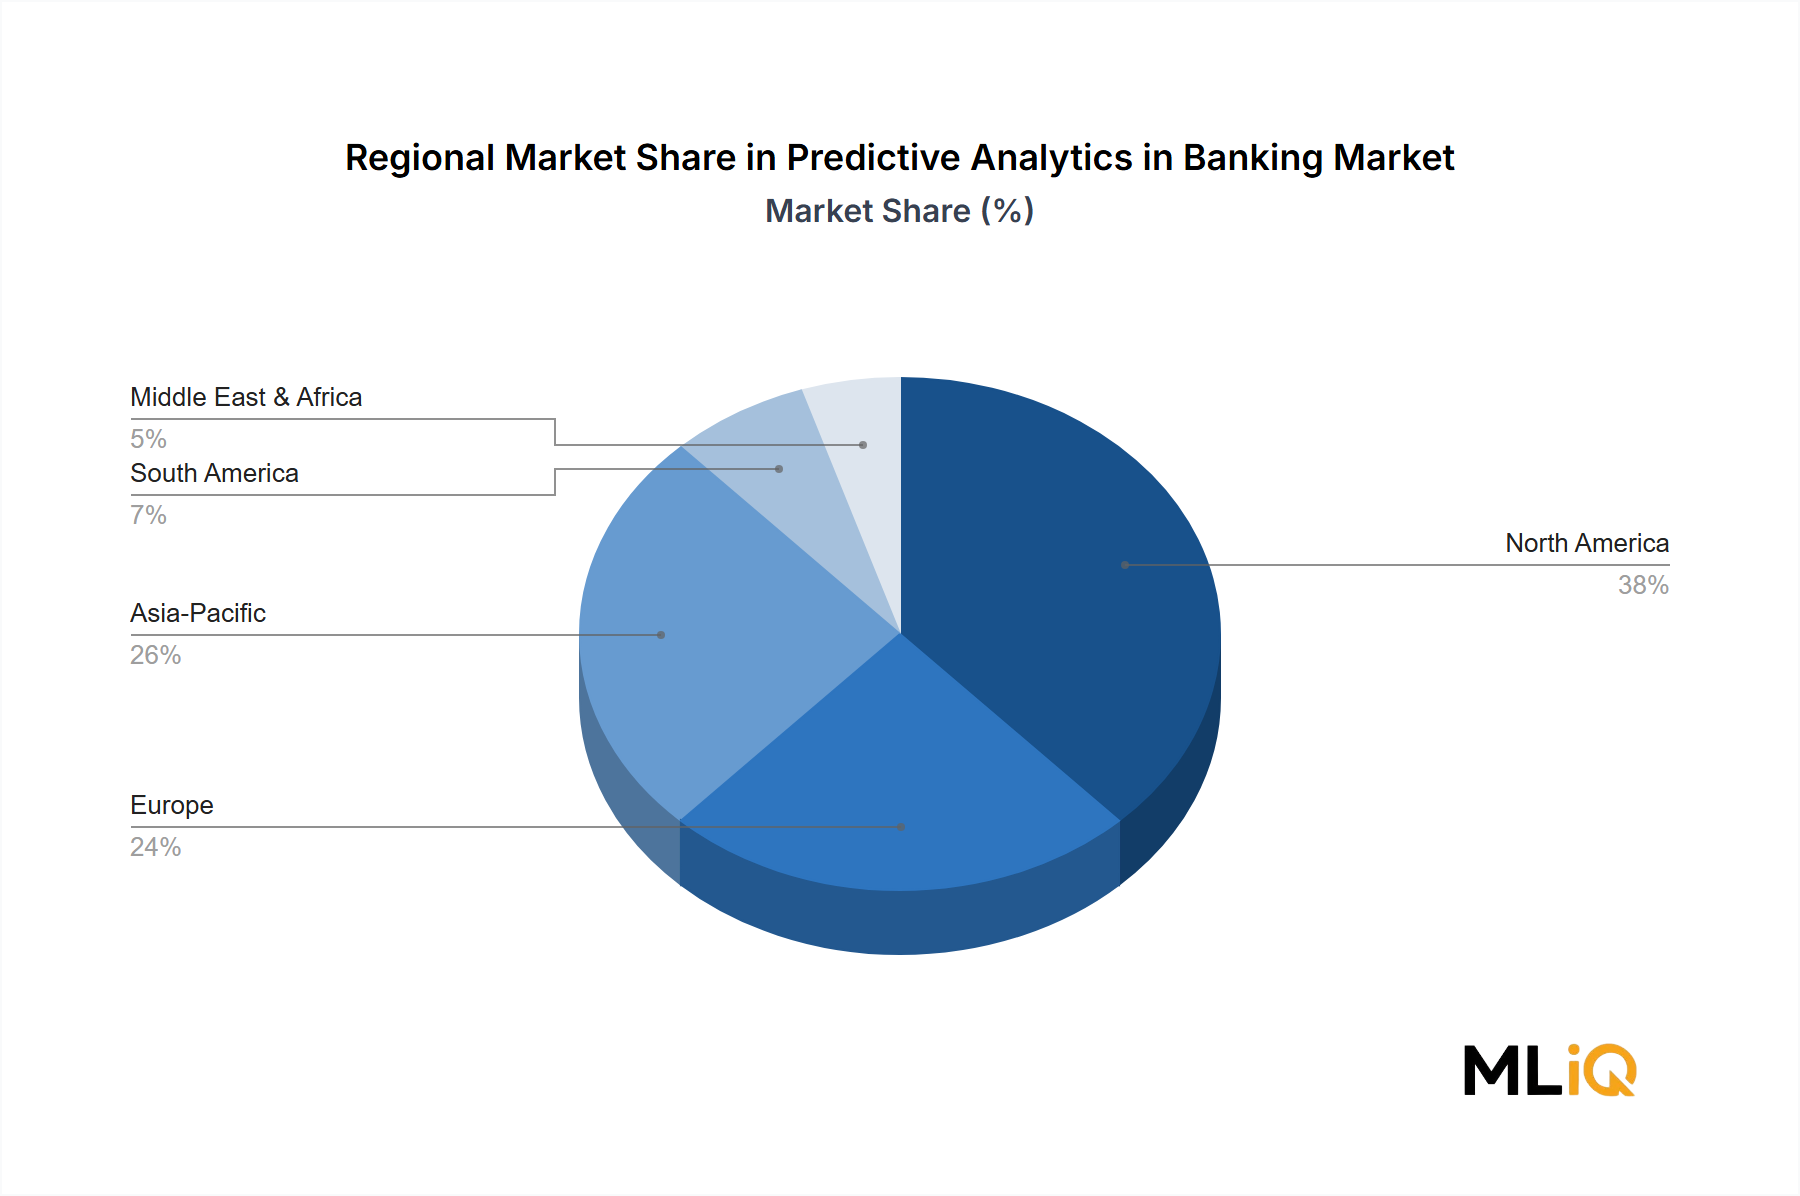
North America currently commands the largest revenue share, underpinned by early technology adoption, a dense concentration of Tier-1 financial institutions, and substantial venture and enterprise software investment. Asia Pacific, however, is the fastest-growing region, propelled by rapid digital banking penetration in China, India, and Southeast Asia, where legacy infrastructure constraints are leapfrogged through cloud-native deployment.
On the competitive front, incumbent enterprise software vendors such as IBM Corporation, Oracle Corporation, and SAS Institute, Inc. face intensifying competition from agile analytics pure-plays and hyperscaler platforms. Strategic differentiators increasingly hinge on explainability of model outputs — a critical requirement under emerging AI governance regulations in the European Union and the United States.
Looking ahead, the integration of generative AI with traditional predictive modeling, the maturation of federated learning frameworks that preserve data privacy, and the mainstreaming of real-time decisioning engines will define the next phase of market evolution. Institutions that establish robust data governance architectures and invest in model risk management capabilities will be best positioned to capture the compounding returns from predictive analytics deployment.