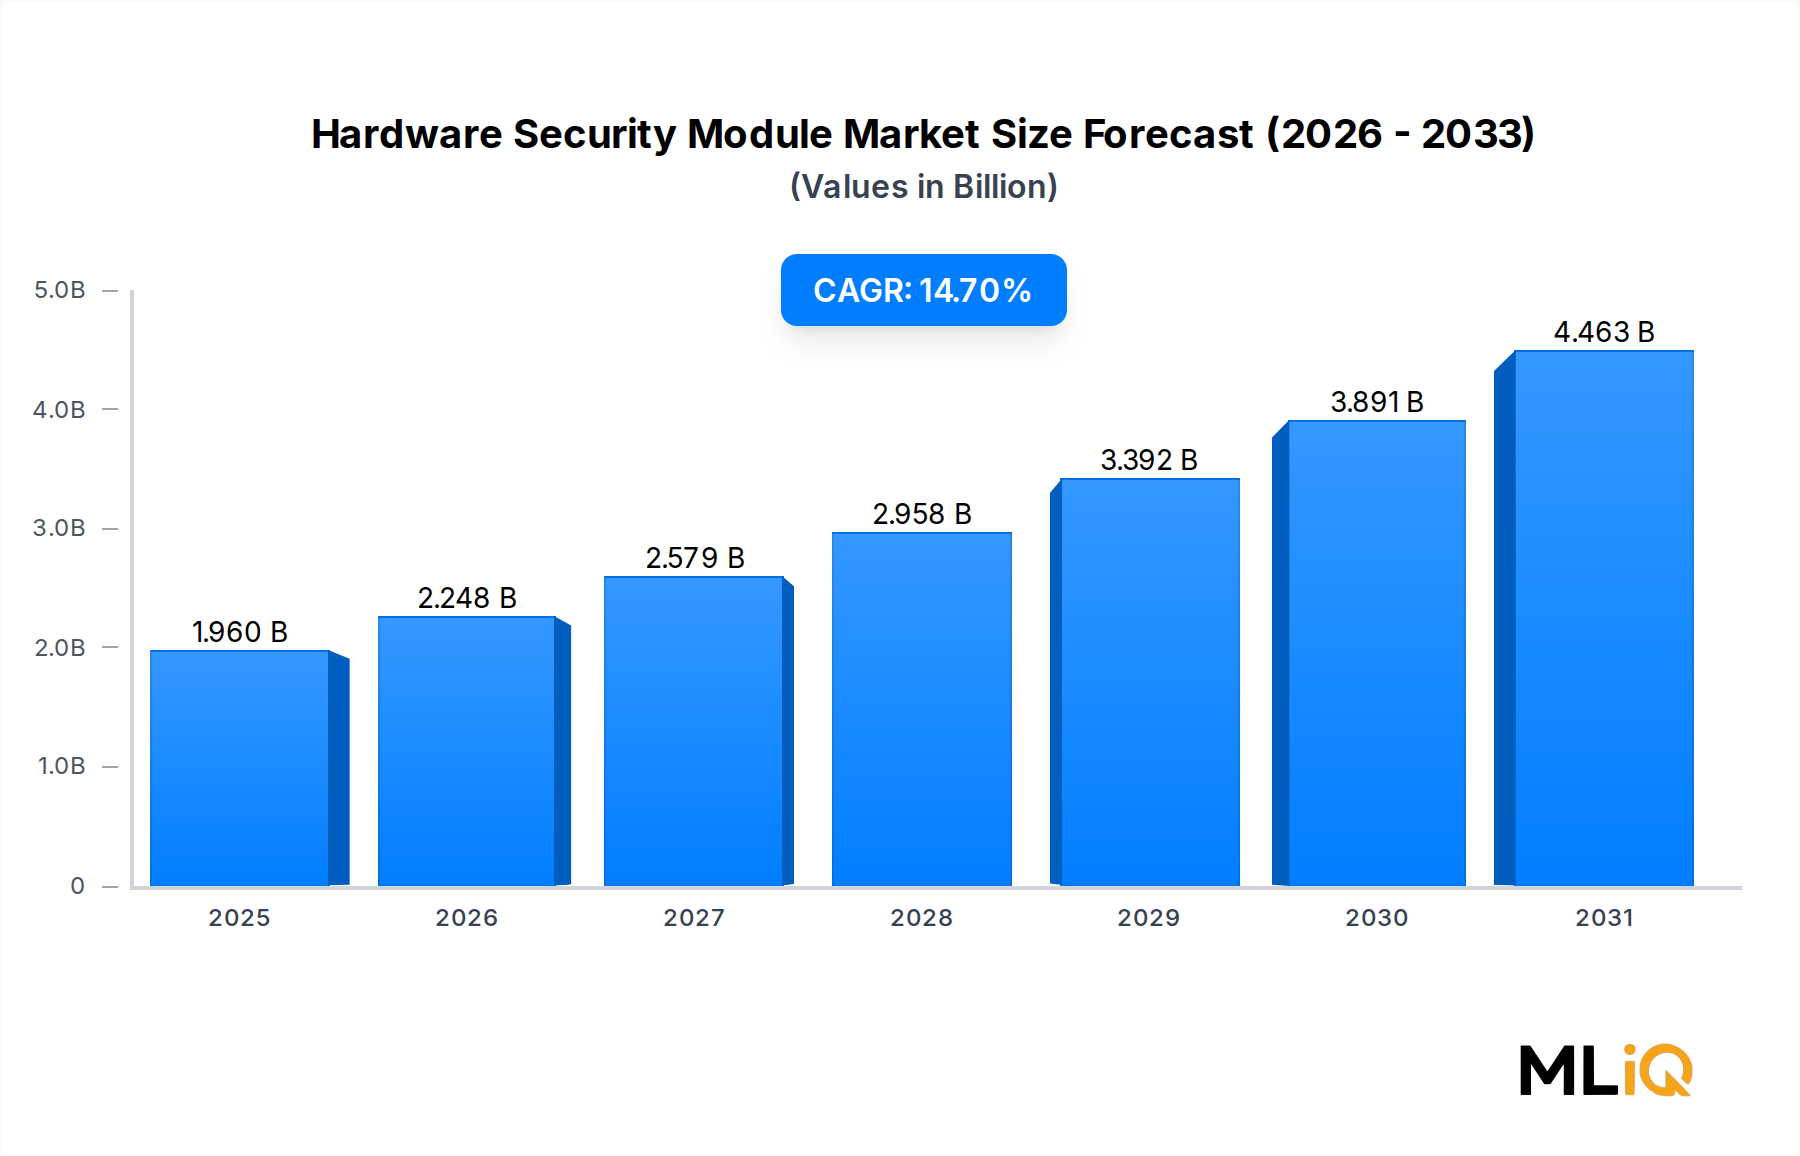
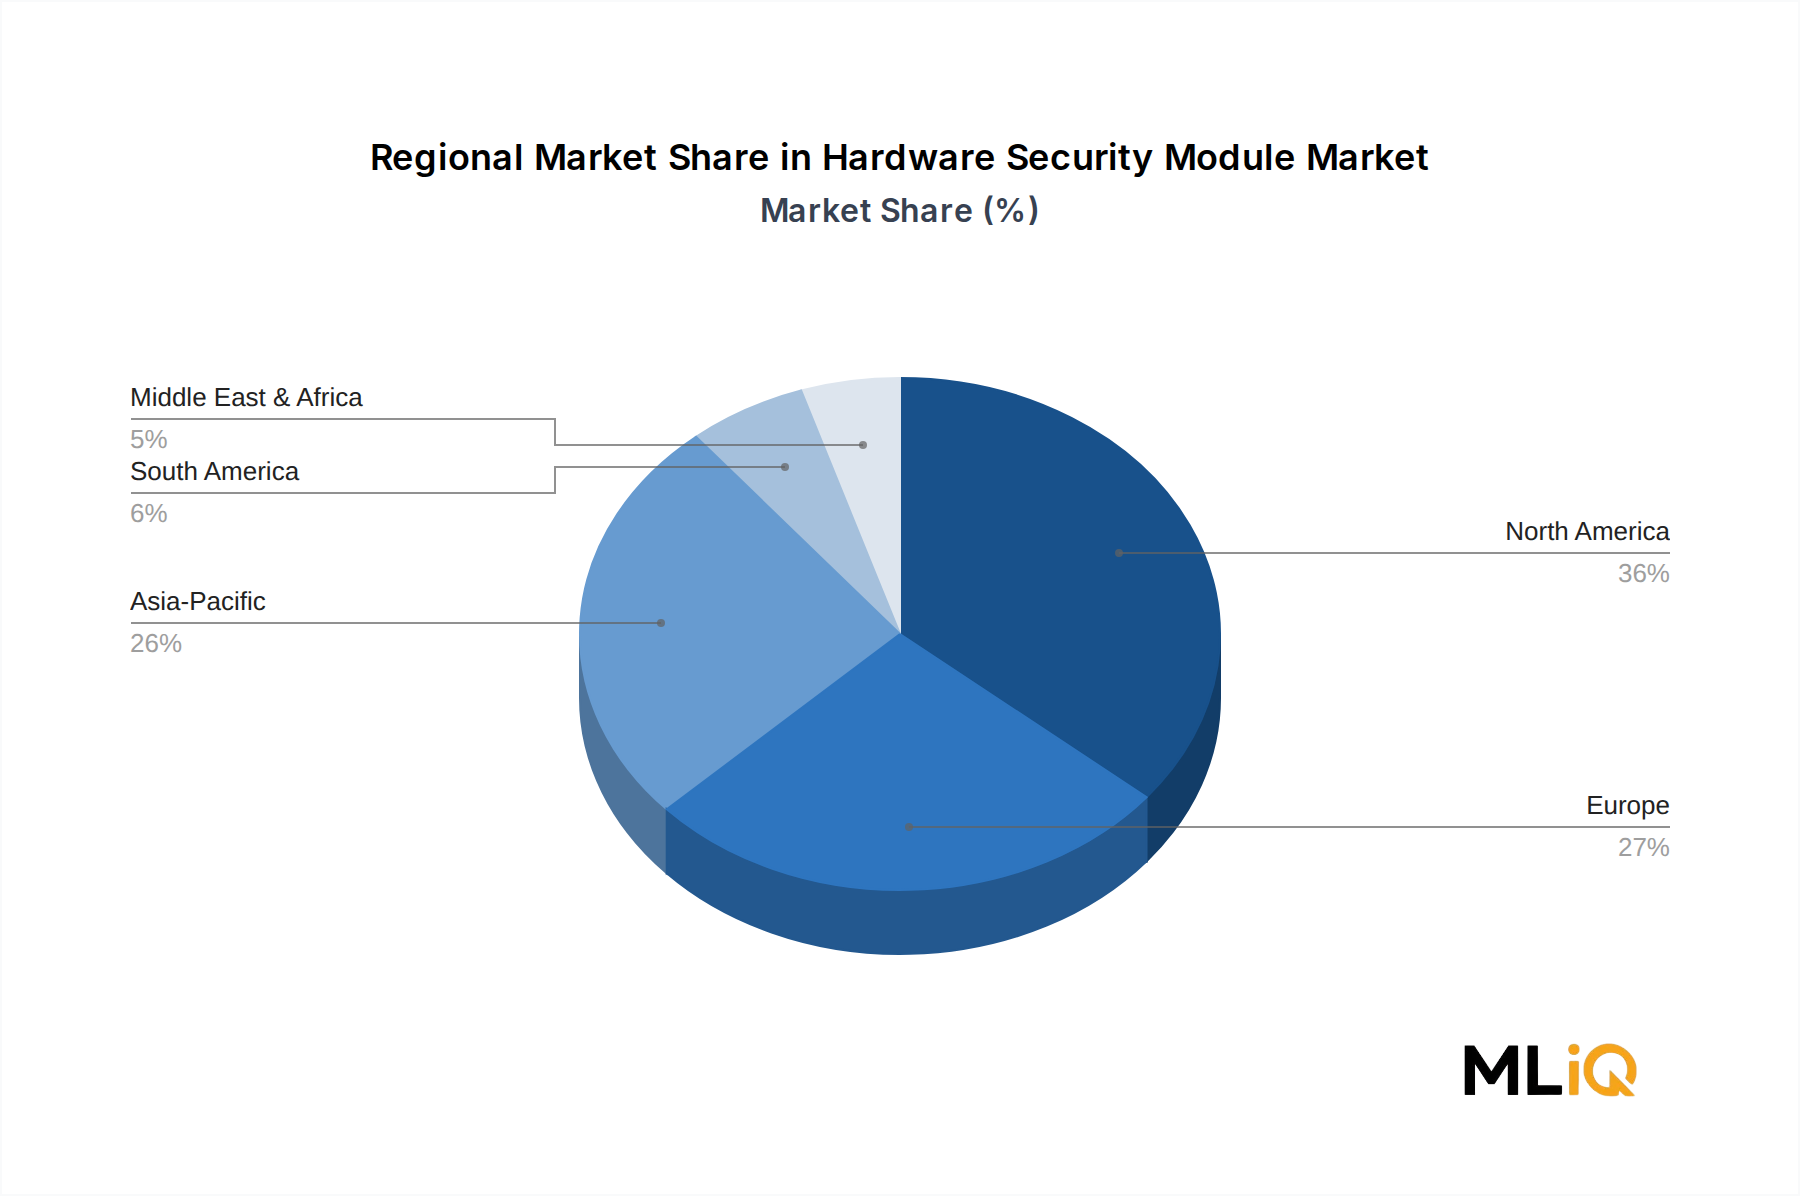
The Hardware Security Module Market is propelled by a set of concrete, measurable demand catalysts while also navigating a distinct set of structural constraints that modulate adoption velocity.
Among the primary drivers, regulatory compliance mandates represent the single most reliable demand catalyst. PCI-DSS v4.0, which became effective in March 2024, introduced enhanced cryptographic controls that explicitly reference hardware-based key protection, driving upgrade cycles across payment ecosystems. Similarly, the European Union's eIDAS 2.0 regulation, expected to mandate the use of qualified electronic signature devices for certain public-sector transactions, is stimulating HSM procurement across EU member states.
Post-quantum cryptography readiness is an emerging but rapidly intensifying driver. NIST's 2024 finalization of post-quantum cryptographic standards — including CRYSTALS-Kyber and CRYSTALS-Dilithium — has created immediate demand for HSM firmware upgrades and new hardware generations capable of supporting lattice-based cryptographic algorithms. Vendors are racing to deliver FIPS-validated post-quantum HSMs, and early enterprise adopters in defense, finance, and critical infrastructure are initiating procurement cycles now, well ahead of projected quantum threat timelines.
Cloud adoption serves as a dual-edged driver. The migration of workloads to hyperscale cloud environments is expanding the addressable market for cloud HSM services, with AWS CloudHSM, Azure Dedicated HSM, and Google Cloud HSM gaining traction. This growth is interlinked with both the Cloud Security Market and the broader Public Key Infrastructure Market, as organizations require cryptographic anchoring for certificate authorities and key management services deployed in cloud-native environments.
On the constraint side, high total cost of ownership remains a barrier, particularly for small and mid-sized enterprises. Enterprise-grade network-attached HSMs can cost between $20,000 and $100,000 per unit, exclusive of integration, certification, and maintenance costs. This cost structure limits organic penetration in SME segments and in price-sensitive emerging markets.
Skilled personnel shortages in cryptographic engineering further constrain deployment velocity. The operational complexity of HSM integration — spanning API customization, key ceremony management, and audit logging — requires specialized expertise that many organizations lack internally, extending project timelines and increasing total deployment cost.