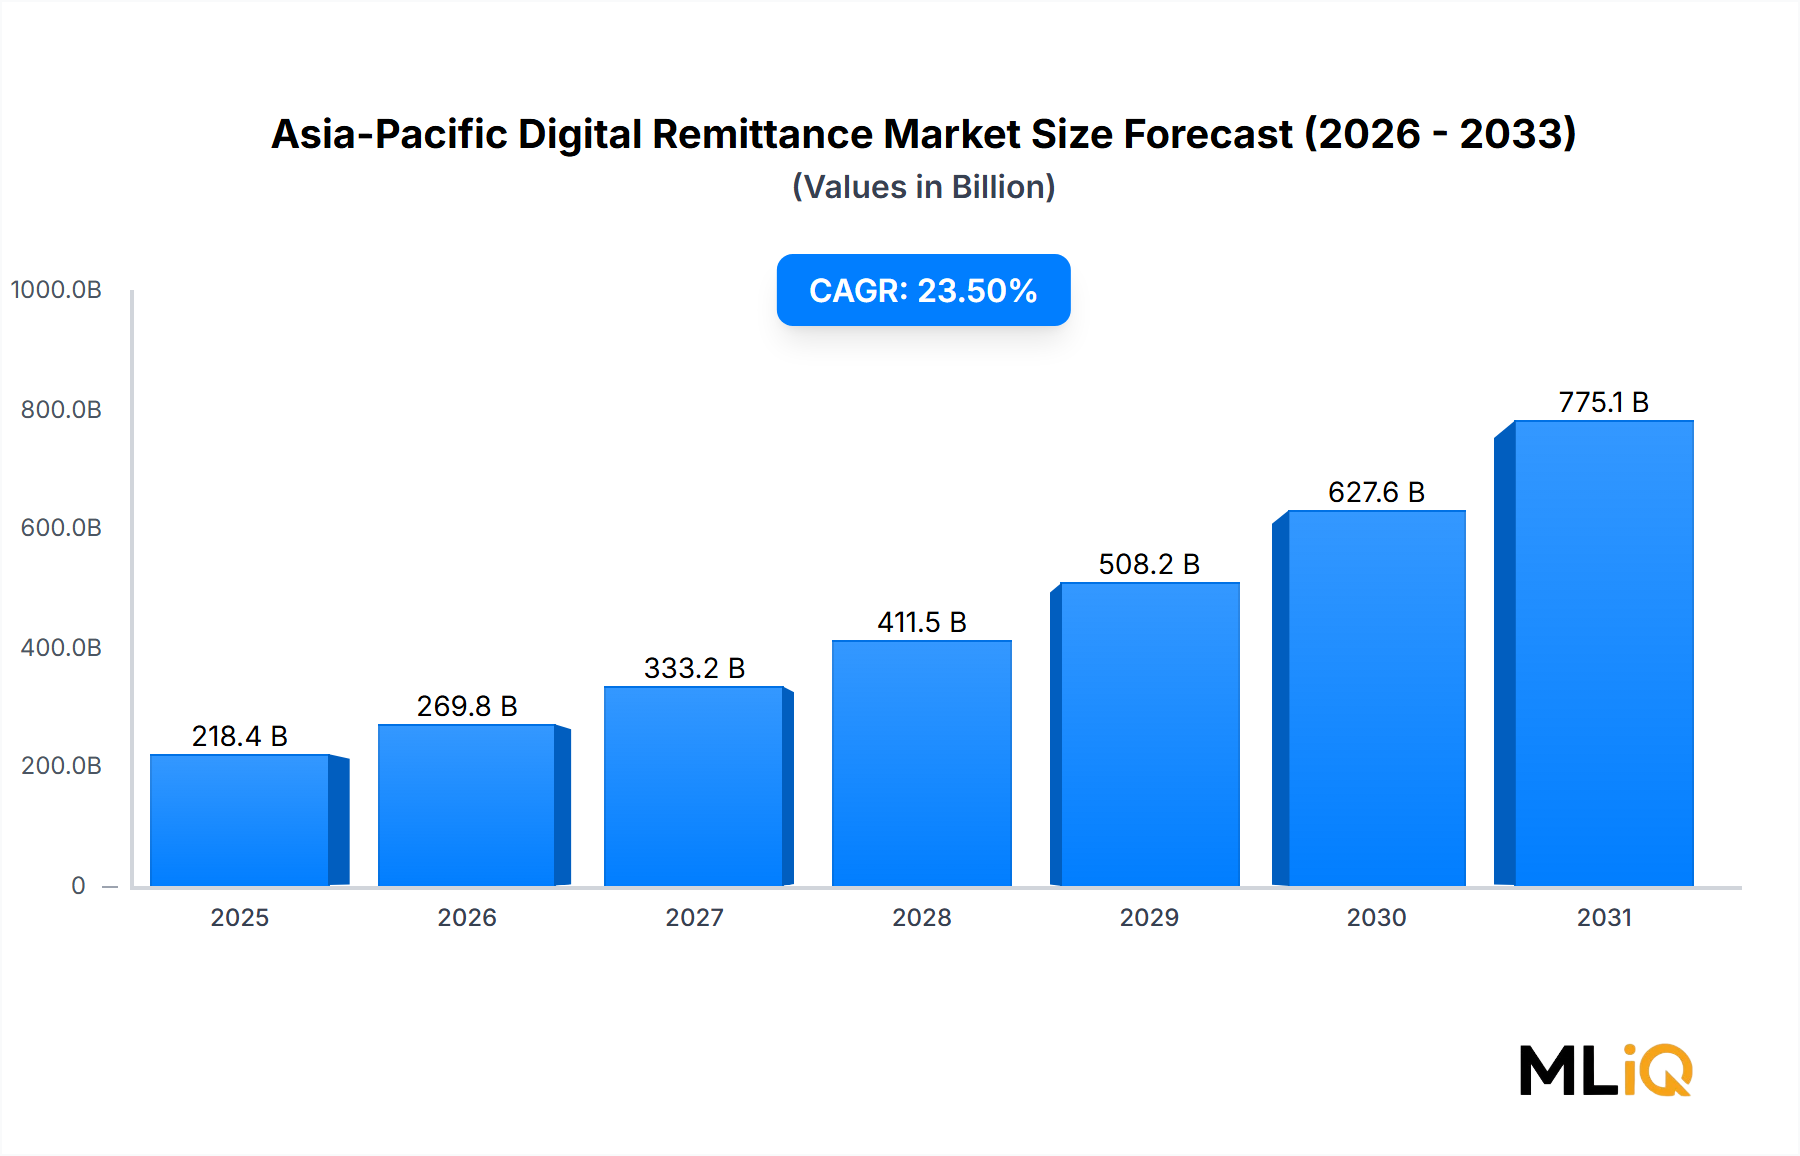
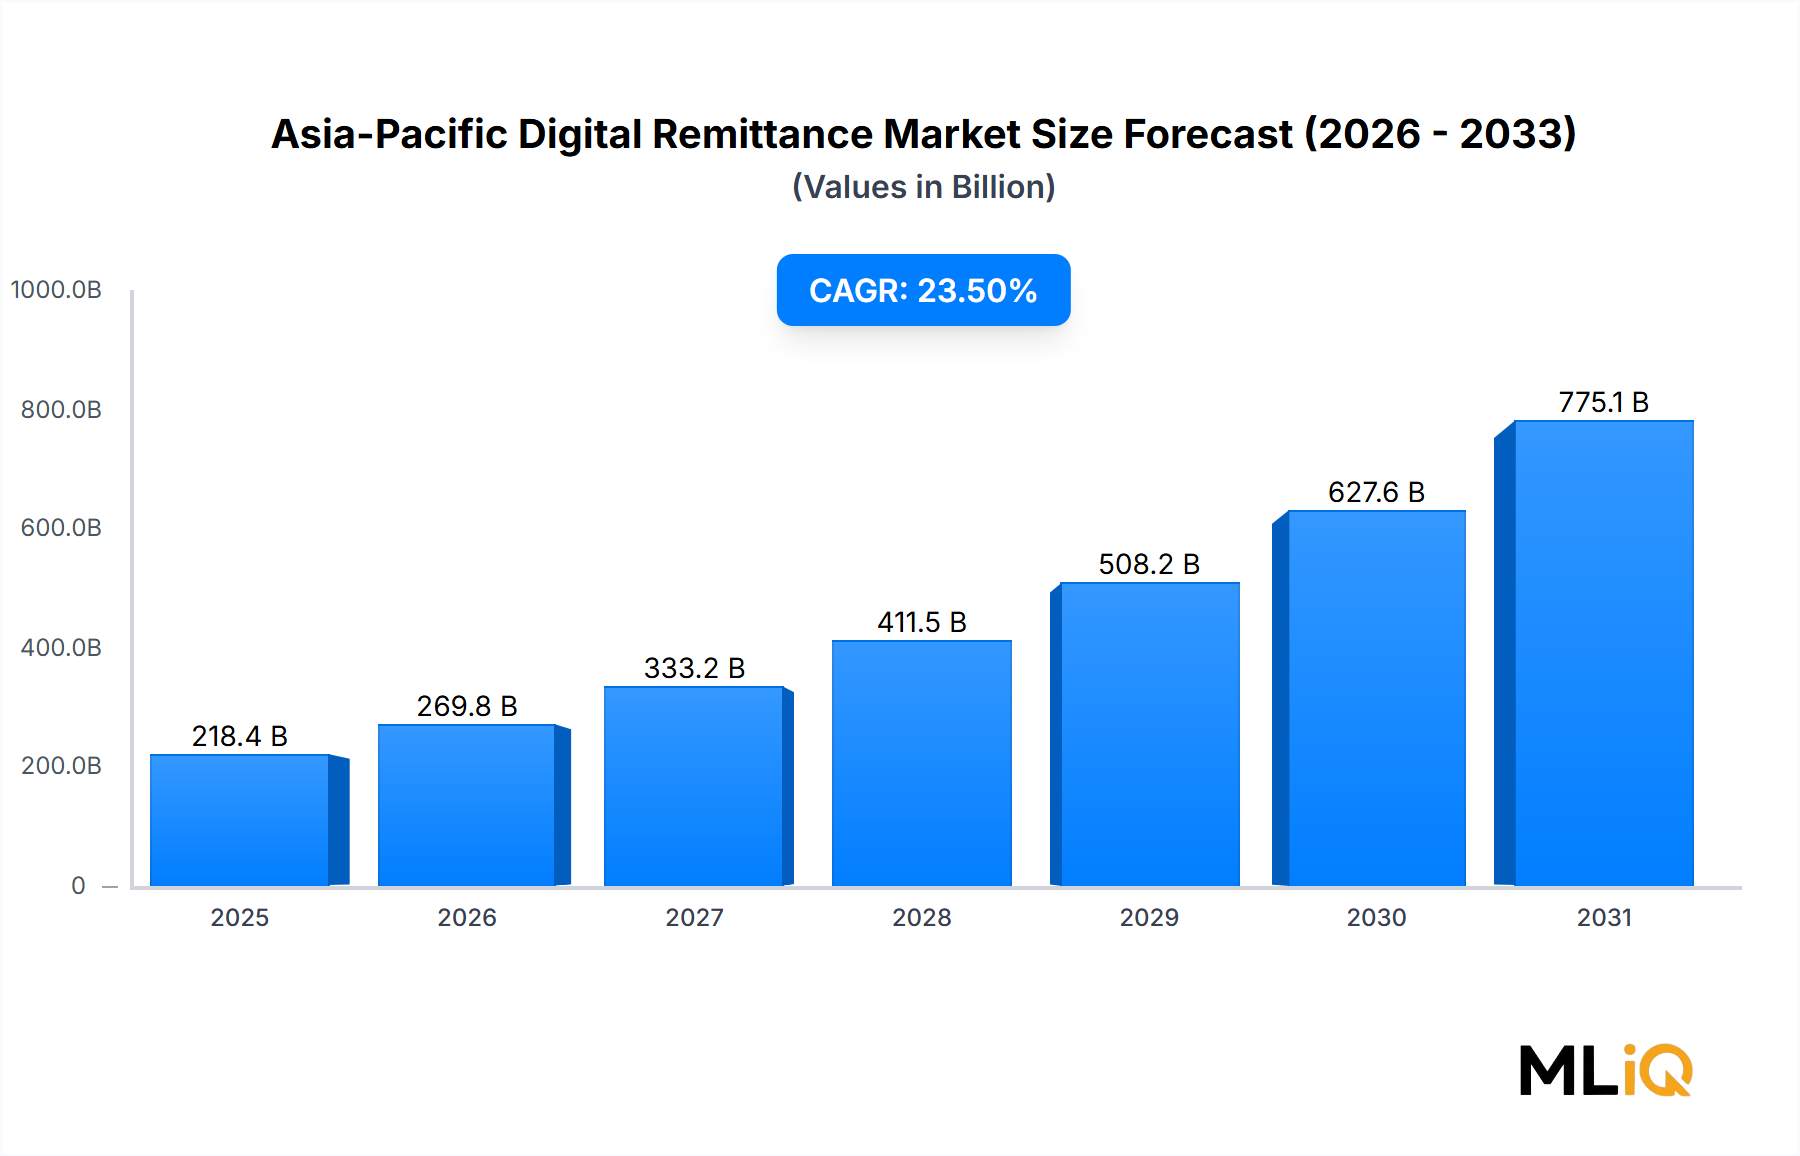
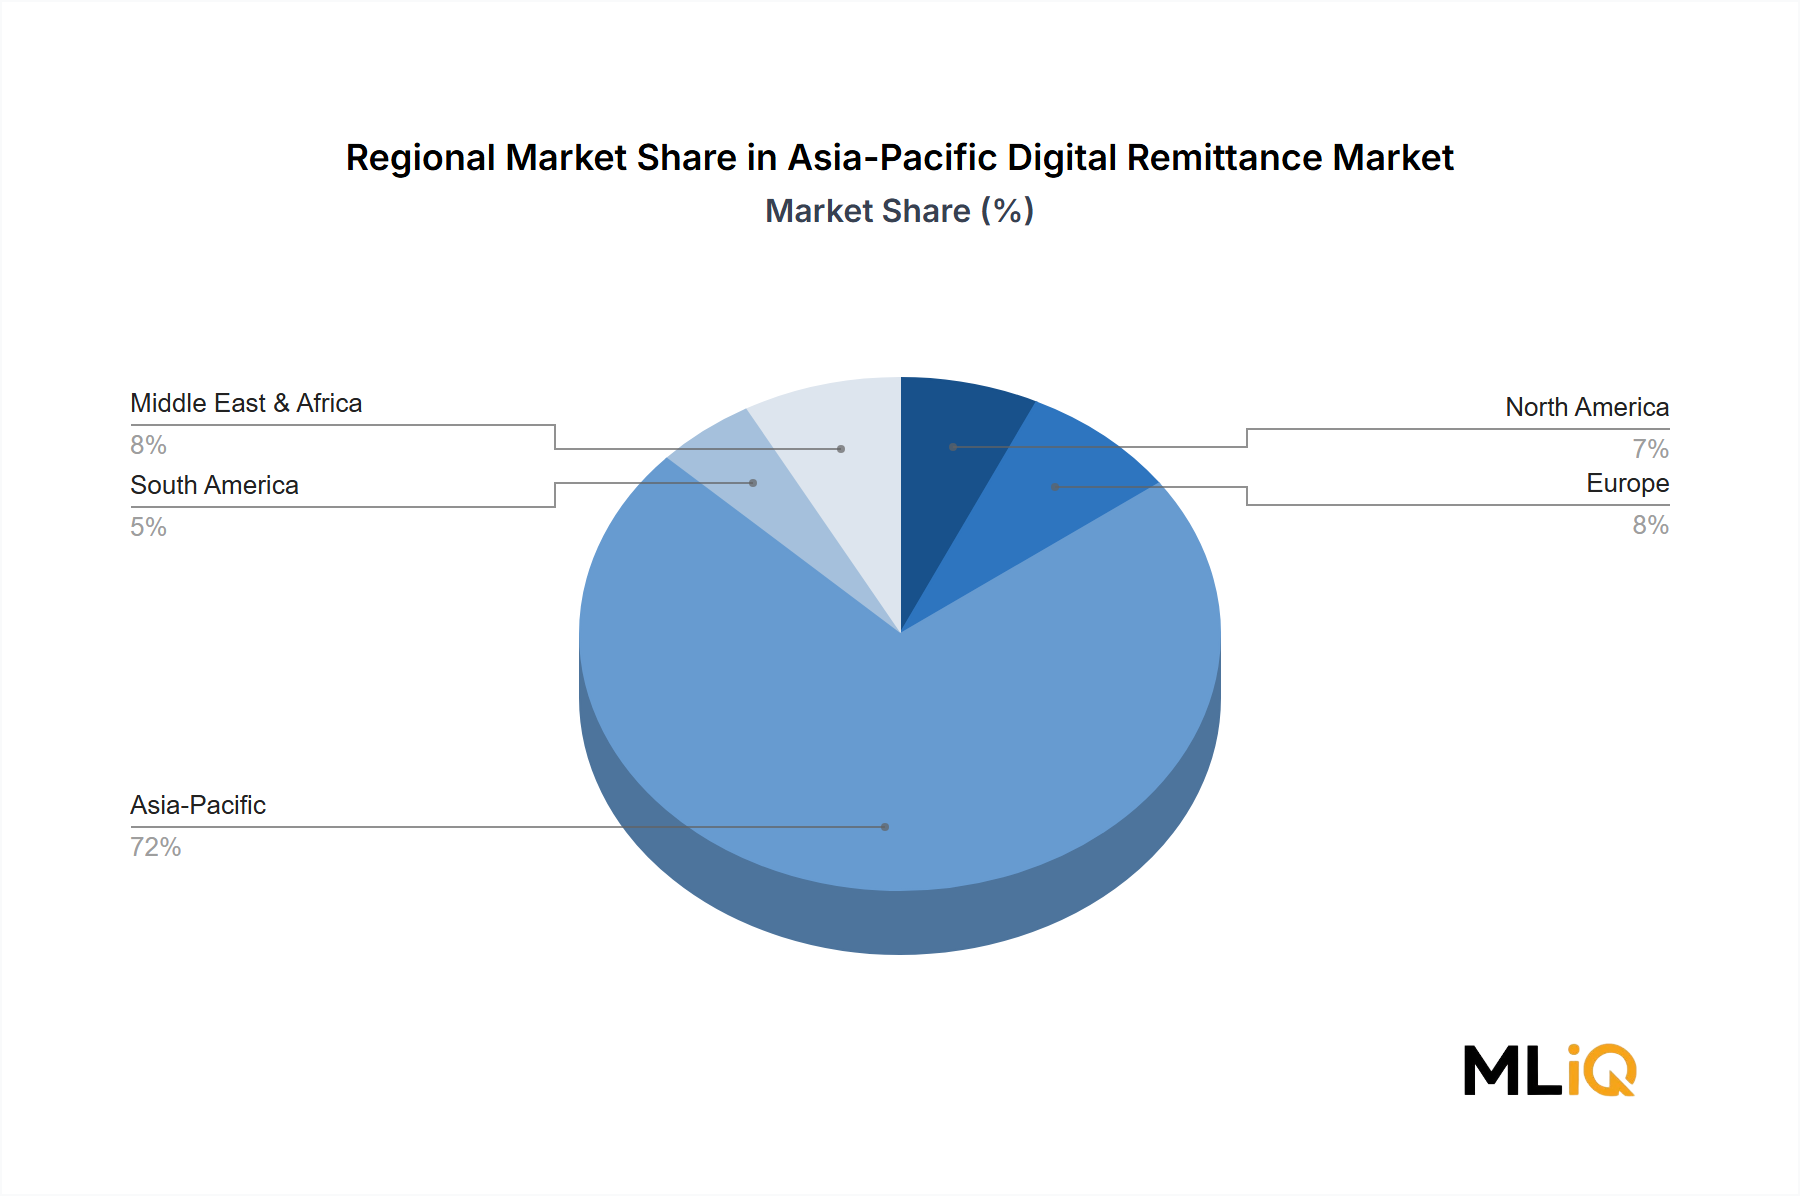
The Asia-Pacific Digital Remittance Market is propelled by a well-defined set of structural drivers and moderated by identifiable constraints that collectively define its risk-reward profile for participants and investors.
Driver 1 — Smartphone and Internet Penetration: Asia-Pacific's smartphone user base exceeded 2.8 billion as of 2024, with mobile internet penetration continuing to deepen across previously underserved markets such as Myanmar, Cambodia, and Papua New Guinea. This infrastructure expansion directly expands the total addressable market for app-based remittance services.
Driver 2 — Declining Transaction Costs via Digital Channels: The global average cost of sending $200 via digital channels has declined to approximately 4.5%, compared to over 7% for cash-agent-based models. On high-volume APAC corridors, fintech operators are offering fees below 2%, accelerating user migration from traditional channels and driving volume growth.
Driver 3 — Real-Time Payment Rail Development: National and multilateral real-time payment infrastructures — including India's UPI, Thailand's PromptPay, Singapore's PayNow, and their bilateral linkages — are reducing settlement times from days to seconds. These rails support the Cross-Border Payment Market by enabling near-instantaneous credit to beneficiary accounts, improving user satisfaction and channel stickiness.
Driver 4 — Regulatory Liberalization: Multiple APAC governments have issued new digital payment licenses, sandbox frameworks, and API-sharing mandates that lower barriers to entry and encourage innovation. The MAS in Singapore and the Reserve Bank of India (RBI) have been particularly proactive in shaping a permissive but compliant operating environment.
Constraint 1 — Anti-Money Laundering (AML) and Know Your Customer (KYC) Compliance Costs: Regulatory compliance remains the most significant cost center for digital remittance operators. AML screening, transaction monitoring, and multi-jurisdictional KYC reconciliation can consume 15–25% of an operator's operational budget, disproportionately impacting smaller, corridor-focused players.
Constraint 2 — Foreign Exchange Volatility: Currency depreciation events in markets such as Sri Lanka (2022), Pakistan (2023), and Bangladesh create adverse economic conditions for remittance-dependent households and can temporarily suppress digital transfer volumes as senders delay transactions awaiting favorable rates.
Constraint 3 — Interoperability Fragmentation: Despite bilateral RTP linkages, the absence of a unified multilateral payment standard across all ASEAN nations creates operational complexity for operators seeking pan-regional scale, inflating technology integration costs.