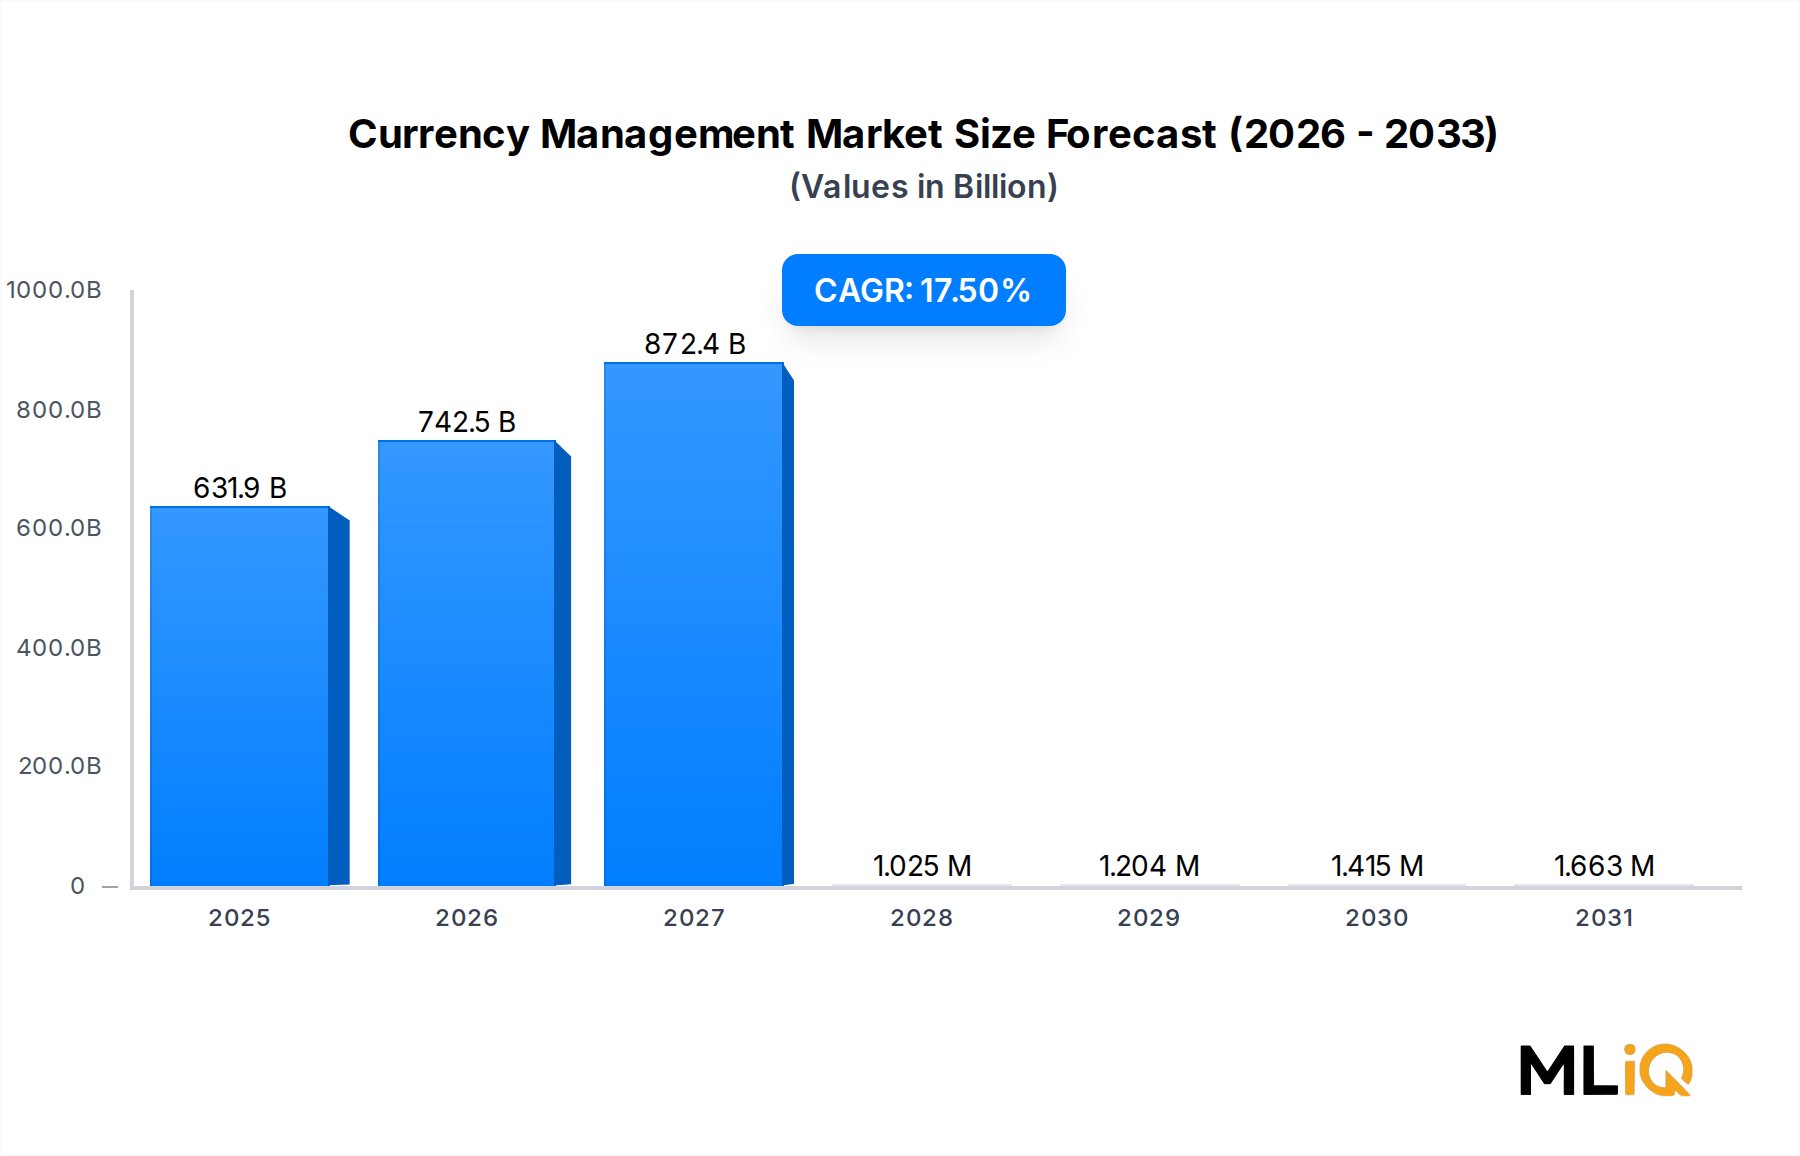
The global Currency Management Market is valued at $631.88 billion as of the base assessment period and is projected to expand at a compound annual growth rate of 17.5% through 2033, reflecting one of the most robust growth trajectories observed across BFSI sub-segments. This acceleration is driven by the confluence of globalization-induced foreign exchange volatility, accelerating cross-border trade volumes, and the rapid institutionalization of automated hedging frameworks among both financial and non-financial corporates.
At its core, the Currency Management Market encompasses a broad spectrum of services and technologies designed to minimize foreign exchange exposure, optimize currency conversion, and provide systematic overlay strategies for institutional portfolios. The market's expansion is underpinned by mounting pressure on multinational corporations, sovereign wealth funds, and asset managers to systematically manage FX risk rather than treat it as a residual concern.
Macroeconomic tailwinds are significant. The post-2020 era of synchronized monetary policy divergence — most notably the Federal Reserve's rate hiking cycle initiated in 2022 and the subsequent divergence between G10 central banks through 2024 — has created structurally elevated FX volatility. The JPMorgan Global FX Volatility Index registered multi-decade highs during 2022–2023, catalyzing renewed corporate demand for currency overlay programs and benchmark hedging mandates.
On the technology front, the proliferation of AI-driven currency analytics, real-time FX pricing APIs, and cloud-native treasury platforms is transforming the delivery model for currency management services. Platform-based solutions from specialized providers are displacing legacy bank-intermediated services among mid-market corporates, opening addressable market segments that were previously inaccessible to specialist currency managers.
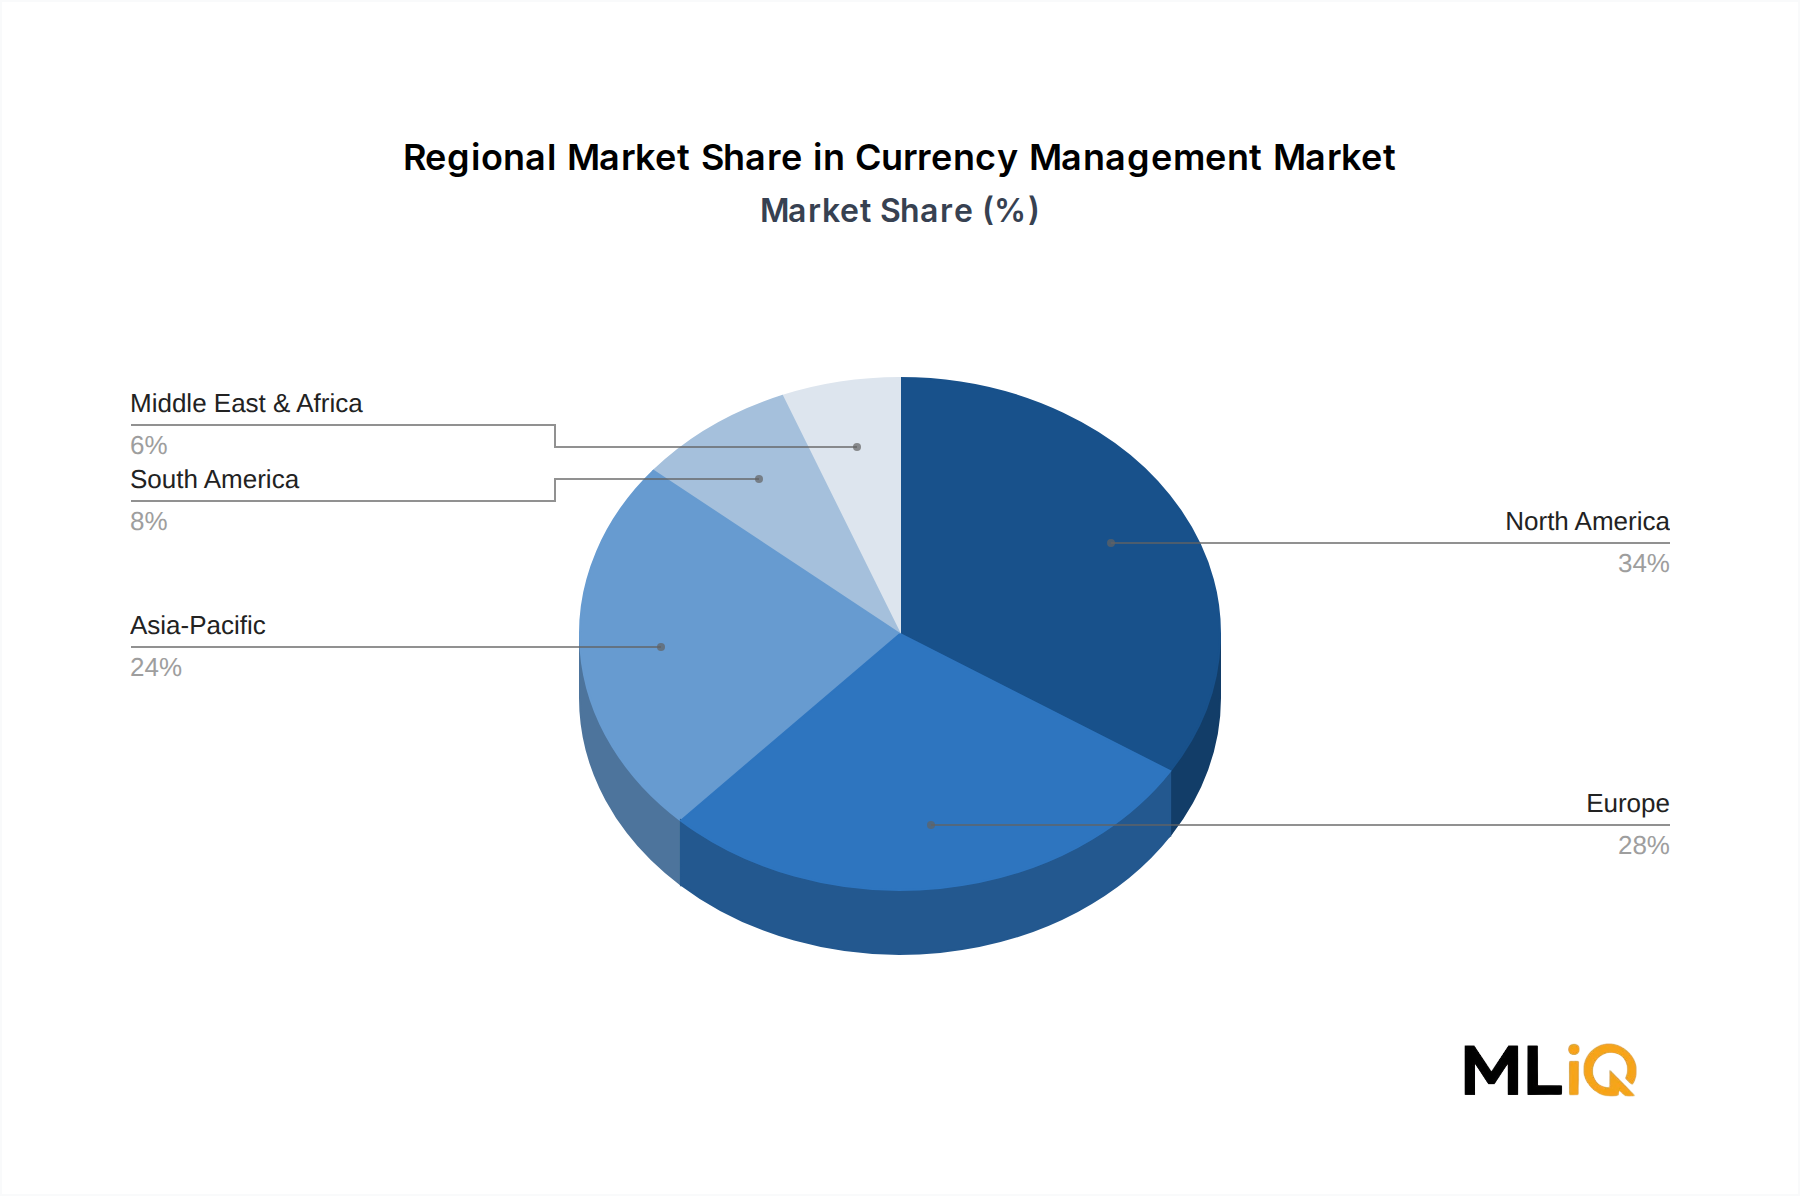
Geographically, North America and Europe jointly account for the dominant revenue share, but Asia Pacific is emerging as the fastest-growing region owing to expanding capital market liberalization, rising outbound foreign direct investment from China and India, and increasing adoption of FX hedging by regional corporates. The Middle East and Africa, while a smaller absolute contributor, is gaining momentum driven by sovereign wealth fund mandates and GCC economic diversification strategies.
Looking forward to 2033, the Currency Management Market is expected to benefit from the institutionalization of digital asset FX corridors, regulatory requirements for systematic FX risk disclosure under frameworks such as IFRS 7 and ASC 815, and the deepening integration of currency management modules within enterprise resource planning ecosystems. The market's 17.5% CAGR is not merely a function of volume growth but reflects a structural re-pricing of currency risk management as a core financial discipline rather than an optional overlay.