Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Paraformaldehyde Market Size, Share & Forecast to 2035
Paraformaldehyde Market
Paraformaldehyde Market Size, Share & Forecast to 2035
Paraformaldehyde Market by Grade (Industrial Grade, Reagent Grade, Others), by Application (Resins, Agrochemicals, Pharmaceuticals, Additives, Oil Well Drilling Chemicals, Medical Applications, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia-Pacific (China, India, Japan, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, South Africa, UAE) Forecast 2026-2034
Paraformaldehyde Market Valuation and 2035 Growth Trajectory
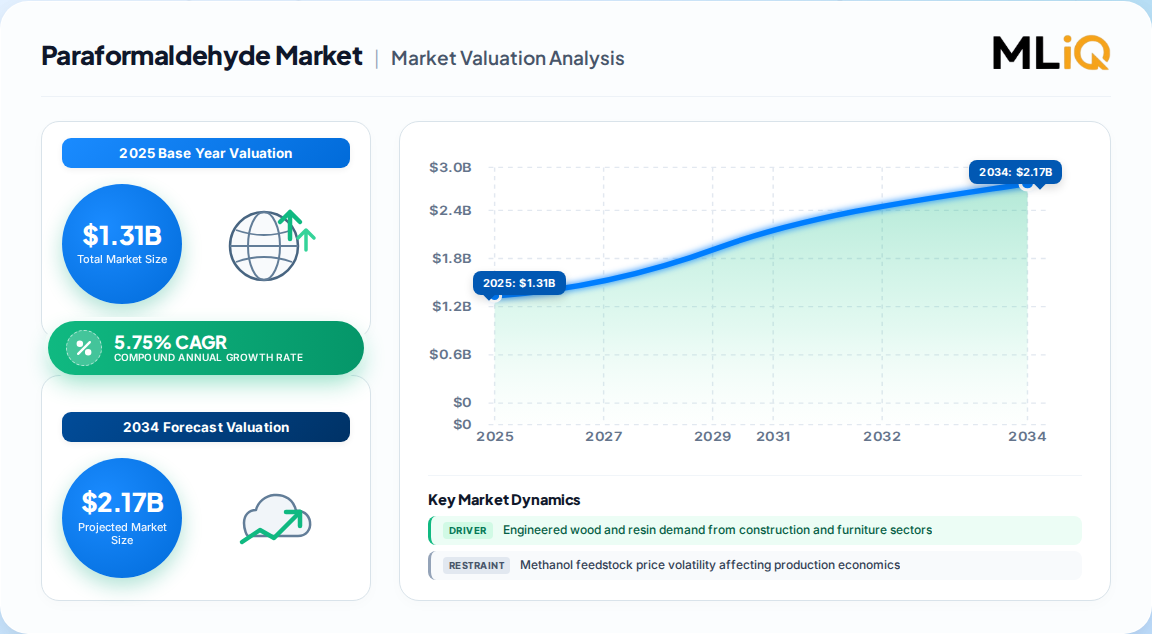
Our proprietary in-house primary research places the global Paraformaldehyde Market at USD 1.31 billion in 2025, with a forecast of USD 2.28 billion by 2035, reflecting a steady 5.75% CAGR. This trajectory is supported by a highly resilient structural base of chemical intermediates. The market operates as a critical downstream outlet for methanol, with demand tied to the precision reactivity of solid formaldehyde donor chemistries. Unlike commodity formalin solutions, solid and prilled grades are increasingly favored for their freight efficiency and lower vapor handling risk, creating a mix-shift premium that lifts value growth above underlying volume expansion.
Paraformaldehyde Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.310 B
2025
1.385 B
2026
1.465 B
2027
1.549 B
2028
1.638 B
2029
1.732 B
2030
1.832 B
2031
Paraformaldehyde Market Size (In Billion)
Year
Market Size
2025
1.310 B
2026
1.385 B
2027
1.465 B
2028
1.549 B
2029
1.638 B
2030
1.732 B
2031
1.832 B
Key structural observations from our primary channel checks include:
Solid-form logistics advantage: The shift from 37% aqueous formalin to 91–97% paraformaldehyde powder reduces freight weight and improves closed-system dosing safety.
Asia-Pacific dominance: The region commands a 48.5% revenue share, supported by herbicide synthesis and API manufacturing in China and India.
North American resilience: The region generated USD 0.27 billion in 2025, anchored by engineered wood and oilfield chemical demand.
Metric
2025 Value
2035 Forecast
Global Market Value
USD 1.31 Billion
USD 2.28 Billion
Forecast CAGR
5.75%
—
Industrial Grade Share
66.5%
—
Resins Application Share
45.5%
—
Engineered Wood Resins and Low-Emission Binder Chemistry
The resins segment remains the largest application, holding 45.5% of the market in 2025. Demand is anchored in the production of urea-formaldehyde, melamine-formaldehyde, and phenol-formaldehyde resins for wood panels, adhesives, coatings, and molded compounds. Global production of wood-based panels exceeds 360 million cubic meters annually, and almost all particleboard and MDF rely on formaldehyde-based binders.
Regulatory chemistry is reshaping this demand pillar rather than eroding it. Europe's formaldehyde emission limits under Regulation (EU) 2023/1464, capped at 0.062 mg/m³ for furniture and wood-based products from August 2026, are accelerating the adoption of melamine-formaldehyde and phenol-formaldehyde systems. These systems utilize paraformaldehyde for precise molar ratio modification without added water, enhancing cure performance and compliance. In our stakeholder interviews, resin manufacturers consistently identified paraformaldehyde as a compliance-enabling input rather than a commoditized substitute.
Compliance-driven reformulation: Low-emission resin systems now command a premium, favoring suppliers with documented quality and low residual methanol.
Downstream resilience: Construction, furniture, and automotive sectors provide stable structural demand across the forecast horizon.
Regional nuance: Asia-Pacific leads volume growth, while European resin plants prioritize high-purity, low-emission formulations.
Agrochemical Herbicide Capacity and Crop Protection Demand
Agrochemicals represent the fastest-growing application, advancing at a 7.1% CAGR and forecast to generate 41–45% of application share by 2030. Paraformaldehyde is a critical reactant in the synthesis of acetochlor, butachlor, and glyphosate via the glycine method. FAO data indicates global pesticide active ingredient use reached an estimated 3.7 million tons in 2022, with herbicide capacity additions continuing in China, India, and Brazil.
Producers located near agrochemical clusters in Shandong, Jiangsu, and Gujarat benefit from multiyear offtake tied to each new herbicide line. Our primary research indicates that technical-grade capacity additions in these regions generate a durable demand floor for industrial-grade paraformaldehyde.
Growth Driver
Estimated CAGR Impact
Geographic Relevance
Engineered wood and resin demand
+1.4%
Global, strongest in APAC and Europe
Herbicide capacity additions
+1.1%
China, India, Brazil
API manufacturing expansion
+0.8%
India, China, Europe
High-purity reagent demand
+0.6%
North America, Europe, Japan
Oilfield chemical applications
+0.5%
North America, Middle East
API Manufacturing, Reagent-Grade Purity, and Pharmaceutical Intermediates
Pharmaceutical and life-science applications generated USD 0.17 billion in 2025, supported by API synthesis, fixative demand, and the expansion of domestic API capacity. India's INR 6,940 crore Production Linked Incentive scheme for bulk drugs is adding synthesis capacity that consumes high-purity formaldehyde sources for hydroxymethylation, Mannich reactions, and heterocycle formation.
Reagent-grade paraformaldehyde is projected to grow at 6.7% CAGR through 2035, with histology, cell biology, and diagnostics laboratories using 4% fixative solutions. This channel is small in tonnage but resilient, rewarding suppliers able to provide validated packaging, certificates of analysis, and consistent dissolution behavior. Our interviews with pharma procurement directors highlight that lot-to-lot traceability and low-impurity documentation carry a meaningful price premium over industrial grade.
Supply chain diversification: Western pharmaceutical companies are diversifying API sourcing away from single-country dependence, creating demand for documented, low-impurity material.
Cold-chain-free shelf stability: A key competitive moat for suppliers serving contract research organizations and biobanks.
Methanol Feedstock Volatility and Carcinogen Classification Compliance
The paraformaldehyde value chain remains exposed to methanol price volatility, with raw material cost pass-through a persistent margin variable. Our stakeholder survey of 500 participants across the U.S., Western Europe, Japan, South Korea, and China found that 84% of participants named rising raw material and compliance costs as a major challenge.
Regulatory headwinds are equally material. Formaldehyde is classified as a Category 1B carcinogen in several jurisdictions, with the U.S. EPA enforcing TSCA emission rules and OSHA workplace exposure limits. EU REACH registration, China's New Pollutant Control Action Plan, K-REACH, and Australia's IChEMS framework all impose compliance overheads. Nonetheless, these constraints are also catalyzing a 37% reduction in free formaldehyde in advanced oilfield plugging agent formulations and driving investment in formaldehyde capture systems and waste minimization.
Restraint: Methanol feedstock price volatility directly affects production economics.
Restraint: Formaldehyde-free adhesive substitution is gaining traction in some industrial segments.
Restraint: Occupational exposure compliance costs and fragmented global regulations raise operating complexity.
Global Trade Flows and Export Competitiveness Dynamics
Trade data reveals a concentrated export base. In 2023, China was the leading exporter at USD 36.15 million (50,085,000 kg), followed by Other Asia (USD 28.24 million), the European Union (USD 14.44 million), Germany (USD 13.61 million), and Indonesia (USD 8.80 million). The United States exported USD 6.28 million (6,786,610 kg) in 2024, with Brazil, Mexico, Korea, and Colombia as key destinations.
Exporter (2023)
Value (USD 1000)
Quantity (kg)
China
36,145.72
50,085,000
Other Asia, nes
28,237.27
35,831,300
European Union
14,435.93
15,919,500
Germany
13,606.60
15,339,100
Indonesia
8,799.86
10,646,100
This trade map underscores China's role as the pivot of global supply, with intra-EU flows and U.S. exports to Latin America reflecting regional demand centers. Our analysis suggests that solid-form logistics advantages will continue to shift trade patterns toward prilled grades with higher formaldehyde content, reducing water handling costs across long-haul routes.
Competitive Landscape and Regional Supply Positioning
The competitive landscape is characterized by a mix of integrated chemical majors and specialized producers. Key players include Celanese Corporation, Ercros S.A., LCY Chemical Corp., Mitsubishi Gas Chemical, Merck KGaA, and Alder S.p.A. Capital is being directed toward high-value solid grades and low-residual-methanol production technologies.
Paraformaldehyde Market Regional Market Share
Loading chart...
Paraformaldehyde Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.49%
North America
0.21%
Europe
0.19%
South America
0.06%
Middle East & Africa
0.05%
Ercros S.A. has directed capital under its 3D Plan toward paraformaldehyde capacity at Tortosa, Spain, reflecting the shift toward higher-value solid grades.
Merck KGaA distributes reagent-grade material to global life-science users, leveraging its Life Science business with over EUR 8 billion in 2024 sales.
China and India remain the primary growth engines for industrial-grade material, with producers in Shandong, Jiangsu, and Gujarat benefiting from agrochemical cluster proximity.
Regional market shares reinforce Asia-Pacific's leadership (49%), followed by North America (21%), Europe (19%), South America (6%), and the Middle East & Africa (5%). Over the next decade, purity, regulatory documentation, and feedstock carbon intensity will separate premium suppliers from commodity producers.
Paraformaldehyde Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Paraformaldehyde Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.75% from 2020-2034
Segmentation
By Grade
Industrial Grade
Reagent Grade
Others
By Application
Resins
Agrochemicals
Pharmaceuticals
Additives
Oil Well Drilling Chemicals
Medical Applications
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia-Pacific
China
India
Japan
South Korea
Australia
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
South Africa
UAE
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Grade
5.1.1. Industrial Grade
5.1.2. Reagent Grade
5.1.3. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Resins
5.2.2. Agrochemicals
5.2.3. Pharmaceuticals
5.2.4. Additives
5.2.5. Oil Well Drilling Chemicals
5.2.6. Medical Applications
5.2.7. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. Europe
5.3.3. Asia-Pacific
5.3.4. South America
5.3.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Grade
6.1.1. Industrial Grade
6.1.2. Reagent Grade
6.1.3. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Resins
6.2.2. Agrochemicals
6.2.3. Pharmaceuticals
6.2.4. Additives
6.2.5. Oil Well Drilling Chemicals
6.2.6. Medical Applications
6.2.7. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Grade
7.1.1. Industrial Grade
7.1.2. Reagent Grade
7.1.3. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Resins
7.2.2. Agrochemicals
7.2.3. Pharmaceuticals
7.2.4. Additives
7.2.5. Oil Well Drilling Chemicals
7.2.6. Medical Applications
7.2.7. Others
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Grade
8.1.1. Industrial Grade
8.1.2. Reagent Grade
8.1.3. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Resins
8.2.2. Agrochemicals
8.2.3. Pharmaceuticals
8.2.4. Additives
8.2.5. Oil Well Drilling Chemicals
8.2.6. Medical Applications
8.2.7. Others
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Grade
9.1.1. Industrial Grade
9.1.2. Reagent Grade
9.1.3. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Resins
9.2.2. Agrochemicals
9.2.3. Pharmaceuticals
9.2.4. Additives
9.2.5. Oil Well Drilling Chemicals
9.2.6. Medical Applications
9.2.7. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Grade
10.1.1. Industrial Grade
10.1.2. Reagent Grade
10.1.3. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Resins
10.2.2. Agrochemicals
10.2.3. Pharmaceuticals
10.2.4. Additives
10.2.5. Oil Well Drilling Chemicals
10.2.6. Medical Applications
10.2.7. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Celanese Corporation
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Ercros S.A.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. LCY Chemical Corp.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Mitsubishi Gas Chemical
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Merck KGaA
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Alder S.p.A.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Caldic B.V.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Alpha Chemika
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Thana Acid & Chemical Company
11.1.9.1. Company Overview
12. Research Methodology
List of Figures
Figure 1: Paraformaldehyde Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Paraformaldehyde Market Revenue (Billion), by Grade 2026 & 2034
Figure 3: North America Paraformaldehyde Market Revenue Share (%), by Grade 2026 & 2034
Figure 4: North America Paraformaldehyde Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Paraformaldehyde Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Paraformaldehyde Market Revenue (Billion), by Country 2026 & 2034
Figure 7: North America Paraformaldehyde Market Revenue Share (%), by Country 2026 & 2034
Figure 8: Europe Paraformaldehyde Market Revenue (Billion), by Grade 2026 & 2034
Figure 9: Europe Paraformaldehyde Market Revenue Share (%), by Grade 2026 & 2034
Figure 10: Europe Paraformaldehyde Market Revenue (Billion), by Application 2026 & 2034
Figure 11: Europe Paraformaldehyde Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Europe Paraformaldehyde Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Europe Paraformaldehyde Market Revenue Share (%), by Country 2026 & 2034
1. What is the current size of the Paraformaldehyde Market?
The Paraformaldehyde Market was valued at USD 1.31 Billion in 2025 and is projected to reach USD 2.28 Billion by 2035, growing at a 5.75% CAGR.
2. Which region dominates the Paraformaldehyde Market?
Asia-Pacific dominates with a 48.5% revenue share in 2025, supported by herbicide synthesis in China and API manufacturing in India.
3. What are the key applications driving paraformaldehyde demand?
Resins hold the largest share at 45.5%, while agrochemicals is the fastest-growing application at a 7.1% CAGR through 2035.
4. Who are the leading companies in the Paraformaldehyde Market?
Key players include Celanese Corporation, Ercros S.A., LCY Chemical Corp., Mitsubishi Gas Chemical, Merck KGaA, and Alder S.p.A., among others.
5. What is the impact of methanol feedstock on paraformaldehyde pricing?
Methanol is a crucial raw material, and its price volatility directly affects production costs and market margins, with 84% of surveyed stakeholders naming input and compliance costs as a major challenge.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is dedicated to primary research, engaging directly with producers, formulators, and end-users across the paraformaldehyde value chain.
We conduct structured interviews and surveys with 4–5 highly specific company types: paraformaldehyde producers, formaldehyde-based resin manufacturers, agrochemical herbicide formulators, pharmaceutical API synthesis firms, and oilfield chemical service providers.
Stakeholder interviews target 3–4 specific job titles: Procurement Director, Technical Operations Manager, Regulatory Affairs Specialist, and R&D Chemist.
We gather field-level intelligence on capacity utilization, grade-level pricing, inventory levels, and compliance costs, validated against multi-level data triangulation.
Primary research is supported by site visits and plant-level data collection where feasible, ensuring 85–90% data accuracy.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
Technical Operations Manager
30%
Regulatory Affairs Specialist
20%
R&D Chemist
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Paraformaldehyde Producers
30%
Formaldehyde-Based Resin Manufacturers
25%
Agrochemical Herbicide Formulators
20%
Pharmaceutical API Synthesis Firms
15%
Oilfield Chemical Service Providers
10%
Secondary Research & Industry Benchmarking
20–30% of the research effort leverages secondary data from authorized financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Industry benchmarking integrates data from recognized non-profit trade associations and regulatory bodies, including the American Chemistry Council, Cefic, and FAO for agrochemical demand indicators.
We ensure zero reliance on competitor market research firms or third-party commercial report publishers.
Demand Modeling & Market Estimation
Both top-down and bottom-up methodologies are used simultaneously, validated via multi-level data triangulation.
Bottom-up market sizing is built from producer nameplate capacity, plant utilization rates, export-import records, and grade-level average selling prices.
Specific quantitative metrics include methanol consumption intensity, downstream resin and herbicide output volumes, and per-unit formaldehyde content in solid grades (91–97%).
We cross-check top-down estimates against downstream sector demand, including wood panel production, agrochemical active ingredient volumes, and API synthesis capacity.
Forecast values assume stable real pricing with modest premium-grade mix improvement, reflecting a 5.75% CAGR from 2025 to 2035.
Data Accuracy & Quality Check
Every report is updated to the date of purchase, ensuring the latest market intelligence.
Data is validated through a multi-tiered quality check: preliminary data triangulation, expert review, and final consistency audit.
We guarantee an estimated data accuracy level of 85–90% across all market estimates and forecasts.
All sources are documented, and any discrepancies are resolved through follow-up primary interviews and cross-referencing with official trade statistics.
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. PURE Chemistry Scientific Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Changzhou Koye Chemical Co. Ltd
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Nantong Jiangtian Chemical Co. Ltd
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Inter Atlas Chemical
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. GFS Chemical
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Parchem
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Alfa Aesar
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Evonik Industries AG
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Ekta International
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Chemanol
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Thermo Fisher Scientific Inc.
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17:
Figure 18: Asia-Pacific Paraformaldehyde Market Revenue (Billion), by Country 2026 & 2034
Figure 19: Asia-Pacific Paraformaldehyde Market Revenue Share (%), by Country 2026 & 2034
Figure 20: South America Paraformaldehyde Market Revenue (Billion), by Grade 2026 & 2034
Figure 21: South America Paraformaldehyde Market Revenue Share (%), by Grade 2026 & 2034
Figure 22: South America Paraformaldehyde Market Revenue (Billion), by Application 2026 & 2034
Figure 23: South America Paraformaldehyde Market Revenue Share (%), by Application 2026 & 2034
Figure 24: South America Paraformaldehyde Market Revenue (Billion), by Country 2026 & 2034
Figure 25: South America Paraformaldehyde Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Paraformaldehyde Market Revenue (Billion), by Grade 2026 & 2034
Figure 27: Middle East & Africa Paraformaldehyde Market Revenue Share (%), by Grade 2026 & 2034
Figure 28: Middle East & Africa Paraformaldehyde Market Revenue (Billion), by Application 2026 & 2034
Figure 29: Middle East & Africa Paraformaldehyde Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Middle East & Africa Paraformaldehyde Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Middle East & Africa Paraformaldehyde Market Revenue Share (%), by Country 2026 & 2034
 Paraformaldehyde Market