Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Aerospace Materials Market Size, Share & Forecast to 2035
Aerospace Materials Market
Aerospace Materials Market Size, Share & Forecast to 2035
Aerospace Materials Market by Material Type (Advanced Aluminum Alloys, Advanced Composites, Titanium Alloys, Ceramic-Matrix Composites, Superalloys, Advanced Steel Alloys, Advanced Adhesives), by Structure Class (Structural, Non-Structural, Functional), by Aircraft Type (Commercial Aircraft(Passenger Aircraft, Transport Aircraft, Space Aircraft), Military Aircraft, General Aviation, Helicopters, Spacecraft, UAVs), by Application System (Airframe Structures, Engine Components, Interior Systems, MRO and Aftermarket Replacement, Nacelles, Landing Gear and Braking), by Manufacturing Process (Conventional Manufacturing, Additive Manufacturing, Hybrid Processes), by End Use (Private Sector, Public Sector), by North America (USA, Canada, Mexico), by Europe (Germany, France, Italy, Spain, UK, Poland, Russia, Netherlands, Sweden, Norway, Switzerland, Ireland, Denmark), by Asia-Pacific (China, India, Japan, Australia, South Korea, Thailand, Singapore, Vietnam, Malaysia, Indonesia, Philippines), by South America (Brazil, Argentina, Colombia, Chile, Peru), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Egypt, Israel, Kuwait, Oman, Bahrain) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 521
Aerospace Materials Market Valuation and 2035 Outlook
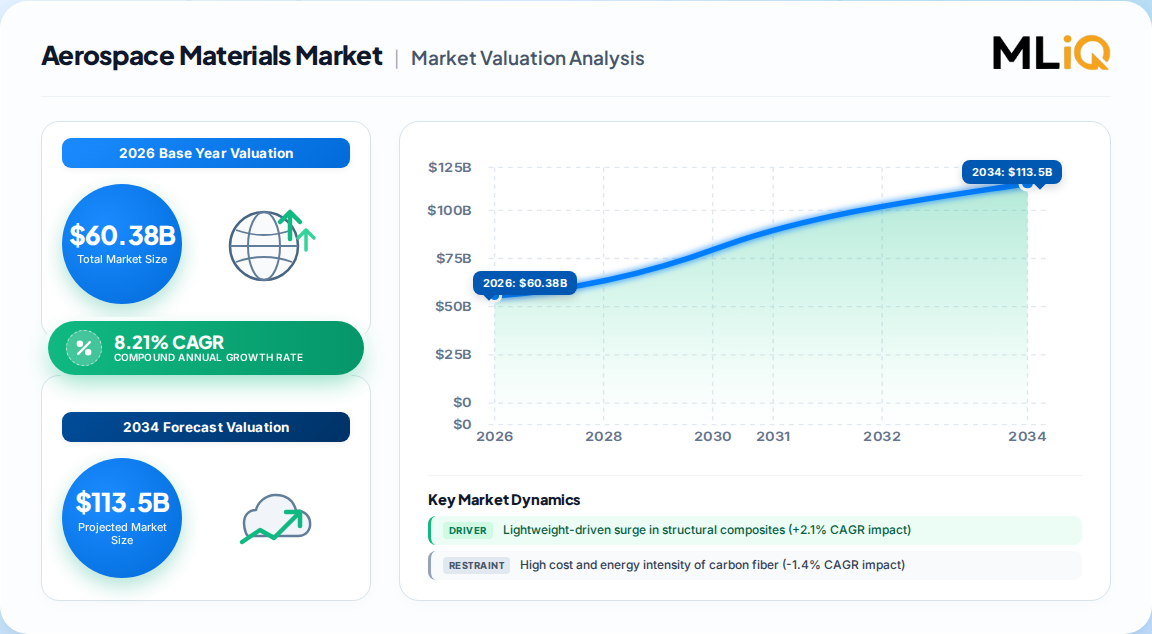
Our proprietary supply-side and demand-side triangulation places the global Aerospace Materials Market at USD 60.38 billion in 2026, expanding to USD 89.58 billion by 2031 at a CAGR of 8.21%. Alternative scenario bands from our regional panel data point to a longer-horizon ceiling of USD 7,202.9 million-equivalent growth in advanced composite sub-tiers by 2035 under accelerated space-launch and narrowbody re-engining conditions.
Aerospace Materials Market Size (In Billion)
100.0B
80.0B
60.0B
40.0B
20.0B
0
55.80 B
2025
60.38 B
2026
65.34 B
2027
70.70 B
2028
76.51 B
2029
82.79 B
2030
89.58 B
2031
Aerospace Materials Market Size (In Billion)
Year
Market Size
2025
55.80 B
2026
60.38 B
2027
65.34 B
2028
70.70 B
2029
76.51 B
2030
82.79 B
2031
89.58 B
Scope of Our Primary Assessment
Definitional boundary: high-performance metallic and non-metallic materials engineered for extreme mechanical, thermal, chemical and fatigue loads across civil, defense and space platforms.
Certification and traceability requirements elevate technical and economic value versus conventional industrial grades.
Our bottom-up build tracks certified material tons shipped and reconciles against OEM build-rate schedules.
Metric
2025 (Actual)
2026 (Base)
2031 (Forecast)
Market value
USD 55.80 Billion
USD 60.38 Billion
USD 89.58 Billion
Implied CAGR
—
8.21%
8.21%
Structural materials share
85.04%
~84.8%
~84.2%
Structural Composite Penetration in Twin-Aisle Airframes
Composite content surpassed 50% by structural weight in leading twin-aisle programs in 2025, unlocking roughly 20% operating-weight reduction and up to 15% lower fuel consumption over a 20-year life cycle.
Cost-sensitive narrowbody programs are raising composite ratios — the C919 targets 25% in its next block upgrade.
Fiber-placement lines cut labor hours by approximately 35%, compressing unit economics for high-rate production.
Aerospace-grade polyacrylonitrile precursor bottlenecks remain the single largest pacing constraint on substitution velocity.
Regional-jet and turboprop platforms stay predominantly aluminum, preserving a bifurcated material landscape through 2031.
Space-Launch Ecosystem Demands Superalloys and Carbon-Carbon
Annual orbital launches tripled between 2020 and 2025. Reusable first stages fly up to 15 cycles, demanding alloys that survive 1,650°C re-entry temperatures.
Space-vehicle demand contributes over USD 15 billion in incremental opportunity by 2031.
Space vehicles represent the fastest-growing aircraft-type demand vector at an 11.08% CAGR.
Satellite constellations raise material intensity per kilogram through radiation-hardened panels and high-frequency antenna substrates.
Qualification cycles compress as launch operators iterate hardware every 18–24 months.
MRO and Aftermarket Replacement Growth Vector
Airframe structures held the largest application-system share at 34.47% in 2025, but maintenance, repair and aftermarket replacement is the fastest-growing system at a 10.86% CAGR.
Aging fleets in North America and Europe sustain consumable alloy and composite patch demand.
Additive manufacturing slashes lead times from one year to six weeks for certified replacement hardware.
Buy-to-fly ratios fall from 20:1 in machined titanium toward near parity, freeing working capital for operators.
The FAA Advisory Circular 33.15-3, issued in 2025, trims certification cycles for established alloys to roughly three years.
Additive Manufacturing and Hybrid Process Adoption
Conventional manufacturing retains dominance, anchored by established machining routes for aluminum and titanium. Additive manufacturing is the fastest-growing process tier.
Laser-sintered fuel nozzles and 3D-printed landing-gear fittings now hold FAA and EASA approval for safety-critical use.
Hybrid processes gain traction in prototyping and small-batch production.
Build-size limits and surface-finish constraints confine current adoption mostly to engines and secondary structures.
Powder-bed fusion lines at Safran, Honeywell and Rolls-Royce support hundreds of parts per engine.
Titanium Alloys and Advanced Aluminum Alloy Substitution Dynamics
Advanced aluminum alloys remain expected to dominate through 2031 on scalability and repairability for high-rate aircraft production. Titanium alloys are the fastest-growing metallic subsegment.
Ceramic-matrix composites deliver a 1% fuel-burn advantage that compounds across thousands of engines.
Circular-economy mandates add a further 0.9% CAGR uplift, concentrated in Europe and North America.
Regional Supply-Chain Localization and Trade Flows
Asia-Pacific accounted for 53.65% of 2025 share and grows at a 9.24% CAGR; North America retains over 35% of global value with the deepest R&D ecosystem. OEMs are localizing supply chains to hedge tariff exposure.
Aerospace Materials Market Regional Market Share
Loading chart...
Aerospace Materials Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.22%
Asia-Pacific
0.31%
South America
0.06%
Middle East & Africa
0.06%
India's production-linked incentives and China's industrial subsidies have expanded domestic aerospace material capacity.
The EU Carbon Border Adjustment Mechanism raises cost on carbon-intensive metals, accelerating composite substitution in Europe.
Strategic-metal supply-chain exposure acts as a 1.1% CAGR drag across Europe and North America.
High cost and energy intensity of carbon fiber imposes a 1.4% CAGR restraint, most acute in Asia-Pacific near term.
Competitive Landscape and Certification Barriers
Market concentration is assessed as medium, with vertically integrated primes and specialist material houses sharing value.
Toray, Hexcel, Syensqo, Teijin and Mitsubishi Chemical anchor the advanced composite supply tier.
Arconic, Constellium, ATI and Carpenter Technology hold qualified positions in advanced alloys.
Multi-billion-dollar capacity additions announced by Hexcel and Toray target the composite trajectory through 2031.
Lengthy certification timelines remain the principal barrier to new entrant scaling.
1. What is the aerospace materials market size in 2026?
Our primary research values the global Aerospace Materials Market at USD 60.38 billion in 2026, expanding to USD 89.58 billion by 2031 at a CAGR of 8.21%.
2. Which material type dominates the aerospace materials market?
Composite materials hold a 42% share of the market, driven by their high strength-to-weight ratio and corrosion resistance in fuselage and wing structures. Titanium alloys are the fastest-growing metallic subsegment on engine and structural demand.
3. Which region is the fastest-growing aerospace materials market?
Asia-Pacific accounted for 53.65% of 2025 market share and grows at a 9.24% CAGR, supported by manufacturing expansion in China and India. North America retains the largest concentration of R&D and OEM value.
4. What is driving demand for advanced aerospace materials?
Lightweight structural composites contribute a 2.1% CAGR uplift, space-launch ecosystem expansion adds 1.8%, and OEM carbon-neutral roadmaps add 1.5%. Additive-manufactured certified alloys contribute a further 1.3%.
5. What is the fastest-growing application system in aerospace materials?
MRO and aftermarket replacement is the fastest-growing application system at a 10.86% CAGR, while airframe structures remain the largest at 34.47% of 2025 share.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We allocate 70–80% of total research effort to primary research, spanning structured interviews, expert panels and targeted surveys across the aerospace materials value chain.
Company types engaged: qualified alloy and composite material suppliers; Tier-1 aerostructure and engine sub-assembly manufacturers; aircraft OEM procurement and materials engineering functions; additive manufacturing powder and feedstock specialists; MRO and aftermarket parts distributors.
Stakeholder designations interviewed: Chief Materials Engineer, Director of Supply Chain Procurement, Airframe Structures Program Manager, Qualification and Certification Lead.
Every report is updated to the date of purchase, incorporating the latest certification approvals, capacity announcements and tariff developments.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Materials Engineer
30%
Director of Supply Chain Procurement
28%
Airframe Structures Program Manager
24%
Qualification and Certification Lead
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Qualified alloy and composite material suppliers
30%
Tier-1 aerostructure and engine sub-assembly manufacturers
25%
Aircraft OEM procurement and materials engineering functions
20%
Additive manufacturing powder and feedstock specialists
15%
MRO and aftermarket parts distributors
10%
Secondary Research & Industry Benchmarking
20–30% of effort is directed to secondary validation using Bloomberg, Factiva, Hoovers and PitchBook financial databases.
We triangulate against official .gov registries, .org trade association publications and recognized non-profit technical standards bodies; no commercial research portals are used as inputs.
Certified material shipment disclosures, OEM build-rate schedules and airworthiness directive records are cross-referenced for consistency.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies run simultaneously, validated via multi-level data triangulation across material, aircraft type, application system and geography.
Bottom-up quantitative metrics include: certified material tons shipped by material grade; composite content as a percentage of structural weight per platform; OEM narrowbody and widebody build rates; and material spend per kilogram of payload for space launch vehicles.
Segment splits are reconciled against supplier revenue disclosures and qualification records.
Guaranteed estimated data accuracy level of 85–90%.


 Aerospace Materials Market