Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
1-Decene Market by Derivative (Polyalphaolefins, Oxo Alcohols, Linear Alkyl Benzene, Linear Mercaptans, Chlorinated Alpha Olefins, Alkyl Dimethylamine, Di-alkyl Diethylamine), by Grade (Bio-based, Synthetic), by Form (Liquid, Solid), by Application (Poly Alpha Olefin, Polyethylene, Detergent Alcohols, Synthetic Lubricants, Others), by End-user (Food & Beverage, Pharmaceutical, Paints & Dyes, Others), by North America (United States, Canada), by Europe (Germany, United Kingdom, France, Italy, Spain, Russia, NORDIC), by Asia Pacific (China, Japan, India, Indonesia, Malaysia, Australia, South Korea, Singapore), by Latin America (Mexico, Argentina, Brazil), by Middle East & Africa (Saudi Arabia, UAE, Israel, GCC, North Africa, South Africa) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 234
1-Decene Market Valuation and Forecast Trajectory 2027-2036
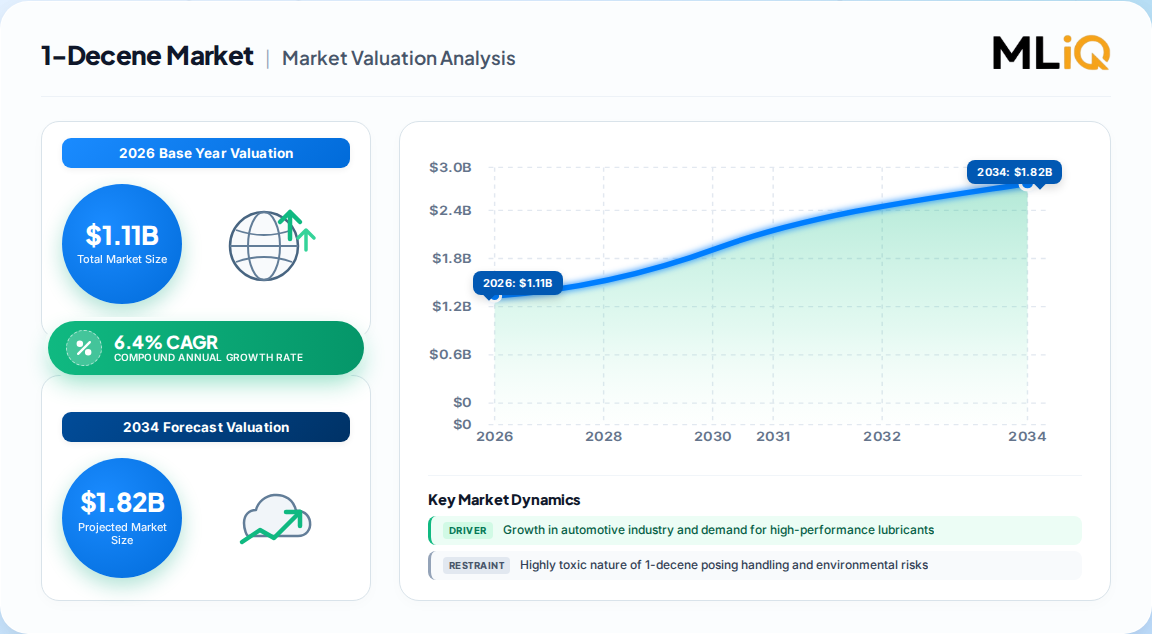
Our proprietary primary research estimates the global 1-Decene Market at USD 1.11 billion in 2026, rising to USD 1.18 billion in 2027 and expanding to USD 2.06 billion by 2036, reflecting a robust 6.4% CAGR across the 2027-2036 forecast window. This trajectory is anchored in sustained downstream demand for polyalphaolefins (PAO) and the accelerating shift toward bio-based alpha-olefin feedstocks.
1-Decene Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.043 B
2025
1.110 B
2026
1.181 B
2027
1.257 B
2028
1.337 B
2029
1.423 B
2030
1.514 B
2031
1-Decene Market Size (In Billion)
Year
Market Size
2025
1.043 B
2026
1.110 B
2027
1.181 B
2028
1.257 B
2029
1.337 B
2030
1.423 B
2031
1.514 B
Metric
2026
2027
2036
CAGR (2027-2036)
Market Size (USD Billion)
1.11
1.18
2.06
6.4%
PAO Derivative Share
~67%
~67%
~67%
—
Europe Revenue Share
~46%
~46%
~45%
—
Base year (2026): USD 1.11 billion
Forecast year (2036): USD 2.06 billion
Incremental growth: ~USD 950 million over ten years
Fastest-growing region: Asia Pacific
Largest regional share: Europe at approximately 46%
Polyalphaolefins as the Dominant Downstream Derivative
Polyalphaolefins (PAO) remain the single most consequential derivative of 1-decene, accounting for roughly 67% of total derivative consumption. PAO is synthesized through the oligomerization of linear alpha-olefins, with C-10 (1-decene) being the preferred feedstock due to its superior viscosity index and oxidative stability.
Polyalphaolefins: ~67% of derivative share; used in gear oils, compressor oils, transmission fluids, and greases.
Oxo Alcohols: Growing in plasticizers, solvents, and acrylates for construction and consumer goods.
Linear Alkyl Benzene (LAB): Driven by biodegradable detergent demand.
Linear Mercaptans: Niche but stable demand in polymer modification.
Chlorinated Alpha Olefins: Rising adoption in flame retardants and plastic additives.
Alkyl Dimethylamine & Di-alkyl Diethylamine: Smaller volumes in water treatment and pharmaceuticals.
Automotive and Industrial Lubricant Demand Dynamics
The automotive and industrial lubrication sectors constitute the primary demand engine for 1-decene. Expanding vehicle production, industrial automation, and wind-energy installations are pushing PAO consumption higher.
The global automotive industry is projected to approach USD 9 trillion by 2030, directly lifting synthetic lubricant demand.
Wind turbine deployment and heavy-duty machinery require premium lubricants with extended service life.
In India, domestic vehicle sales rose 7.3%, signaling robust demand in developing automotive markets.
Stringent fuel-efficiency regulations and the rise of electric-vehicle thermal management systems are creating new PAO consumption vectors.
Food, Pharmaceutical, and Cosmetic End-Use Expansion
Beyond lubricants, 1-decene derivatives are increasingly utilized in food processing, pharmaceutical formulations, and cosmetic ingredients.
Food & Beverage: Hydrogenated poly-1-decene is used as a glazing and polishing agent for dry fruits and sugar confectionery, and as a non-stick coating and anti-foaming agent. Global packaged food sales reached approximately USD 3 trillion in 2019, up from USD 2 trillion in 2016.
Pharmaceutical: Used as a chemical intermediate and processing aid.
Paints & Dyes: Acts as a specialty solvent and additive.
Cosmetics: PVP/Decene Copolymer is listed in the EU CosIng database for binding, emulsion-stabilizing, film-forming, and viscosity-controlling functions under the Cosmetics Regulation.
Upstream Ethylene Feedstock and Bio-Based Supply Transition
The 1-decene value chain is tightly coupled to ethylene availability, as 1-decene is produced exclusively through full-range alpha-olefin distribution via ethylene oligomerization. On-purpose production of C-10 is not commercially feasible, creating structural supply constraints.
Supply Route
Feedstock
Status
Key Characteristic
Petrochemical
Ethylene (from shale gas / naphtha)
Dominant
Cost-sensitive; subject to crude oil volatility
Bio-based
Rapeseed oil methyl ester
Emerging
Ethenolysis; Verbio plant to produce 17,000 tonnes/year from 2026
The U.S. and China shale gas boom has expanded ethylene availability, supporting alpha-olefin production.
Verbio's large-scale ethenolysis plant in Bitterfeld (Germany), scheduled for 2026, will produce 17,000 tonnes of bio-based 1-decene annually.
Regional Share: Europe Leadership and Asia Pacific Momentum
Europe dominates the global 1-decene landscape with approximately 46% revenue share, underpinned by a mature PAO and oxo-alcohol industrial base. Germany is the largest country-level market within Europe.
1-Decene Market Regional Market Share
Loading chart...
1-Decene Market Regional Market Share
Region
Market Share (%)
Europe
0.46%
North America
0.28%
Asia-Pacific
0.18%
South America
0.04%
Middle East & Africa
0.04%
North America: Projected to capture 38% share by 2036, driven by automotive expansion and shale gas feedstock advantage.
Asia Pacific: Fastest-growing region, led by China, India, Japan, South Korea, and Singapore; expanding polyethylene and automotive capacity.
Middle East & Africa: Saudi Arabia and GCC countries benefit from low-cost ethylene feedstock.
Latin America: Brazil and Mexico show steady but moderate growth.
Competitive Landscape and Strategic Developments
The 1-decene market is concentrated among integrated petrochemical majors and specialty chemical producers. Key players include Shell Group, Exxon Mobil Corporation, INEOS AG, Chevron Phillips Chemical Company LLC, Sasol Limited, Qatar Chemical Company Ltd, Idemitsu Kosan Co., Ltd., Saudi Basic Industries Corporation, Alfa Aesar (Thermo Fisher Scientific), and Gelest, Inc.
2026: Verbio commissions world's first large-scale ethenolysis plant (17,000 tonnes/year 1-decene) in Bitterfeld, Germany.
January 2025: Cyclodextrin-mediated hydroformylation process developed, improving catalyst recycling and sustainability.
Table 15: Europe 1-Decene Market Revenue Billion Forecast, by Derivative 2020 & 2034
Table 16: Europe 1-Decene Market Revenue Billion Forecast, by Grade 2020 & 2034
Table 17: Europe 1-Decene Market Revenue Billion Forecast, by Form 2020 & 2034
Frequently Asked Questions
1. What is the current size of the 1-Decene Market?
The global 1-Decene Market was valued at USD 1.11 billion in 2026 and is projected to reach USD 2.06 billion by 2036, growing at a 6.4% CAGR.
2. Which region dominates the 1-Decene Market?
Europe holds the largest share at approximately 46% of global revenue in 2025-2026, driven by a mature PAO and oxo-alcohol industrial base, with Germany as the leading country market.
3. What is the primary application of 1-Decene?
Polyalphaolefins (PAO) account for roughly 67% of derivative consumption, serving as the key feedstock for high-performance synthetic lubricants used in automotive, industrial, and wind-energy applications.
4. What are the key growth drivers for the 1-Decene Market?
Expanding automotive production, rising demand for synthetic lubricants, increasing packaged food consumption, and bio-based feedstock innovations are the primary growth drivers.
5. Who are the leading companies in the 1-Decene Market?
Key players include Shell Group, Exxon Mobil Corporation, INEOS AG, Chevron Phillips Chemical Company LLC, Sasol Limited, Qatar Chemical Company Ltd, Idemitsu Kosan Co., Ltd., and Saudi Basic Industries Corporation.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70-80% of our data foundation derives from primary research, including structured interviews with C-suite executives, procurement heads, and technical directors across the 1-decene value chain.
We conduct interviews with alpha-olefin producers, polyalphaolefin (PAO) blenders, synthetic lubricant formulators, oxo-alcohol manufacturers, and petrochemical feedstock suppliers.
Stakeholder job titles interviewed include Procurement Director, Technical Operations Manager, Supply Chain Head, and R&D Director.
Primary interviews are complemented by plant-level checks and capacity verification across Europe, North America, and Asia Pacific.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
Technical Operations Manager
25%
Supply Chain Head
20%
R&D Director
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Alpha-Olefin Producers
30%
PAO and Synthetic Lubricant Blenders
25%
Oxo-Alcohol and Detergent Manufacturers
20%
Petrochemical Feedstock Suppliers
15%
Specialty Chemical Distributors
10%
Secondary Research & Industry Benchmarking
Roughly 20-30% of the research is sourced from secondary benchmarks, including official multilateral and governmental databases such as UN Comtrade, World Bank, OECD, and Eurostat.
Commercial financial databases used include Bloomberg, Factiva, Hoovers, and PitchBook for corporate financial and capacity disclosures.
All reports are updated to the date of purchase, ensuring the latest available trade flows, pricing, and regulatory changes are reflected.
Demand Modeling & Market Estimation
We employ a simultaneous top-down and bottom-up methodology, validated through multi-level data triangulation.
Our bottom-up market sizing quantifies PAO production volumes (kilotons), ethylene feedstock consumption, automotive lubricant demand (million liters), and packaged food additive volumes (tons).
Segment-level demand is cross-validated against regional capacity utilization rates and import-export trade data from UN Comtrade and US ITC.
Price-volume decomposition is applied to isolate real growth from inflationary effects across the 2027-2036 forecast horizon.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90%, achieved through rigorous multi-source triangulation.
Every data point undergoes a three-tier validation: primary interview confirmation, trade-statistics cross-check, and historical time-series consistency testing.
Outlier detection and sensitivity analysis are performed on all CAGR and market size projections.
Final estimates are reviewed by our internal senior analyst panel before publication, with full audit trails maintained for regulatory and compliance purposes.
GCC
North Africa
South Africa
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Gelest Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 18: Europe 1-Decene Market Revenue (Billion), by Form 2026 & 2034
Figure 19: Europe 1-Decene Market Revenue Share (%), by Form 2026 & 2034
Figure 20: Europe 1-Decene Market Revenue (Billion), by Application 2026 & 2034
Figure 21: Europe 1-Decene Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe 1-Decene Market Revenue (Billion), by End-user 2026 & 2034
Figure 23: Europe 1-Decene Market Revenue Share (%), by End-user 2026 & 2034
Figure 24: Europe 1-Decene Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe 1-Decene Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific 1-Decene Market Revenue (Billion), by Derivative 2026 & 2034
Figure 27: Asia Pacific 1-Decene Market Revenue Share (%), by Derivative 2026 & 2034
Figure 28: Asia Pacific 1-Decene Market Revenue (Billion), by Grade 2026 & 2034
Figure 29: Asia Pacific 1-Decene Market Revenue Share (%), by Grade 2026 & 2034
Figure 30: Asia Pacific 1-Decene Market Revenue (Billion), by Form 2026 & 2034
Figure 31: Asia Pacific 1-Decene Market Revenue Share (%), by Form 2026 & 2034
Figure 32: Asia Pacific 1-Decene Market Revenue (Billion), by Application 2026 & 2034
Figure 33: Asia Pacific 1-Decene Market Revenue Share (%), by Application 2026 & 2034
Figure 34: Asia Pacific 1-Decene Market Revenue (Billion), by End-user 2026 & 2034
Figure 35: Asia Pacific 1-Decene Market Revenue Share (%), by End-user 2026 & 2034
Figure 36: Asia Pacific 1-Decene Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific 1-Decene Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Latin America 1-Decene Market Revenue (Billion), by Derivative 2026 & 2034
Figure 39: Latin America 1-Decene Market Revenue Share (%), by Derivative 2026 & 2034
Figure 40: Latin America 1-Decene Market Revenue (Billion), by Grade 2026 & 2034
Figure 41: Latin America 1-Decene Market Revenue Share (%), by Grade 2026 & 2034
Figure 42: Latin America 1-Decene Market Revenue (Billion), by Form 2026 & 2034
Figure 43: Latin America 1-Decene Market Revenue Share (%), by Form 2026 & 2034
Figure 44: Latin America 1-Decene Market Revenue (Billion), by Application 2026 & 2034
Figure 45: Latin America 1-Decene Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Latin America 1-Decene Market Revenue (Billion), by End-user 2026 & 2034
Figure 47: Latin America 1-Decene Market Revenue Share (%), by End-user 2026 & 2034
Figure 48: Latin America 1-Decene Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Latin America 1-Decene Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa 1-Decene Market Revenue (Billion), by Derivative 2026 & 2034
Figure 51: Middle East & Africa 1-Decene Market Revenue Share (%), by Derivative 2026 & 2034
Figure 52: Middle East & Africa 1-Decene Market Revenue (Billion), by Grade 2026 & 2034
Figure 53: Middle East & Africa 1-Decene Market Revenue Share (%), by Grade 2026 & 2034
Figure 54: Middle East & Africa 1-Decene Market Revenue (Billion), by Form 2026 & 2034
Figure 55: Middle East & Africa 1-Decene Market Revenue Share (%), by Form 2026 & 2034
Figure 56: Middle East & Africa 1-Decene Market Revenue (Billion), by Application 2026 & 2034
Figure 57: Middle East & Africa 1-Decene Market Revenue Share (%), by Application 2026 & 2034
Figure 58: Middle East & Africa 1-Decene Market Revenue (Billion), by End-user 2026 & 2034
Figure 59: Middle East & Africa 1-Decene Market Revenue Share (%), by End-user 2026 & 2034
Figure 60: Middle East & Africa 1-Decene Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa 1-Decene Market Revenue Share (%), by Country 2026 & 2034
Table 18: Europe 1-Decene Market Revenue Billion Forecast, by Application 2020 & 2034
Table 19: Europe 1-Decene Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 20: Europe 1-Decene Market Revenue Billion Forecast, by Country 2020 & 2034


 1-Decene Market