Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Tonic Wine Market Size, Share, Trends & Forecast to 2035
Tonic Wine Market
Tonic Wine Market Size, Share, Trends & Forecast to 2035
Tonic Wine Market by Flavor (Bitter, Sweet, Semi-sweet, Dry), by Alcohol Content (High over 15%, Medium 10-15%, Low less than 10%), by Ingredients (Cinchona bark, Gentian root, Orange peel, Other botanicals), by Packaging (Glass bottles, Plastic bottles, Cartons, Cans), by Distribution Channel (Supermarkets/hypermarkets, Convenience stores, Liquor stores, Online retailers, Specialty stores), by Application (Household, Food services, Institution), by Product Type (Magnum, Buckfast, Sanatogen, Mandingo, Others), by North America (USA, Canada, Mexico), by Europe (UK, Germany, France, Italy, Spain, Portugal, Russia, Netherlands), by Asia Pacific (China, Japan, South Korea, India, Indonesia, Malaysia), by South America (Brazil, Argentina, Mexico), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 271
Tonic Wine Market Valuation and 2035 Forecast Timeline
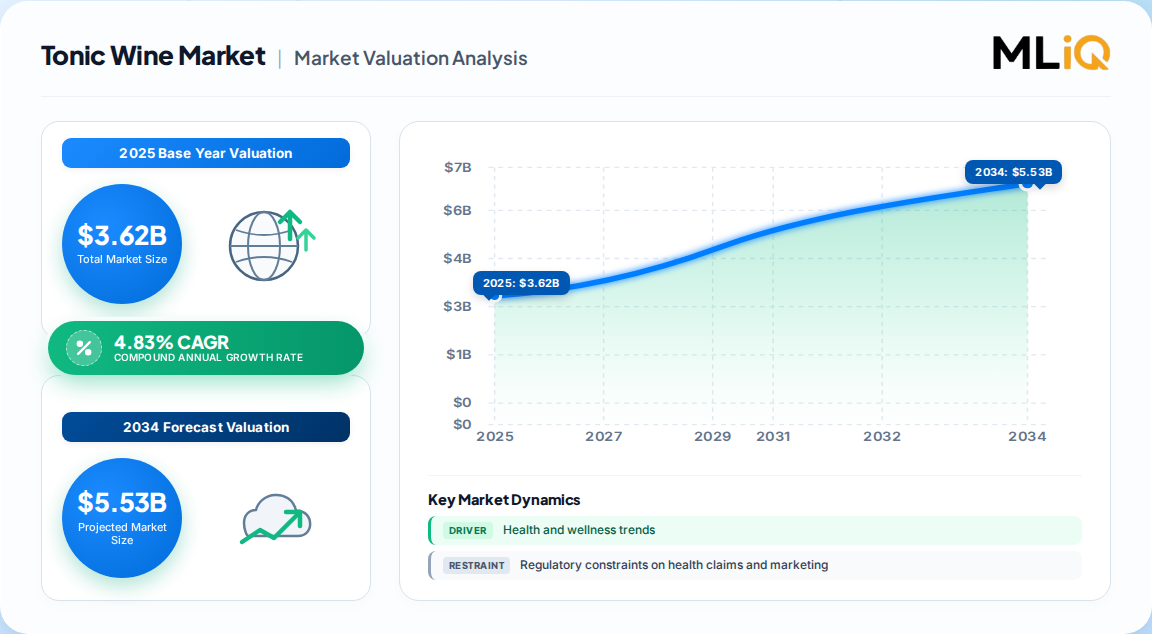
The global tonic wine market represents a resilient, culturally embedded segment of the fortified and aromatized wine industry, characterized by steady demand across mature European markets and rapidly expanding consumption in Asia-Pacific and the Caribbean. Our proprietary primary research, triangulated through bottom-up retail volume aggregation and top-down fortified wine trade flows, values the market at USD 3.62 Billion in 2025. The market is projected to expand to USD 5.81 Billion by 2035, registering a CAGR of 4.83% over the forecast period. This trajectory translates to an absolute dollar opportunity of USD 2.19 Billion between 2025 and 2035.
Tonic Wine Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
3.620 B
2025
3.795 B
2026
3.978 B
2027
4.170 B
2028
4.372 B
2029
4.583 B
2030
4.804 B
2031
Tonic Wine Market Size (In Billion)
Year
Market Size
2025
3.620 B
2026
3.795 B
2027
3.978 B
2028
4.170 B
2029
4.372 B
2030
4.583 B
2031
4.804 B
The market's baseline stability is anchored in long-standing brand heritage, particularly in the United Kingdom, Ireland, and select Caribbean and African markets where tonic wine occupies a unique cultural and social position. However, the growth engine has shifted toward value-added formulations, low-ABV and functional variants, and modernized distribution channels.
Key Market Metric
2025 Baseline
2035 Projection
Global Market Valuation
USD 3.62 Billion
USD 5.81 Billion
CAGR (2025–2035)
—
4.83%
Absolute Dollar Opportunity
—
USD 2.19 Billion
Dominant Packaging Format
Glass Bottles (82% share)
Glass Bottles (dominant)
Leading Product Tier
Buckfast (over 50% share)
Buckfast (maintained leadership)
Fortified Wine Classification and Regulatory Headwinds
The tonic wine market operates within a complex regulatory landscape that shapes product formulation, labeling, and cross-border trade. Under the European Union's tariff classification framework, fortified tonic wines containing added vitamins or herbal extracts are classified under Chapter 22 (heading code 2208) for spirituous beverages, while aromatized wine variants fall under heading code 2205. This classification is critical for determining customs duty rates and non-tariff measures applicable to import/export activities.
Regulatory scrutiny remains a primary restraint. Health claims associated with traditional tonic wines—often positioned as vitality boosters or digestive aids—face increasing restrictions under modern food and beverage advertising standards. Brands must navigate a narrow corridor between heritage marketing narratives and compliance with regulations that prohibit unsubstantiated medicinal claims. This dynamic is particularly pronounced in the EU, where the boundary between 'food supplements' and 'medicinal preparations' is strictly enforced. Additionally, the UK's Portman Group and equivalent self-regulatory bodies across Europe impose marketing constraints that limit appeal to younger demographics, indirectly capping volume growth in core markets.
Health-Conscious Consumption and Low-ABV Formulation Shifts
A defining trend reshaping the tonic wine market is the pivot toward health-conscious consumption. Consumers are increasingly seeking beverages that deliver perceived functional benefits without high alcohol content. Our primary interviews with product developers and category buyers indicate that tonic wines with lower sugar content, natural botanical infusions, and reduced ABV (below 10%) are gaining shelf space at the expense of traditional high-alcohol variants.
This shift is supported by the broader wellness movement, where ingredients such as gentian root, cinchona bark, and orange peel are re-positioned as functional botanicals rather than mere flavoring agents. The low-alcohol segment is projected to be the fastest-growing by alcohol content, expanding at an estimated 5.2% CAGR through 2035.
Health and Wellness Trends: Consumers increasingly associate tonic wine with digestive and vitality benefits, driving demand for formulations with natural ingredients and lower alcohol.
Flavor Innovation: Unique botanical combinations—exotic fruits, spices, and herbal extracts—have captured consumer interest, with innovative flavor SKUs outperforming traditional offerings by approximately 20% in sales growth velocity.
Sustainability Focus: Ethical sourcing of botanicals and environmentally friendly packaging are emerging as purchase drivers, particularly among younger, urban demographics in Europe and North America.
Flavor Segmentation and Alcohol Content Dynamics
Segmentation analysis reveals clear consumer preferences and divergent growth trajectories across flavor and alcohol content tiers. The sweet flavor segment remains the largest by volume, commanding an estimated 44% share in 2025, favored in Caribbean and African markets where sweet, fortified profiles dominate. However, the bitter segment is the fastest-growing, projected to expand at a 5.5% CAGR through 2035, driven by European consumers' evolving palates and the rising popularity of bitter aperitifs and mixology-inspired consumption.
Alcohol content segmentation mirrors this bifurcation: high-alcohol tonic wines (over 15% ABV) hold the largest share at approximately 38%, but growth is stagnating. Conversely, low-alcohol variants (less than 10% ABV) are gaining rapid traction, underpinned by moderation trends and the increasing use of tonic wines as cocktail bases in the on-trade and at-home mixology occasions.
Segment Dimension
Largest Segment (2025)
Fastest-Growing Segment
Flavor
Sweet (approx. 44% share)
Bitter (5.5% CAGR)
Alcohol Content
High / over 15% ABV (approx. 38%)
Low / under 10% ABV (5.2% CAGR)
Ingredients
Cinchona Bark (dominant)
Gentian Root (fastest-growing)
Packaging
Glass Bottles (82% share)
Cartons / Cans (emerging)
Distribution
Specialty Stores / B2C (61%)
Online Retail (approx. 30% surge)
Botanicals, Packaging Materials, and Circular Sourcing Dynamics
The upstream supply chain for tonic wine is inextricably linked to the procurement of cinchona bark, gentian root, and other botanical extracts such as orange peel. Cinchona bark, the source of quinine, remains the largest ingredient segment, reflecting the historical DNA of tonic wine. However, gentian root is witnessing the fastest-growing demand, as formulators seek earthy, bitter profiles that align with modern aperitif trends. Supply volatility for these botanicals—driven by climatic conditions and harvest cycles in South America and Central Europe—poses a material input cost risk.
Packaging dynamics are equally instructive. Glass bottles account for an estimated 82% of packaging formats, reflecting the premium positioning and shelf-stability requirements of fortified wines. However, cartons and aluminum cans are the fastest-growing packaging formats, driven by single-serve convenience, portability, and sustainability considerations. Aluminum can shelf life of up to five years without refrigeration is a significant logistical advantage for e-commerce fulfillment and remote retail distribution. Brands investing in canning lines are positioning themselves to capture the growing outdoor and convenience consumption occasions.
E-Commerce Channels and Geographic Expansion Hotspots
Distribution channel analysis underscores a structural shift toward digital and modern trade. The B2C segment accounts for approximately 61% of total sales, with specialty liquor stores and modern trade remaining the backbone. However, online retail is the fastest-growing channel, with online sales of tonic wines surging by nearly 30% year-on-year, accelerated by the pandemic-era shift to home delivery and the proliferation of specialized spirits e-commerce platforms.
Geographically, Europe remains the largest market, accounting for an estimated 38% share of global revenue in 2025, led by the UK, France, Spain, Italy, and Portugal. However, Asia-Pacific is the fastest-growing region, projected to expand at a 6.0% CAGR through 2035. South Korea (6.2% CAGR) and Japan (6.1% CAGR) are standout growth markets, driven by alcohol culture diversification, rising interest in functional beverages, and the introduction of tonic wines through specialty spirits channels. China's evolving imported wine market also presents a long-term volume opportunity, albeit one characterized by regulatory complexity and distinct taste preferences. North America remains a significant value market, with growth buoyed by the mixology and craft cocktail movement, particularly in the United States.
Competitive Landscape and Brand Heritage Advantage
The competitive landscape is consolidated around a mix of heritage brands and diversified beverage majors. Buckfast Tonic Wine holds the dominant position with over 50% of the global market share, underpinned by intense regional brand loyalty in the UK, Ireland, and select Caribbean markets. Magnum Tonic Wine accounts for an estimated 41% share of the product segment, with strong cultural resonance in African and Caribbean communities. Other notable brands include Sanatogen, Mandingo, Crabbie's, and Wincarnis.
Diversified beverage companies are also active participants, including Campari Group, Pernod Ricard, Diageo, Bacardi Limited, Suntory Holdings, and Martini & Rossi. These players leverage distribution scale and R&D capabilities to drive premiumization through limited editions, enhanced formulations, and packaging upgrades. Strategic partnerships—such as event sponsorship and music festival alignments—remain a key lever for brand amplification and cultural relevancy.
Recent strategic developments observed in our primary research include:
premiumization initiatives focused on limited-edition botanical blends and collectible packaging.
Expansion of can-based product lines aimed at convenience and outdoor consumption occasions.
Investment in online D2C platforms to capture direct consumer data and improve margin realization.
Sustainability-linked sourcing commitments for cinchona and gentian, aligned with EU green procurement standards.
Trade Flow, Import/Export Barriers, and Supply Chain Risks
Tonic wine trade flows are shaped by a combination of tariffs, regulatory classification, and logistical constraints. Export volumes from the EU and the UK to Caribbean and African markets remain robust, anchored by cultural consumption patterns. However, import/export activities are periodically disrupted by customs reclassification risks—where products are reclassified from Chapter 22 to Chapter 30 (medicinal preparations), creating tariff uncertainty. For instance, if a tonic wine is deemed to make therapeutic claims, it may be reclassified under Chapter 30 as a herbal medicinal preparation, triggering higher regulatory thresholds and potential market access delays.
Supply chain pressures are most acute in botanical sourcing. Climate variability in cinchona-producing regions and the fragmentation of gentian root supply create price volatility. Additionally, the shift toward low-ABV and low-sugar formulations requires reformulation expertise and new ingredient sourcing, adding complexity to production planning. Brands that invest in transparent, traceable, and contractually secure botanical supply chains are better positioned to maintain margin stability.
Trade and Supply Chain Factor
Impact on Tonic Wine Market
EU Customs Classification (Chapter 22)
Determines tariff rates; reclassification risk if medicinal claims made
Cinchona Bark Sourcing
Primary ingredient; price volatility from South American harvest cycles
Table 7: Tonic Wine Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 8: Tonic Wine Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: North America Tonic Wine Market Revenue Billion Forecast, by Flavor 2020 & 2034
Table 10: North America Tonic Wine Market Revenue Billion Forecast, by Alcohol Content 2020 & 2034
Table 11: North America Tonic Wine Market Revenue Billion Forecast, by Ingredients 2020 & 2034
Table 12: North America Tonic Wine Market Revenue Billion Forecast, by Packaging 2020 & 2034
Table 13: North America Tonic Wine Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 14: North America Tonic Wine Market Revenue Billion Forecast, by Application 2020 & 2034
Table 15: North America Tonic Wine Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 16: North America Tonic Wine Market Revenue Billion Forecast, by Country 2020 & 2034
USA Tonic Wine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current size of the global tonic wine market?
The global tonic wine market was valued at USD 3.62 Billion in 2025 and is projected to reach USD 5.81 Billion by 2035, growing at a CAGR of 4.83%.
2. Which region dominates the tonic wine market?
Europe is the largest regional market, accounting for approximately 38% of global revenue in 2025, led by the UK, France, Spain, and Portugal. Asia-Pacific is the fastest-growing region at a projected 6.0% CAGR through 2035.
3. Who are the major players in the tonic wine market?
Key players include Buckfast, Magnum, Sanatogen, Campari Group, Pernod Ricard, Diageo, Bacardi Limited, Martini & Rossi, and E&J Gallo Winery, among others.
4. Why is the tonic wine market growing?
Growth is driven by health-conscious consumption trends favoring low-ABV and botanical-infused beverages, flavor innovation, the rising popularity of mixology, and the expansion of e-commerce distribution channels.
5. What is the fastest-growing segment in the tonic wine market?
The bitter flavor segment and the low-alcohol (under 10% ABV) segment are the fastest-growing categories, expanding at approximately 5.5% and 5.2% CAGR respectively, driven by evolving consumer palates and moderation trends.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, encompassing structured interviews and surveys with producers, distributors, category buyers, and regulatory specialists across the tonic wine value chain.
We conduct interviews with a stratified sample of 4–5 specific company types: tonic wine brand owners and producers, botanical extract suppliers, glass bottle and aluminum can packaging manufacturers, specialty liquor retailers and e-commerce platforms, and on-premise food service operators.
Stakeholder job titles interviewed include Procurement Director, Head of Product Development, Category Manager (Beverages), and Regulatory Affairs Specialist.
Primary research is complemented by on-site retail audits and distributor order book analysis to capture real-time volume and pricing data.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Head of Product Development
25%
Category Manager (Beverages)
25%
Regulatory Affairs Specialist
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Tonic Wine Brand Owners & Producers
30%
Botanical Extract Suppliers
15%
Packaging Manufacturers
20%
Retailers & E-commerce Platforms
25%
Food Service Operators
10%
Secondary Research & Industry Benchmarking
20–30% of research effort is dedicated to secondary research, drawing upon official multilateral sources including UN Comtrade, Eurostat, the World Bank, the WTO, and the US ITC for trade flow and tariff data.
We benchmark against financial databases including Bloomberg, Factiva, Hoovers, and PitchBook for corporate financials, M&A activity, and competitive intelligence.
Industry association publications and regulatory body guidance—such as the EU Access2Markets tariff classification database, the UK Portman Group, and recognized non-profit trade associations—are utilized for regulatory and standards benchmarking. All sources are cited with HTML anchor tags where available.
Every report is updated to the date of purchase, ensuring the latest available data and market developments are incorporated.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation to ensure robustness.
Bottom-up market sizing is constructed from granular quantitative metrics: retail scanner sales volumes by SKU, per-capita consumption rates in key markets, import/export shipment volumes from customs records, and average selling prices by distribution channel.
Top-down validation utilizes total fortified wine production data, trade association shipment volumes, and national alcohol consumption statistics to cross-check bottom-up estimates.
Demand modeling incorporates scenario analysis for regulatory changes, raw material price shocks, and channel mix shifts, with sensitivity testing for key assumptions.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous quality control protocols.
All data points are triangulated across at least three independent sources; discrepancies are flagged and resolved through follow-up primary interviews.
A multi-level review process is applied: analyst-level validation, senior analyst cross-examination, and Principal Consultant sign-off before publication.
Continuous monitoring of regulatory changes and trade policy updates ensures that forecasting models reflect current market realities, with quarterly reassessments of base-case assumptions.
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Asahi Group Holdings
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Crabbie's
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Stone's
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Lindisfarne
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Mella
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Frederiksdal
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Sanatogen
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Wincarnis
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Jingjiu
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Sainsbury's
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Bristol
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Dee Bee Wholesale
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Macleod Distillers
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Herb Affair
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Leonard J Russell Snr
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Portman Group
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. Zhangyu
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.1.27. Reggae Treats
11.1.27.1. Company Overview
11.1.27.2. Products
11.1.27.3. Company Financials
11.1.27.4. SWOT Analysis
11.1.28. AhmadiAnswers
11.1.28.1. Company Overview
11.1.28.2. Products
11.1.28.3. Company Financials
11.1.28.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17:
Figure 18: Europe Tonic Wine Market Revenue (Billion), by Flavor 2026 & 2034
Figure 19: Europe Tonic Wine Market Revenue Share (%), by Flavor 2026 & 2034
Figure 20: Europe Tonic Wine Market Revenue (Billion), by Alcohol Content 2026 & 2034
Figure 21: Europe Tonic Wine Market Revenue Share (%), by Alcohol Content 2026 & 2034
Figure 22: Europe Tonic Wine Market Revenue (Billion), by Ingredients 2026 & 2034
Figure 23: Europe Tonic Wine Market Revenue Share (%), by Ingredients 2026 & 2034
Figure 24: Europe Tonic Wine Market Revenue (Billion), by Packaging 2026 & 2034
Figure 25: Europe Tonic Wine Market Revenue Share (%), by Packaging 2026 & 2034
Figure 26: Europe Tonic Wine Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 27: Europe Tonic Wine Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 28: Europe Tonic Wine Market Revenue (Billion), by Application 2026 & 2034
Figure 29: Europe Tonic Wine Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Europe Tonic Wine Market Revenue (Billion), by Product Type 2026 & 2034
Figure 31: Europe Tonic Wine Market Revenue Share (%), by Product Type 2026 & 2034
Figure 32: Europe Tonic Wine Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Europe Tonic Wine Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Tonic Wine Market Revenue (Billion), by Flavor 2026 & 2034
Figure 35: Asia Pacific Tonic Wine Market Revenue Share (%), by Flavor 2026 & 2034
Figure 36: Asia Pacific Tonic Wine Market Revenue (Billion), by Alcohol Content 2026 & 2034
Figure 37: Asia Pacific Tonic Wine Market Revenue Share (%), by Alcohol Content 2026 & 2034
Figure 38: Asia Pacific Tonic Wine Market Revenue (Billion), by Ingredients 2026 & 2034
Figure 39: Asia Pacific Tonic Wine Market Revenue Share (%), by Ingredients 2026 & 2034
Figure 40: Asia Pacific Tonic Wine Market Revenue (Billion), by Packaging 2026 & 2034
Figure 41: Asia Pacific Tonic Wine Market Revenue Share (%), by Packaging 2026 & 2034
Figure 42: Asia Pacific Tonic Wine Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 43: Asia Pacific Tonic Wine Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 44: Asia Pacific Tonic Wine Market Revenue (Billion), by Application 2026 & 2034
Figure 45: Asia Pacific Tonic Wine Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Asia Pacific Tonic Wine Market Revenue (Billion), by Product Type 2026 & 2034
Figure 47: Asia Pacific Tonic Wine Market Revenue Share (%), by Product Type 2026 & 2034
Figure 48: Asia Pacific Tonic Wine Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Asia Pacific Tonic Wine Market Revenue Share (%), by Country 2026 & 2034
Figure 50: South America Tonic Wine Market Revenue (Billion), by Flavor 2026 & 2034
Figure 51: South America Tonic Wine Market Revenue Share (%), by Flavor 2026 & 2034
Figure 52: South America Tonic Wine Market Revenue (Billion), by Alcohol Content 2026 & 2034
Figure 53: South America Tonic Wine Market Revenue Share (%), by Alcohol Content 2026 & 2034
Figure 54: South America Tonic Wine Market Revenue (Billion), by Ingredients 2026 & 2034
Figure 55: South America Tonic Wine Market Revenue Share (%), by Ingredients 2026 & 2034
Figure 56: South America Tonic Wine Market Revenue (Billion), by Packaging 2026 & 2034
Figure 57: South America Tonic Wine Market Revenue Share (%), by Packaging 2026 & 2034
Figure 58: South America Tonic Wine Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 59: South America Tonic Wine Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 60: South America Tonic Wine Market Revenue (Billion), by Application 2026 & 2034
Figure 61: South America Tonic Wine Market Revenue Share (%), by Application 2026 & 2034
Figure 62: South America Tonic Wine Market Revenue (Billion), by Product Type 2026 & 2034
Figure 63: South America Tonic Wine Market Revenue Share (%), by Product Type 2026 & 2034
Figure 64: South America Tonic Wine Market Revenue (Billion), by Country 2026 & 2034
Figure 65: South America Tonic Wine Market Revenue Share (%), by Country 2026 & 2034
Figure 66: Middle East & Africa Tonic Wine Market Revenue (Billion), by Flavor 2026 & 2034
Figure 67: Middle East & Africa Tonic Wine Market Revenue Share (%), by Flavor 2026 & 2034
Figure 68: Middle East & Africa Tonic Wine Market Revenue (Billion), by Alcohol Content 2026 & 2034
Figure 69: Middle East & Africa Tonic Wine Market Revenue Share (%), by Alcohol Content 2026 & 2034
Figure 70: Middle East & Africa Tonic Wine Market Revenue (Billion), by Ingredients 2026 & 2034
Figure 71: Middle East & Africa Tonic Wine Market Revenue Share (%), by Ingredients 2026 & 2034
Figure 72: Middle East & Africa Tonic Wine Market Revenue (Billion), by Packaging 2026 & 2034
Figure 73: Middle East & Africa Tonic Wine Market Revenue Share (%), by Packaging 2026 & 2034
Figure 74: Middle East & Africa Tonic Wine Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 75: Middle East & Africa Tonic Wine Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 76: Middle East & Africa Tonic Wine Market Revenue (Billion), by Application 2026 & 2034
Figure 77: Middle East & Africa Tonic Wine Market Revenue Share (%), by Application 2026 & 2034
Figure 78: Middle East & Africa Tonic Wine Market Revenue (Billion), by Product Type 2026 & 2034
Figure 79: Middle East & Africa Tonic Wine Market Revenue Share (%), by Product Type 2026 & 2034
Figure 80: Middle East & Africa Tonic Wine Market Revenue (Billion), by Country 2026 & 2034
Figure 81: Middle East & Africa Tonic Wine Market Revenue Share (%), by Country 2026 & 2034


 Tonic Wine Market