Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Tomato Industry Market Size, Share & Growth Forecast 2026-2031
Tomato Industry Market Size, Share & Growth Forecast 2026-2031
Tomato Industry
Tomato Industry Market Size, Share & Growth Forecast 2026-2031
Tomato Industry by Product (Sauces, Paste, Canned Tomatoes, Ketchup, Juice, Others), by Type (Roma Tomatoes, Cherry Tomatoes, Grape Tomatoes, Beefsteak Tomatoes, Heirloom Tomatoes, Tomatoes On The Vine, Green Tomatoes, Others), by Category (Conventional, Organic), by End User (Household, Food Service Industry), by Distribution Channel (Direct, Indirect), by North America (USA, Canada, Mexico), by Europe (Spain, Italy, Netherlands, Poland), by Asia-Pacific (China, India, Japan), by South America (Brazil, Argentina), by Middle East & Africa (Egypt, Nigeria, Turkey) Forecast 2026-2034
Tomato Industry market Valuation Timeline 2026–2031
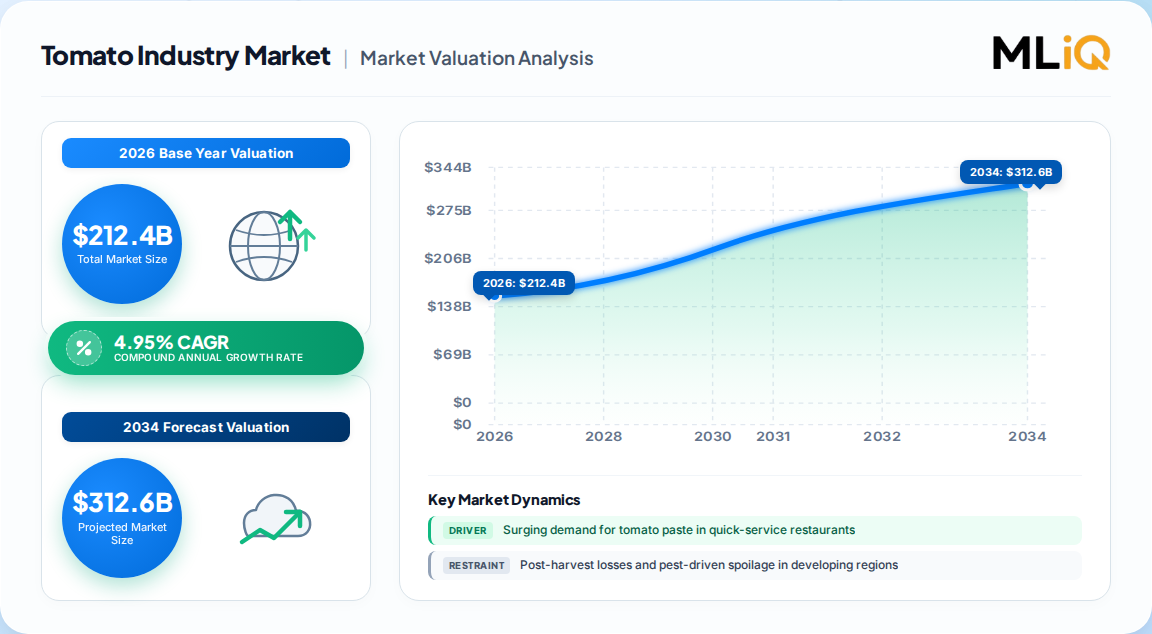
The global tomato industry market is projected to expand from USD 212.4 billion in 2026 to USD 270.5 billion by 2031, registering a 4.95% CAGR. This growth reflects sustained demand for both fresh and processed tomato products, alongside technological advances in protected cultivation.
Tomato Industry Market Size (In Billion)
300.0B
200.0B
100.0B
0
202.4 B
2025
212.4 B
2026
222.9 B
2027
233.9 B
2028
245.5 B
2029
257.7 B
2030
270.4 B
2031
Tomato Industry Market Size (In Billion)
Year
Market Size
2025
202.4 B
2026
212.4 B
2027
222.9 B
2028
233.9 B
2029
245.5 B
2030
257.7 B
2031
270.4 B
Metric
Value
Market Size (2026)
USD 212.4 Billion
Market Size (2031)
USD 270.5 Billion
CAGR (2026–2031)
4.95%
Fastest Growing Region
Africa (4.8% CAGR)
Largest Regional Share
Asia-Pacific (47.0% in 2025)
Leading Product Segment
Sauces (29.4% share)
Leading Type Segment
Roma Tomatoes (24.3% share)
Asia-Pacific dominates with a 47.0% share, driven by China’s processing capacity and India’s production volumes.
Africa emerges as the fastest-growing region, supported by government incentives and drip irrigation expansion.
Conventional tomatoes command 89.5% of the category segment, favored for affordability and scale.
Processed Tomato Products Demand Dynamics
The processed segment—sauces, paste, canned tomatoes, ketchup, and juice—accounts for a dominant share of market value. Sauces lead with 29.4% of product segmentation in 2025, while ketchup is forecast to grow at 5.9% CAGR through 2031.
Quick-service restaurants (QSR) and ready-meal brands are locking in multi-year supply contracts, tightening spot availability of paste and diced tomatoes.
China’s paste consumption is rising at 7% CAGR, outpacing its 1.5 million metric ton capacity and eroding its export surplus.
Italy processed 5.2 million metric tons in 2024, with branded sauce (6% CAGR) diverting volumes from export channels.
Nigeria spends USD 360 million annually on paste imports, incentivizing local processors to integrate backward with growers.
Greenhouse and Protected Cultivation Expansion
Protected cultivation is reshaping yield benchmarks and quality standards. Greenhouse clusters in the Netherlands, Mexico, and Japan deliver yields two to three times higher than open-field benchmarks.
Region
Greenhouse Metric
Netherlands
USD 1.89 billion in greenhouse tomato exports (2024); 30% natural gas reduction via LED lighting
Mexico (Sinaloa)
70 metric tons per acre—double California’s open-field yield
Japan
25% price premium for zero-residue hydroponic produce
AI-driven optimization and digital twin technologies are enabling real-time monitoring of temperature, humidity, and irrigation, with a 2026 study in China reporting 20–30% yield increases and 60% water savings.
Government incentives such as India’s Production Linked Incentive Scheme (USD 1.31 billion) and Egypt’s drip irrigation expansion (120,000 hectares) are accelerating adoption.
Post-Harvest Losses and Supply Chain Constraints
Post-harvest losses remain a critical restraint, with up to 20% of harvested tomatoes in developing regions never reaching consumers due to inadequate cold-chain infrastructure.
India loses 11.61% of its crop despite cold-chain subsidies.
Nigeria’s 18% spoilage rate inflates its USD 360 million paste import bill.
The invasive moth Tuta absoluta cuts yields by 30% across East Africa.
These gaps invite investment in integrated cold-chain logistics and pest-management service firms, presenting opportunities for value-chain consolidation.
Regional Trade Flows and Import Dependencies
Global trade in tomatoes and processed products is shaped by structural deficits and surpluses. West Africa’s intra-regional food trade—including tomatoes—is valued at USD 10 billion annually, six times higher than official records, with up to 85% going unrecorded (OECD, 2025).
Mexico and the Netherlands are leading exporters of greenhouse tomatoes, while China and Italy dominate processed paste and sauce exports.
Import-dependent nations such as Nigeria and Gulf states are scaling domestic processing to curb trade deficits.
Competitive Landscape and Strategic Developments
The market is highly competitive, with leading players focusing on capacity expansion, processing technology, and sustainable sourcing.
Company
Strategic Focus
The Morning Star Company
Large-scale processing and bulk paste supply
COFCO Tunhe Tomato Co. Ltd.
China’s leading paste producer with export orientation
Xinjiang Chalkis Company Ltd.
Integrated tomato processing in Xinjiang
Ingomar Packing Co.
California-based processing and bulk ingredients
ConAgra Brands Inc.
Branded sauces and ketchup
Olam International
Global agri-supply chain and processing
Los Gatos Tomato Products
Premium processed tomato products
China Haohan Group Limited
Diversified agricultural processing
Campbell Soup Company
Branded soups and sauces; USDA grant for tomato farming
Toma-Tek (Neil Jones Food Company)
Industrial tomato processing
Campbell Soup Company received a USD 3.4 million USDA grant to support tomato farming in California.
A EUR 10 million investment was secured to develop autonomous deleafing technology, signaling automation trends.
Purdue University received a USD 3.5 million grant for tomato research, focusing on disease resistance and yield.
Future Outlook: Precision Agriculture and Value-Added Products
Emerging opportunities lie in precision agriculture, organic certification, and value-added product innovation.
AI-powered breeding (e.g., Syngenta’s TomatoVision) accelerates variety selection, with only 1–3% of tested varieties reaching commercialization.
Organic tomatoes command a 111.6% price premium over conventional, with a 4.7% sales uptick in 2024.
Zero-residue hydroponic production is gaining traction, particularly in Japan and the EU, where labeling mandates are polarizing shelves.
Carbon-footprint scrutiny of energy-intensive greenhouses is driving investment in renewable energy and circular systems.
The tomato industry market is poised for steady expansion, balancing yield intensification with sustainability and supply-chain resilience.
Tomato Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Tomato Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.95% from 2020-2034
Segmentation
By Product
Sauces
Paste
Canned Tomatoes
Ketchup
Juice
Others
By Type
Roma Tomatoes
Cherry Tomatoes
Grape Tomatoes
Beefsteak Tomatoes
Heirloom Tomatoes
Tomatoes On The Vine
Green Tomatoes
Others
By Category
Conventional
Organic
By End User
Household
Food Service Industry
By Distribution Channel
Direct
Indirect
By Geography
North America
USA
Canada
Mexico
Europe
Spain
Italy
Netherlands
Poland
Asia-Pacific
China
India
Japan
South America
Brazil
Argentina
Middle East & Africa
Egypt
Nigeria
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Sauces
5.1.2. Paste
5.1.3. Canned Tomatoes
5.1.4. Ketchup
5.1.5. Juice
5.1.6. Others
5.2. Market Analysis, Insights and Forecast - by Type
5.2.1. Roma Tomatoes
5.2.2. Cherry Tomatoes
5.2.3. Grape Tomatoes
5.2.4. Beefsteak Tomatoes
5.2.5. Heirloom Tomatoes
5.2.6. Tomatoes On The Vine
5.2.7. Green Tomatoes
5.2.8. Others
5.3. Market Analysis, Insights and Forecast - by Category
5.3.1. Conventional
5.3.2. Organic
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Household
5.4.2. Food Service Industry
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Direct
5.5.2. Indirect
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Sauces
6.1.2. Paste
6.1.3. Canned Tomatoes
6.1.4. Ketchup
6.1.5. Juice
6.1.6. Others
6.2. Market Analysis, Insights and Forecast - by Type
6.2.1. Roma Tomatoes
6.2.2. Cherry Tomatoes
6.2.3. Grape Tomatoes
6.2.4. Beefsteak Tomatoes
6.2.5. Heirloom Tomatoes
6.2.6. Tomatoes On The Vine
6.2.7. Green Tomatoes
6.2.8. Others
6.3. Market Analysis, Insights and Forecast - by Category
6.3.1. Conventional
6.3.2. Organic
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Household
6.4.2. Food Service Industry
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Direct
6.5.2. Indirect
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Sauces
7.1.2. Paste
7.1.3. Canned Tomatoes
7.1.4. Ketchup
7.1.5. Juice
7.1.6. Others
7.2. Market Analysis, Insights and Forecast - by Type
7.2.1. Roma Tomatoes
7.2.2. Cherry Tomatoes
7.2.3. Grape Tomatoes
7.2.4. Beefsteak Tomatoes
7.2.5. Heirloom Tomatoes
7.2.6. Tomatoes On The Vine
7.2.7. Green Tomatoes
7.2.8. Others
7.3. Market Analysis, Insights and Forecast - by Category
7.3.1. Conventional
7.3.2. Organic
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Household
7.4.2. Food Service Industry
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Direct
7.5.2. Indirect
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Sauces
8.1.2. Paste
8.1.3. Canned Tomatoes
8.1.4. Ketchup
8.1.5. Juice
8.1.6. Others
8.2. Market Analysis, Insights and Forecast - by Type
8.2.1. Roma Tomatoes
8.2.2. Cherry Tomatoes
8.2.3. Grape Tomatoes
8.2.4. Beefsteak Tomatoes
8.2.5. Heirloom Tomatoes
8.2.6. Tomatoes On The Vine
8.2.7. Green Tomatoes
8.2.8. Others
8.3. Market Analysis, Insights and Forecast - by Category
8.3.1. Conventional
8.3.2. Organic
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Household
8.4.2. Food Service Industry
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Direct
8.5.2. Indirect
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Sauces
9.1.2. Paste
9.1.3. Canned Tomatoes
9.1.4. Ketchup
9.1.5. Juice
9.1.6. Others
9.2. Market Analysis, Insights and Forecast - by Type
9.2.1. Roma Tomatoes
9.2.2. Cherry Tomatoes
9.2.3. Grape Tomatoes
9.2.4. Beefsteak Tomatoes
9.2.5. Heirloom Tomatoes
9.2.6. Tomatoes On The Vine
9.2.7. Green Tomatoes
9.2.8. Others
9.3. Market Analysis, Insights and Forecast - by Category
9.3.1. Conventional
9.3.2. Organic
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Household
9.4.2. Food Service Industry
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Direct
9.5.2. Indirect
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Sauces
10.1.2. Paste
10.1.3. Canned Tomatoes
10.1.4. Ketchup
10.1.5. Juice
10.1.6. Others
10.2. Market Analysis, Insights and Forecast - by Type
10.2.1. Roma Tomatoes
10.2.2. Cherry Tomatoes
10.2.3. Grape Tomatoes
10.2.4. Beefsteak Tomatoes
10.2.5. Heirloom Tomatoes
10.2.6. Tomatoes On The Vine
10.2.7. Green Tomatoes
10.2.8. Others
10.3. Market Analysis, Insights and Forecast - by Category
10.3.1. Conventional
10.3.2. Organic
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Household
10.4.2. Food Service Industry
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Direct
10.5.2. Indirect
11. Competitive Analysis
11.1. Company Profiles
11.1.1. The Morning Star Company
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. COFCO Tunhe Tomato Co. Ltd.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Xinjiang Chalkis Company Ltd.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Ingomar Packing Co.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. ConAgra Brands Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Olam International
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Los Gatos Tomato Products
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. China Haohan Group Limited
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Campbell Soup Company
12. Research Methodology
List of Figures
Figure 1: Tomato Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Tomato Industry Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Tomato Industry Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Tomato Industry Revenue (Billion), by Type 2026 & 2034
Figure 5: North America Tomato Industry Revenue Share (%), by Type 2026 & 2034
Figure 6: North America Tomato Industry Revenue (Billion), by Category 2026 & 2034
Figure 7: North America Tomato Industry Revenue Share (%), by Category 2026 & 2034
Figure 8: North America Tomato Industry Revenue (Billion), by End User 2026 & 2034
Figure 9: North America Tomato Industry Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Tomato Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Tomato Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Tomato Industry Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Tomato Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Tomato Industry Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Tomato Industry Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Tomato Industry Revenue (Billion), by Type 2026 & 2034
Figure 17: Europe Tomato Industry Revenue Share (%), by Type 2026 & 2034
List of Tables
Table 1: Tomato Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Tomato Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 3: Tomato Industry Revenue Billion Forecast, by Category 2020 & 2034
Table 4: Tomato Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 5: Tomato Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Tomato Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Tomato Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 8: North America Tomato Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 9: North America Tomato Industry Revenue Billion Forecast, by Category 2020 & 2034
Table 10: North America Tomato Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 11: North America Tomato Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: North America Tomato Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Tomato Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Tomato Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Tomato Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Tomato Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 17: Europe Tomato Industry Revenue Billion Forecast, by Type 2020 & 2034
Frequently Asked Questions
1. What is the current size of the global tomato industry market?
The global tomato industry market is valued at USD 212.4 billion in 2026 and is projected to reach USD 270.5 billion by 2031, growing at a 4.95% CAGR.
2. Which region dominates the tomato industry market?
Asia-Pacific leads with a 47.0% market share in 2025, driven by China’s processing capacity and India’s production volumes, while Africa is the fastest-growing region at 4.8% CAGR.
3. What are the key drivers of the tomato industry market?
Rising demand for processed tomato products (1.2% CAGR impact), expansion of greenhouse cultivation (1.0%), government incentives for horticulture (0.9%), and health-driven fresh tomato uptake (0.7%) are primary drivers.
4. What are the major challenges in the tomato industry market?
Post-harvest losses (up to 20% in developing regions), water stress and climate volatility (projected 6% global production decline by 2050), carbon-footprint scrutiny, and price volatility (up to 60% per season) are significant restraints.
5. Who are the leading companies in the tomato industry market?
Key players include The Morning Star Company, COFCO Tunhe Tomato Co. Ltd., Xinjiang Chalkis Company Ltd., Ingomar Packing Co., ConAgra Brands Inc., Olam International, Los Gatos Tomato Products, China Haohan Group Limited, Campbell Soup Company, and Toma-Tek.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70–80% of data is gathered through primary research, including interviews with C-level executives, procurement managers, and technical directors across the tomato value chain.
We conduct in-depth interviews with stakeholders such as: greenhouse operators, tomato processors, cold-chain logistics providers, and retail buyers.
On-site visits and expert panel discussions are organized to validate production and consumption estimates.
Telephonic and online surveys target a global sample of over 1,200 respondents annually, ensuring regional representation.
 Tomato Industry