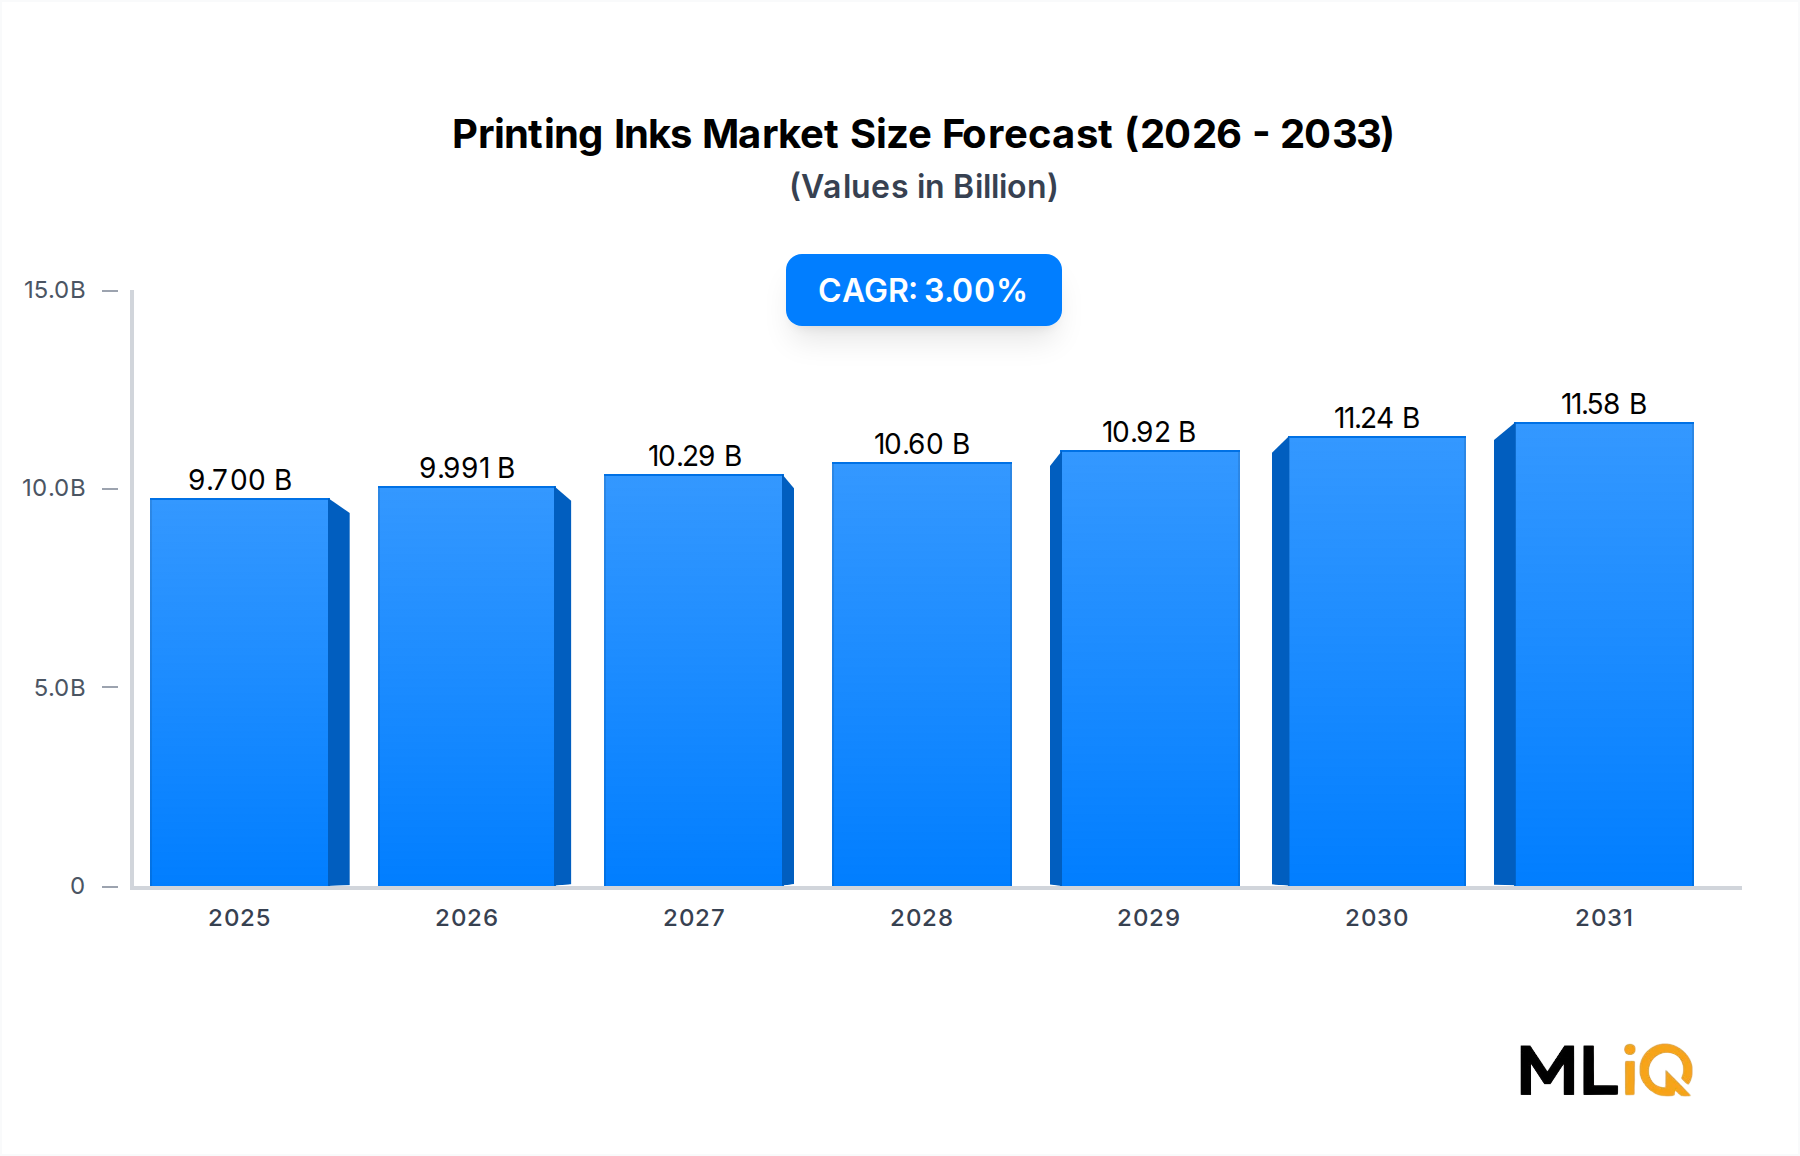
The global Printing Inks Market is valued at $9.7 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 3% through 2033, reflecting steady, sustained demand across packaging, publication, and commercial printing segments. This trajectory places the market on course to surpass $12.3 billion by 2033, underpinned by technological innovation, evolving regulatory frameworks, and shifting end-user priorities.
Several macro tailwinds are reinforcing this growth path. The global rise in e-commerce and consumer goods packaging continues to create persistent demand for high-performance inks capable of meeting both aesthetic and functional specifications. Brand differentiation requirements are pushing brand owners toward premium ink formulations that offer superior color accuracy, faster drying times, and enhanced substrate adhesion. Meanwhile, the proliferation of digital print platforms is reshaping ink consumption patterns, with water-based and UV-cured formulations gaining traction at the expense of traditional solvent-based systems.
Regulatory momentum around volatile organic compound (VOC) emissions is serving as both a driver and a disruptor. Stricter environmental norms across North America and Europe are accelerating the shift toward low-migration, bio-based, and energy-curable ink technologies. This regulatory-driven product substitution is creating incremental revenue opportunities for innovators while compressing margins for incumbents reliant on legacy solvent-based portfolios.
From a demand standpoint, packaging remains the dominant application segment, accounting for the largest share of total ink consumption globally. The surge in flexible packaging for food, pharmaceuticals, and personal care products is a primary catalyst, as brand owners and converters demand inks that comply with food-contact safety regulations without compromising print quality or production throughput.
Asia Pacific leads the market in absolute volume terms, driven by China and India's expanding manufacturing bases and rising domestic consumption. North America and Europe, while more mature, continue to generate strong revenue contributions through premiumization and the adoption of advanced digital and UV-cure ink technologies.
Key demand drivers include expansion in the fast-moving consumer goods (FMCG) sector, growth in pharmaceutical packaging requiring tamper-evident and traceable print solutions, and increasing penetration of digital textile printing. Constraints include raw material price volatility, particularly for pigments, resins, and specialty solvents, as well as margin pressure from consolidation among large printing conglomerates.
Looking ahead, the market's forward-looking outlook is constructive. Investment in sustainable ink chemistry, coupled with the digitization of commercial printing workflows, is expected to sustain above-GDP growth rates across multiple sub-segments. Companies with diversified portfolios spanning water-based, UV-cured, and digital ink platforms are best positioned to capture disproportionate share in the coming cycle.