Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Main Battle Tank Market CAGR 2.98% to Reach $8.4B by 2034
Main Battle Tank Market
Main Battle Tank Market CAGR 2.98% to Reach $8.4B by 2034
Main Battle Tank Market by Type (Light, Medium, Heavy), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Oct 3, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: Main Battle Tank Market
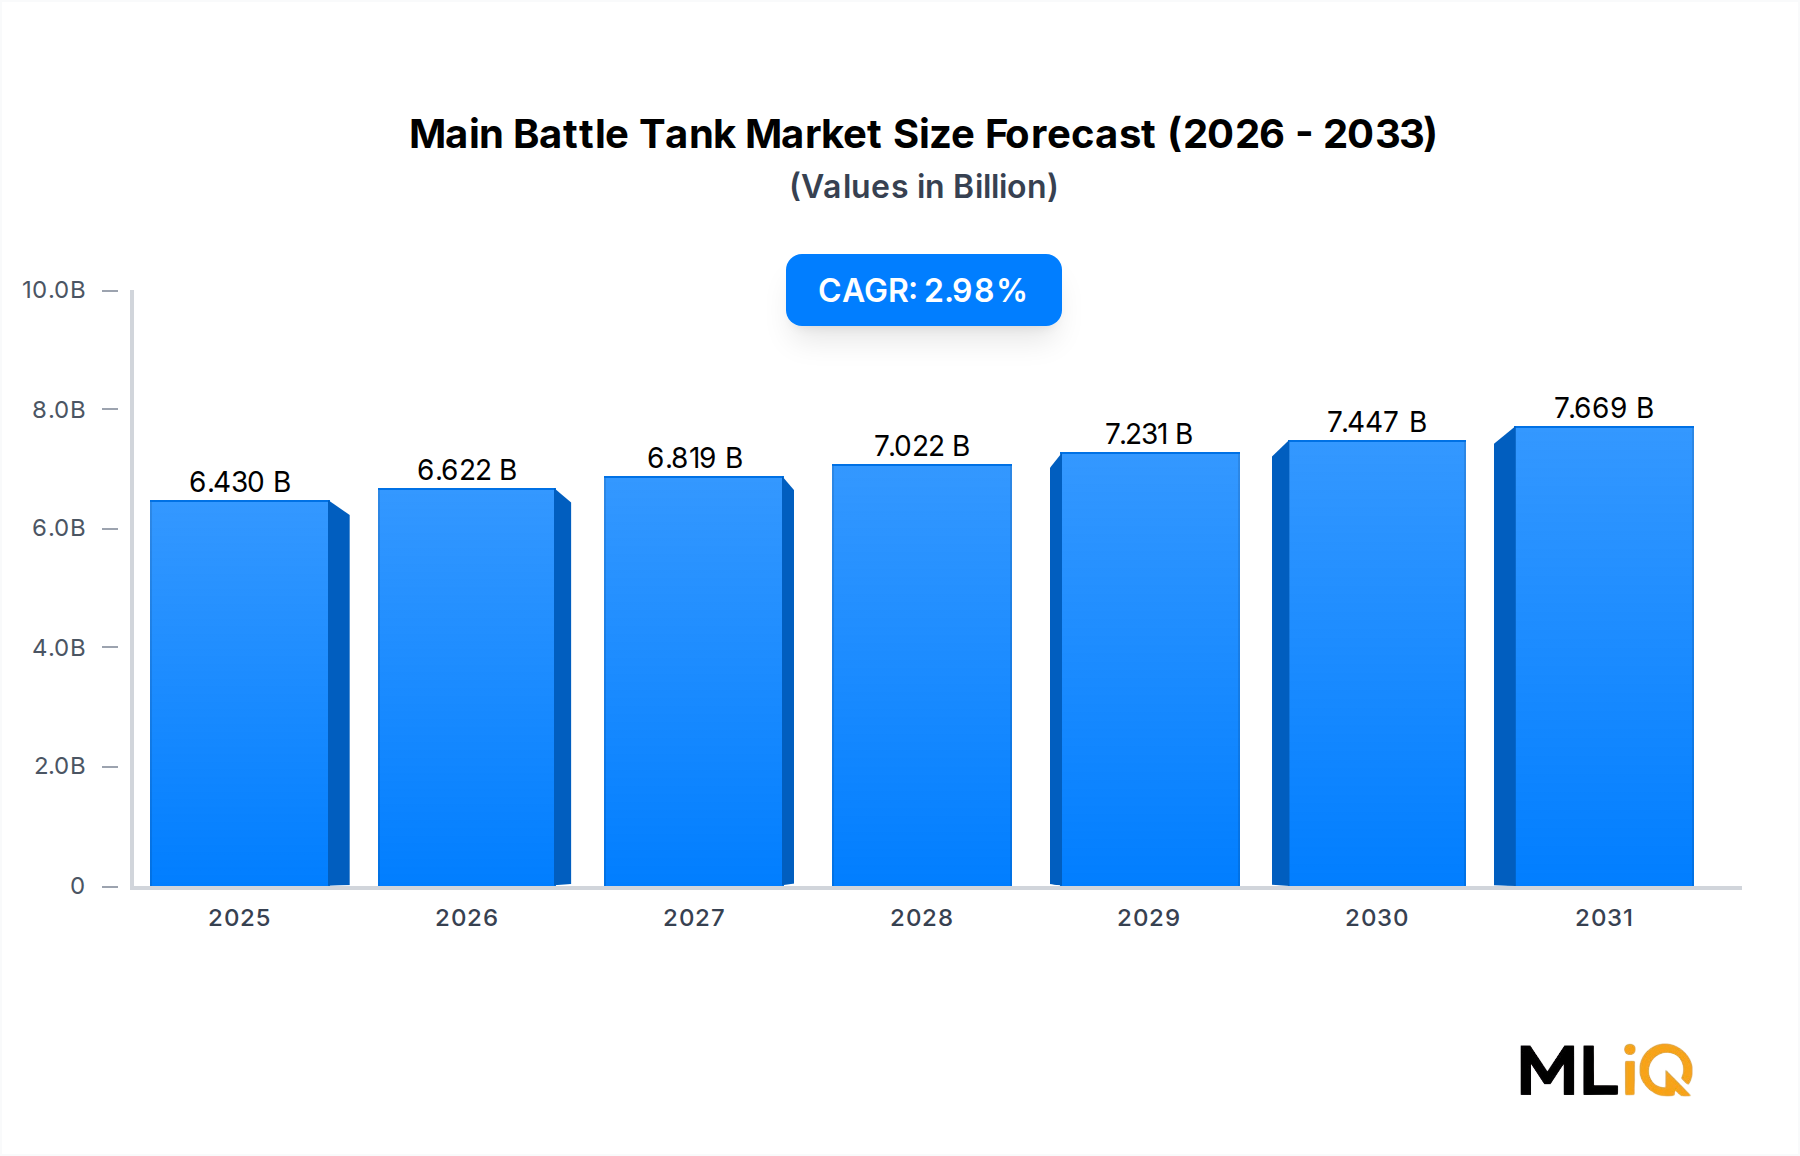
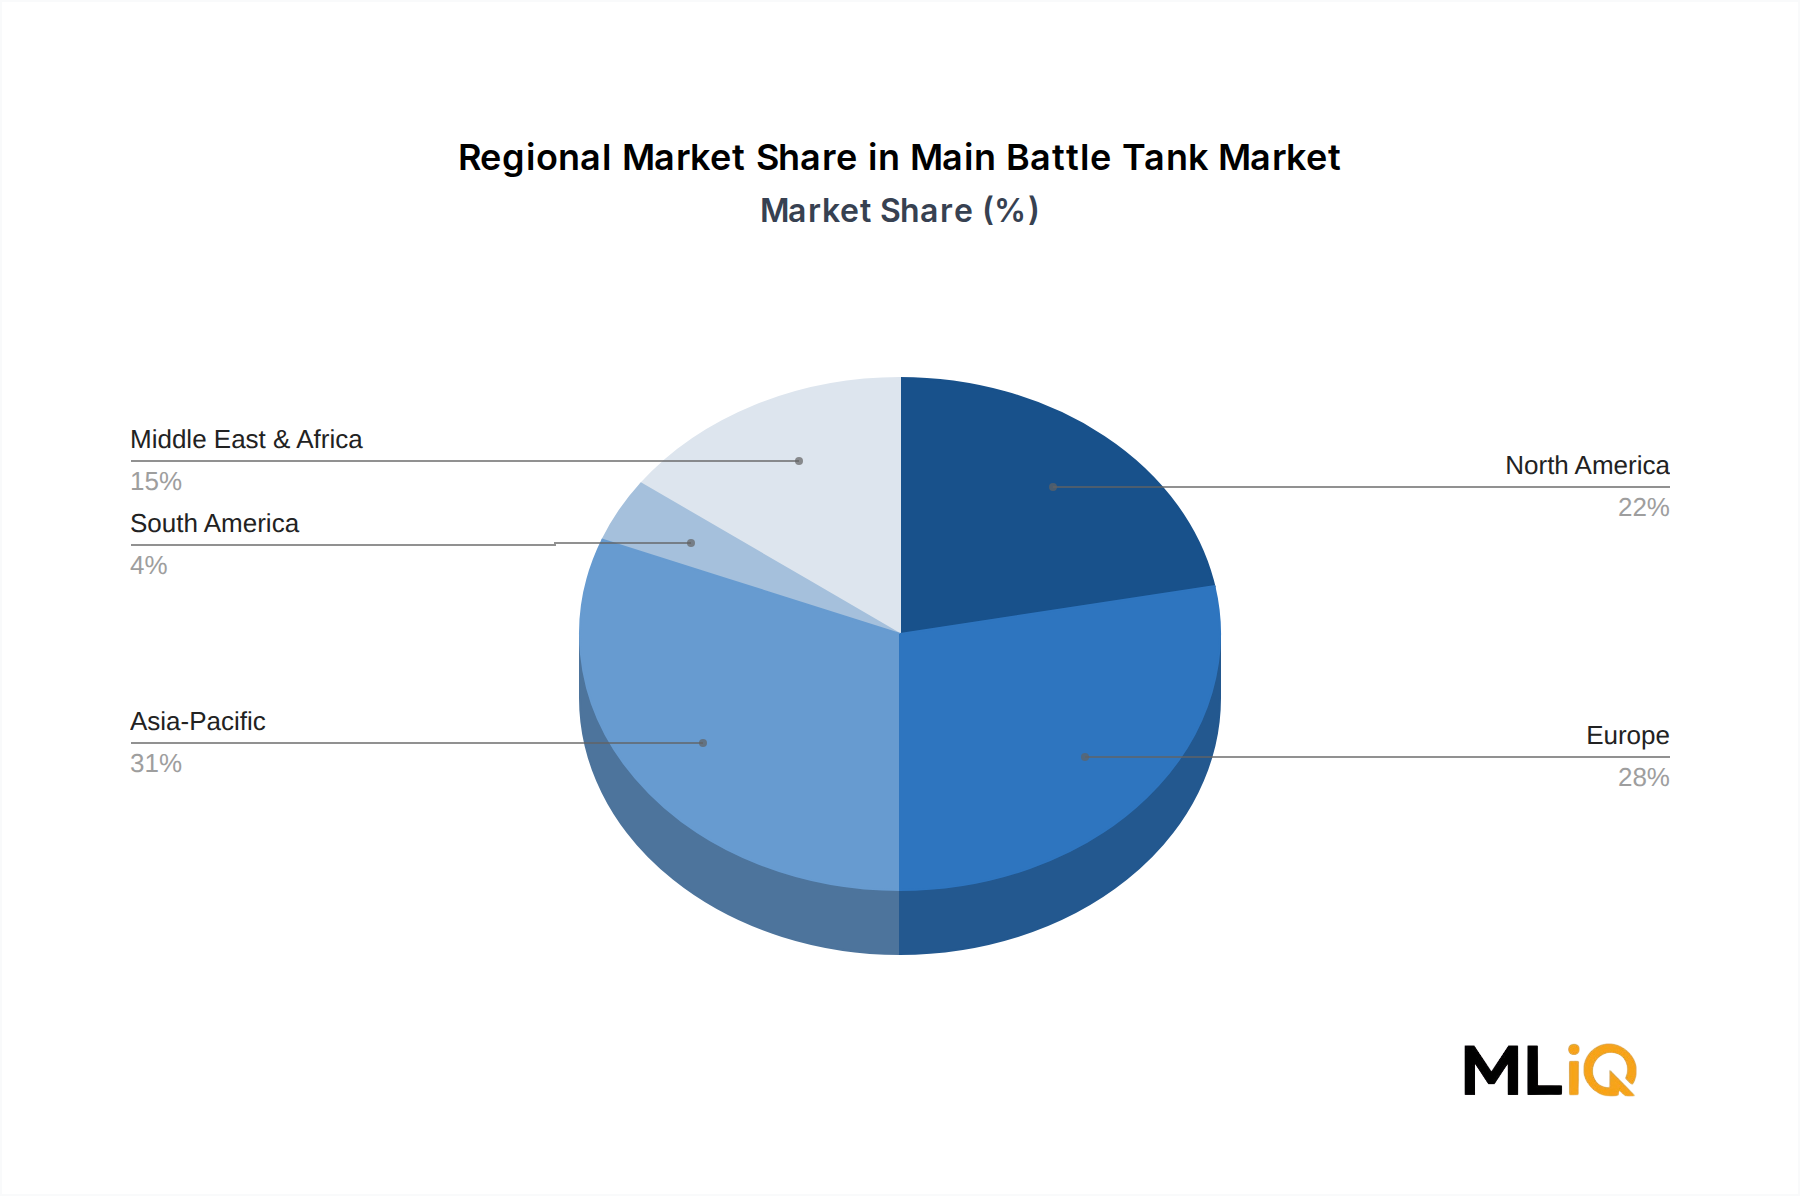
The Main Battle Tank Market is valued at $6.43 billion in 2025 and is projected to reach $8.4 billion by 2034, expanding at a 2.98% CAGR. Growth is supported by armor modernization cycles, light tank procurement, and active protection integration. Europe accounts for 31% of global value, followed by Asia-Pacific at 28%. Heavy main battle tanks generate 54% of revenue, but the Light Battle Tank Market is the fastest-growing type at 4.1% CAGR.
Main Battle Tank Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
6.430 B
2025
6.622 B
2026
6.819 B
2027
7.022 B
2028
7.231 B
2029
7.447 B
2030
7.669 B
2031
The Armored Vehicles Market remains the broader parent category, shaped by cross-border procurement and fleet sustainment. Demand is not uniform: mature fleets in North America and Western Europe are being upgraded, while Asia-Pacific and the Middle East are adding new platforms. Key vendors including General Dynamics, Rheinmetall, BAE Systems, and Hyundai Rotem are balancing domestic orders with export campaigns.
Heavy segment dominance is tied to survivability, firepower, and existing fleet sizes.
Light tank demand is rising for mountain and rapid-deployment missions.
Upgrade programs extend service life at 30-50% of new-build cost.
Export controls and industrial capacity constrain near-term delivery.
Strategic takeaway: the market is not a high-growth volume story but a value-migration story from new hulls to sensors, protection, and sustainment.
Segment Deep-Dive: Heavy Battle Tank Dominance in Main Battle Tank Market
Segment Analysis Matrix
CAGR (2025-2034)
Market Share (2025)
Key Demand Driver
Heavy
2.5%
54%
Fleet modernization and survivability upgrades
Medium
3.0%
31%
Balanced mobility and firepower for regional conflicts
Light
4.1%
15%
Mountain warfare and rapid deployment
Heavy Battle Tank Market Dynamics
The Heavy Battle Tank Market is the largest revenue pool, supported by the M1 Abrams, Leopard 2, Challenger 3, K2, and Type 10 fleets. These vehicles carry 120mm or 125mm guns, advanced composite armor, and active protection systems. Unit values range from $8 million to $12 million, with upgrade packages adding $3 million to $6 million per tank. Margin pressure comes from armor steel, composite materials, and precision electronics.
Medium and Light Segment Momentum
The Medium Battle Tank Market occupies a middle ground, with platforms such as the T-90, Leclerc, and Altay. Demand is strongest in Turkey, India, and parts of the Middle East, where mobility and cost are balanced. The Light Battle Tank Market is the fastest-growing category, driven by India's 350-unit light tank contract and similar programs in China and the United States. Light tanks weigh 25-35 tonnes, enabling airlift and high-altitude operations.
Light: fastest CAGR, lower unit cost, mountain and urban roles.
The Armored Steel Market and Composite Armor Materials Market are critical upstream inputs. Armor steel demand is tied to hull production and spall liners, while composite armor materials support weight reduction. The Active Protection Systems Market is also expanding as armies retrofit Trophy, Iron Fist, and similar systems onto existing heavy fleets. This shifts value from hull manufacturers to electronics and protection suppliers.
Primary Market Drivers & Growth Restraints in Main Battle Tank Market
Armored steel and composite material supply bottlenecks
Medium
Short term
Quantitative catalysts include Italy's EUR 8.2 billion plan for 132 Leopard 2A8IT tanks, India's USD 1.9 billion contract for 350 light battle tanks, and the UK's USD 1.3 billion Challenger 3 upgrade for 148 vehicles. These programs show that demand is concentrated in Europe and Asia-Pacific. The Military Thermal Imaging Market is a direct beneficiary because thermal sights, commander sights, and fire-control systems are upgraded alongside armor. The Active Protection Systems Market is another adjacent growth area, with retrofit rates rising on Abrams and Leopard 2 fleets. The Armored Vehicle Upgrade Market is a key adjacent segment, as armies extend service life rather than procuring new hulls.
Restraints are primarily fiscal and industrial. A new heavy MBT takes 5-7 years from contract to delivery, and export approvals can add 12-24 months. Armor steel capacity is limited to a few mills in Europe, Asia, and North America. Composite armor materials face similar constraints because qualified suppliers must meet military specifications. These bottlenecks protect incumbents but slow fleet renewal.
High-impact driver: European defense budgets above 2% of GDP.
High-impact restraint: unit cost inflation for armor, engines, and optics.
Medium-impact driver: upgrade market for active protection and thermal imaging.
Competitive Ecosystem & Key Vendor Profiles: Main Battle Tank Market
Vendor Benchmarking Matrix
Core Strength
Target Audience
Market Position
General Dynamics Corporation
M1 Abrams and systems integration
U.S. Army, allied nations
Leader
BAE Systems plc
Challenger 3 and armored vehicles
UK, international
Leader
Rheinmetall AG
Leopard 2, guns, ammunition
Germany, NATO
Leader
Hyundai Rotem Co
K2 Black Panther
South Korea, Poland
Challenger
Nexter Group KNDS
Leclerc and Leopard components
France, Europe
Challenger
BMC
Altay MBT
Turkey
Niche
Israel Military Industries
Merkava and armor systems
Israel
Niche
Mitsubishi Heavy Industries Ltd
Type 10 MBT
Japan
Niche
Norinco Private Limited
VT-4 and Type 99
China, export markets
Challenger
DRDO
Arjun MBT
India
Niche
Rostec
T-90 and Armata
Russia
Leader
General Dynamics Corporation: produces the M1 Abrams and leads U.S. armor modernization, including SEPv3 and future AbramsX concepts.
BAE Systems plc: manages the Challenger 3 upgrade and supplies armored vehicle subsystems across NATO.
Hyundai Rotem Co: exports the K2 to Poland and positions South Korea as a fast-delivery alternative.
Nexter Group KNDS: integrates French and German armor industrial assets, including Leclerc upgrades.
BMC: develops the Altay for Turkey and targets regional export opportunities.
Israel Military Industries: supplies Merkava armor and active protection technologies.
Mitsubishi Heavy Industries Ltd: builds the Type 10 for Japan's defensive requirements.
Norinco Private Limited: offers VT-4 and Type 99 variants at lower price points for export customers.
DRDO: leads India's Arjun program and supports indigenous armor supply chains.
Rostec: remains a major Russian producer, though sanctions limit export reach.
Strategic Milestones & Recent Developments in Main Battle Tank Market
Latest Strategic Moves
Company/Country
Event Type
Impact
February 2024
Italy / KNDS
Procurement
EUR 8.2 billion for 132 Leopard 2A8IT tanks over 14 years
March 2022
India
Contract
USD 1.9 billion for 350 light battle tanks
March 2022
UK / BAE Systems
Upgrade
USD 1.3 billion for 148 Challenger 3 tanks
February 2024: Italy approved the acquisition of 132 Leopard 2A8IT main battle tanks for EUR 8.2 billion, with a program timeline near 14 years. This is one of Europe's largest recent armor orders.
March 2022: India signed a USD 1.9 billion contract for 350 light battle tanks to address mountain warfare limitations. The program reflects a shift toward lighter, air-transportable armor.
March 2022: The British Army began the Challenger 3 upgrade, converting 148 Challenger 2 tanks at a cost near USD 1.3 billion. These vehicles are expected to remain in service until at least 2040.
Regional Market Analysis & Growth Corridors for Main Battle Tank Market
Regional Growth Comparison
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
2.2%
$1.54 billion
Abrams upgrades and DSCA exports
High
Europe
3.4%
$1.99 billion
Leopard 2, Challenger 3, and NATO rearmament
High
Asia-Pacific
3.6%
$1.80 billion
India, China, and South Korea programs
Medium
LAMEA
2.7%
$1.10 billion
Turkey, Israel, and GCC demand
Medium
Europe is the largest regional market at $1.99 billion in 2025, supported by NATO spending and the Leopard 2A8IT order. Asia-Pacific is the fastest-growing region at 3.6% CAGR, driven by India's light tank program, China's Type 99 production, and South Korea's K2 exports. North America remains mature but technologically advanced, with Abrams upgrades and foreign military sales.
Fastest-growing: Asia-Pacific, led by India and South Korea.
Most mature: North America, with upgrade-led demand.
Value-dense: Europe, where unit prices and protection requirements are highest.
Emerging: Middle East & Africa, especially Turkey and GCC states.
The Armored Vehicles Market in LAMEA is shaped by Turkey's Altay program and Israel's Merkava fleet. In South America, budgets remain limited, with Brazil and Chile favoring wheeled armored vehicles over heavy MBTs. Regulatory stringency is highest in North America and Europe, where export controls, offsets, and local assembly requirements influence vendor selection.
Pricing Dynamics, Cost Structures & Margin Pressure in Main Battle Tank Market
Average selling prices for new main battle tanks range from $8 million to $12 million per unit, while full programs with spares, training, and support can exceed $20 million per vehicle. Italy's Leopard 2A8IT package implies a program-level unit cost near EUR 62 million, including infrastructure and long-term support. Upgrade programs such as Challenger 3 cost roughly $8.8 million per tank, still below new-build prices.
Cost structure for a modern MBT:
Cost Category
Estimated Share
Armor steel and composite materials
30%
Engine and transmission
15%
Fire control and thermal optics
20%
Armament and ammunition handling
10%
Labor and assembly
15%
Other systems and logistics
10%
The Armored Steel Market and Composite Armor Materials Market are critical cost drivers, with specialty alloys and ceramics subject to long lead times. The Military Thermal Imaging Market adds $1-2 million per vehicle for advanced sights. Margin pressure is intense for hull manufacturers, but suppliers of active protection and thermal imaging retain stronger pricing power. Vendors use escalation clauses and multi-year contracts to manage inflation.
Export, Cross-Border Trade & Tariff Impact on Main Battle Tank Market
Major trade corridors include Germany and South Korea to European NATO members, the United States to GCC states, China to Pakistan, and Russia to legacy customers. The largest net exporters are the United States, Germany, South Korea, and China. Key importers include Poland, India, Egypt, Saudi Arabia, and Australia. Poland's K2 and Abrams orders illustrate how geopolitical alignment drives cross-border shipments.
Tariff and non-tariff barriers remain significant. ITAR and EU dual-use controls add 6-18 months to export approvals, while offset requirements can raise local content to 30-50%. The Armored Vehicle Upgrade Market is less exposed to tariffs because sensors, armor kits, and fire-control systems often move under government-to-government channels. However, steel and composite material tariffs can increase subsystem costs by 5-10%.
Net exporters: United States, Germany, South Korea, China.
Net importers: Poland, India, Egypt, Saudi Arabia.
Barrier: ITAR, EU export controls, and local content mandates.
Opportunity: upgrade kits and active protection retrofits bypass some new-build trade restrictions.
Main Battle Tank Market Segmentation
1. Type
1.1. Light
1.2. Medium
1.3. Heavy
Main Battle Tank Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Main Battle Tank Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 2.98% from 2020-2034
Segmentation
By Type
Light
Medium
Heavy
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Light
5.1.2. Medium
5.1.3. Heavy
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Light
6.1.2. Medium
6.1.3. Heavy
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Light
7.1.2. Medium
7.1.3. Heavy
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Light
8.1.2. Medium
8.1.3. Heavy
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Light
9.1.2. Medium
9.1.3. Heavy
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Light
10.1.2. Medium
10.1.3. Heavy
11. Competitive Analysis
11.1. Company Profiles
11.1.1. General Dynamics Corporation
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. BAE Systems plc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. BMC
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Hyundai Rotem Co
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Nexter group KNDS
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Rheinmetall AG
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Israel Military Industries
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Mitsubishi Heavy Industries Ltd
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Norinco Private Limited
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. DRDO
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Roste
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Main Battle Tank Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Main Battle Tank Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Main Battle Tank Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Main Battle Tank Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Main Battle Tank Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Main Battle Tank Market Revenue (billion), by Type 2026 & 2034
Figure 7: South America Main Battle Tank Market Revenue Share (%), by Type 2026 & 2034
Figure 8: South America Main Battle Tank Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Main Battle Tank Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Main Battle Tank Market Revenue (billion), by Type 2026 & 2034
Figure 11: Europe Main Battle Tank Market Revenue Share (%), by Type 2026 & 2034
Figure 12: Europe Main Battle Tank Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Main Battle Tank Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Main Battle Tank Market Revenue (billion), by Type 2026 & 2034
Figure 15: Middle East & Africa Main Battle Tank Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Middle East & Africa Main Battle Tank Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Main Battle Tank Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Main Battle Tank Market Revenue (billion), by Type 2026 & 2034
Figure 19: Asia Pacific Main Battle Tank Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Asia Pacific Main Battle Tank Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Main Battle Tank Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Main Battle Tank Market Revenue billion Forecast, by Type 2020 & 2034
Table 2: Main Battle Tank Market Revenue billion Forecast, by Region 2020 & 2034
Table 3: North America Main Battle Tank Market Revenue billion Forecast, by Type 2020 & 2034
Table 4: North America Main Battle Tank Market Revenue billion Forecast, by Country 2020 & 2034
Table 5: United States Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 6: Canada Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 7: Mexico Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 8: South America Main Battle Tank Market Revenue billion Forecast, by Type 2020 & 2034
Table 9: South America Main Battle Tank Market Revenue billion Forecast, by Country 2020 & 2034
Table 10: Brazil Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Argentina Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: Rest of South America Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 13: Europe Main Battle Tank Market Revenue billion Forecast, by Type 2020 & 2034
Table 14: Europe Main Battle Tank Market Revenue billion Forecast, by Country 2020 & 2034
Table 15: United Kingdom Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: Germany Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: France Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Italy Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Spain Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 20: Russia Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 21: Benelux Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 22: Nordics Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 23: Rest of Europe Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Middle East & Africa Main Battle Tank Market Revenue billion Forecast, by Type 2020 & 2034
Table 25: Middle East & Africa Main Battle Tank Market Revenue billion Forecast, by Country 2020 & 2034
Table 26: Turkey Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Israel Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: GCC Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: North Africa Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: South Africa Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Middle East & Africa Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Asia Pacific Main Battle Tank Market Revenue billion Forecast, by Type 2020 & 2034
Table 33: Asia Pacific Main Battle Tank Market Revenue billion Forecast, by Country 2020 & 2034
Table 34: China Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: India Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Japan Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: South Korea Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: ASEAN Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: Oceania Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Rest of Asia Pacific Main Battle Tank Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of total effort, covering interviews with MBT hull and turret integrators, fire-control and sensor suppliers, 120mm/125mm gun and autoloader manufacturers, active protection system producers, and track, suspension, and powertrain subsystem suppliers.
We interview stakeholder titles including Armored Vehicle Program Manager, Defense Procurement Director, Land Systems Chief Engineer, and MBT Sustainment and Upgrades Lead.
Interviews validate procurement timelines, unit pricing, fleet modernization rates, and platform-specific requirements across light, medium, and heavy tanks.
Association and regulatory inputs come from the U.S. Defense Security Cooperation Agency (DSCA), European Defence Agency (EDA), National Defense Industrial Association (NDIA), Aerospace Industries Association (AIA), and SIPRI.
Every report is updated to the date of purchase, with primary call notes and interview summaries refreshed on delivery.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Armored Vehicle Program Managers
35%
Defense Procurement Directors
25%
Land Systems Chief Engineers
22%
MBT Sustainment & Upgrades Leads
18%
Industry Ecosystem Breakdown
Company Type
Representation (%)
MBT Hull & Turret Integrators
30%
Fire Control & Sensor Suppliers
20%
Gun & Armament Manufacturers
18%
Armor & Protection System Providers
17%
Powertrain & Mobility Subsystem Suppliers
15%
Secondary Research & Industry Benchmarking
Secondary research represents 20-30% of the research mix and draws on financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Company filings, annual reports, export license records, and parliamentary budget documents are used to benchmark order values and delivery schedules.
No market research websites are cited as primary sources; all third-party estimates are cross-checked against original procurement notices and .gov, .org, and trade association data.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up market sizing uses quantitative metrics including number of active MBTs per country, annual procurement budget per armored brigade, average tank unit price per variant, fleet modernization rate, and light tank procurement volumes.
Top-down sizing cross-references national defense budgets, armor share of land systems spending, and known platform orders such as Italy's 132 Leopard 2A8IT and India's 350 light tanks.
Segment splits are built by type (light, medium, heavy) and by region using country-level fleet inventories and delivery schedules.
Forecasts from 2025 to 2034 apply platform-level replacement cycles, upgrade rates, and export approvals to derive annual value.
Data Accuracy & Quality Check
Each report targets a guaranteed estimated data accuracy level of 85-90%.
Primary interview transcripts are compared with secondary procurement records, and outliers are re-verified with at least two independent sources.
Multi-level data triangulation combines manufacturer data, government budgets, trade association reports, and country-level fleet inventories.
All market values are normalized to 2025 USD unless otherwise stated, and currency conversions use period-average exchange rates.
Every report is updated to the date of purchase, ensuring the latest contract awards, budget revisions, and export approvals are reflected.
Frequently Asked Questions
1. What are the main barriers to entry and competitive moats in the Main Battle Tank Market?
Barriers include multi-year procurement cycles, export licenses, and proprietary armor and fire-control integration. Incumbents such as General Dynamics and Rheinmetall hold moats through established supply chains, government relationships, and tested vehicle platforms. A new entrant typically needs 8-12 years to field a competitive MBT and pass NATO or national qualification trials.
2. Which disruptive technologies and emerging substitutes could reshape the Main Battle Tank Market?
Active protection systems, drone swarms, loitering munitions, and uncrewed ground vehicles are altering MBT survivability and cost equations. The Active Protection Systems Market is growing as armies retrofit Trophy and Iron Fist on Abrams and Leopard 2 fleets. Electric drive and hybrid powertrains may also reduce fuel logistics, though they remain at prototype stage for 50-60 tonne vehicles.
3. How did the Main Battle Tank Market recover after the pandemic and what structural shifts persist?
After 2020-2021 delays, defense budgets rebounded and orders accelerated from 2022 onward. European nations committed over $50 billion to armor modernization after February 2022, while supply chains for armor steel and composite materials remain constrained. Structural shifts include multi-year framework contracts, local assembly mandates, and faster upgrade cycles rather than clean-sheet tank designs.
4. Which region is the fastest-growing in the Main Battle Tank Market and where are emerging geographic opportunities?
Asia-Pacific is the fastest-growing region at 3.6% CAGR, led by India, China, and South Korea. India's USD 1.9 billion light tank program and South Korea's K2 exports to Poland create adjacent opportunities. Middle East demand from Turkey and GCC states also supports higher-than-average unit values.
5. What are the pricing trends and cost structure dynamics in the Main Battle Tank Market?
Average unit prices for new MBTs range from $8 million to $12 million, while full packages with training, spares, and support can exceed $20 million. Armored steel, composite armor, engines, and thermal optics account for roughly 60-70% of vehicle cost. Inflation in specialty alloys and electronics has pressured margins, pushing vendors toward fixed-price escalation clauses.
6. How do sustainability, ESG, and environmental factors affect the Main Battle Tank Market?
Defense ESG reporting focuses on emissions from vehicle fleets, hazardous materials in armor and ammunition, and supplier labor standards. Hybrid-electric drive demonstrators aim to cut fuel consumption by 20-30% versus current diesel MBTs. Procurement rules in the EU and NATO increasingly require lifecycle environmental impact assessments, though national security exemptions limit disclosure.