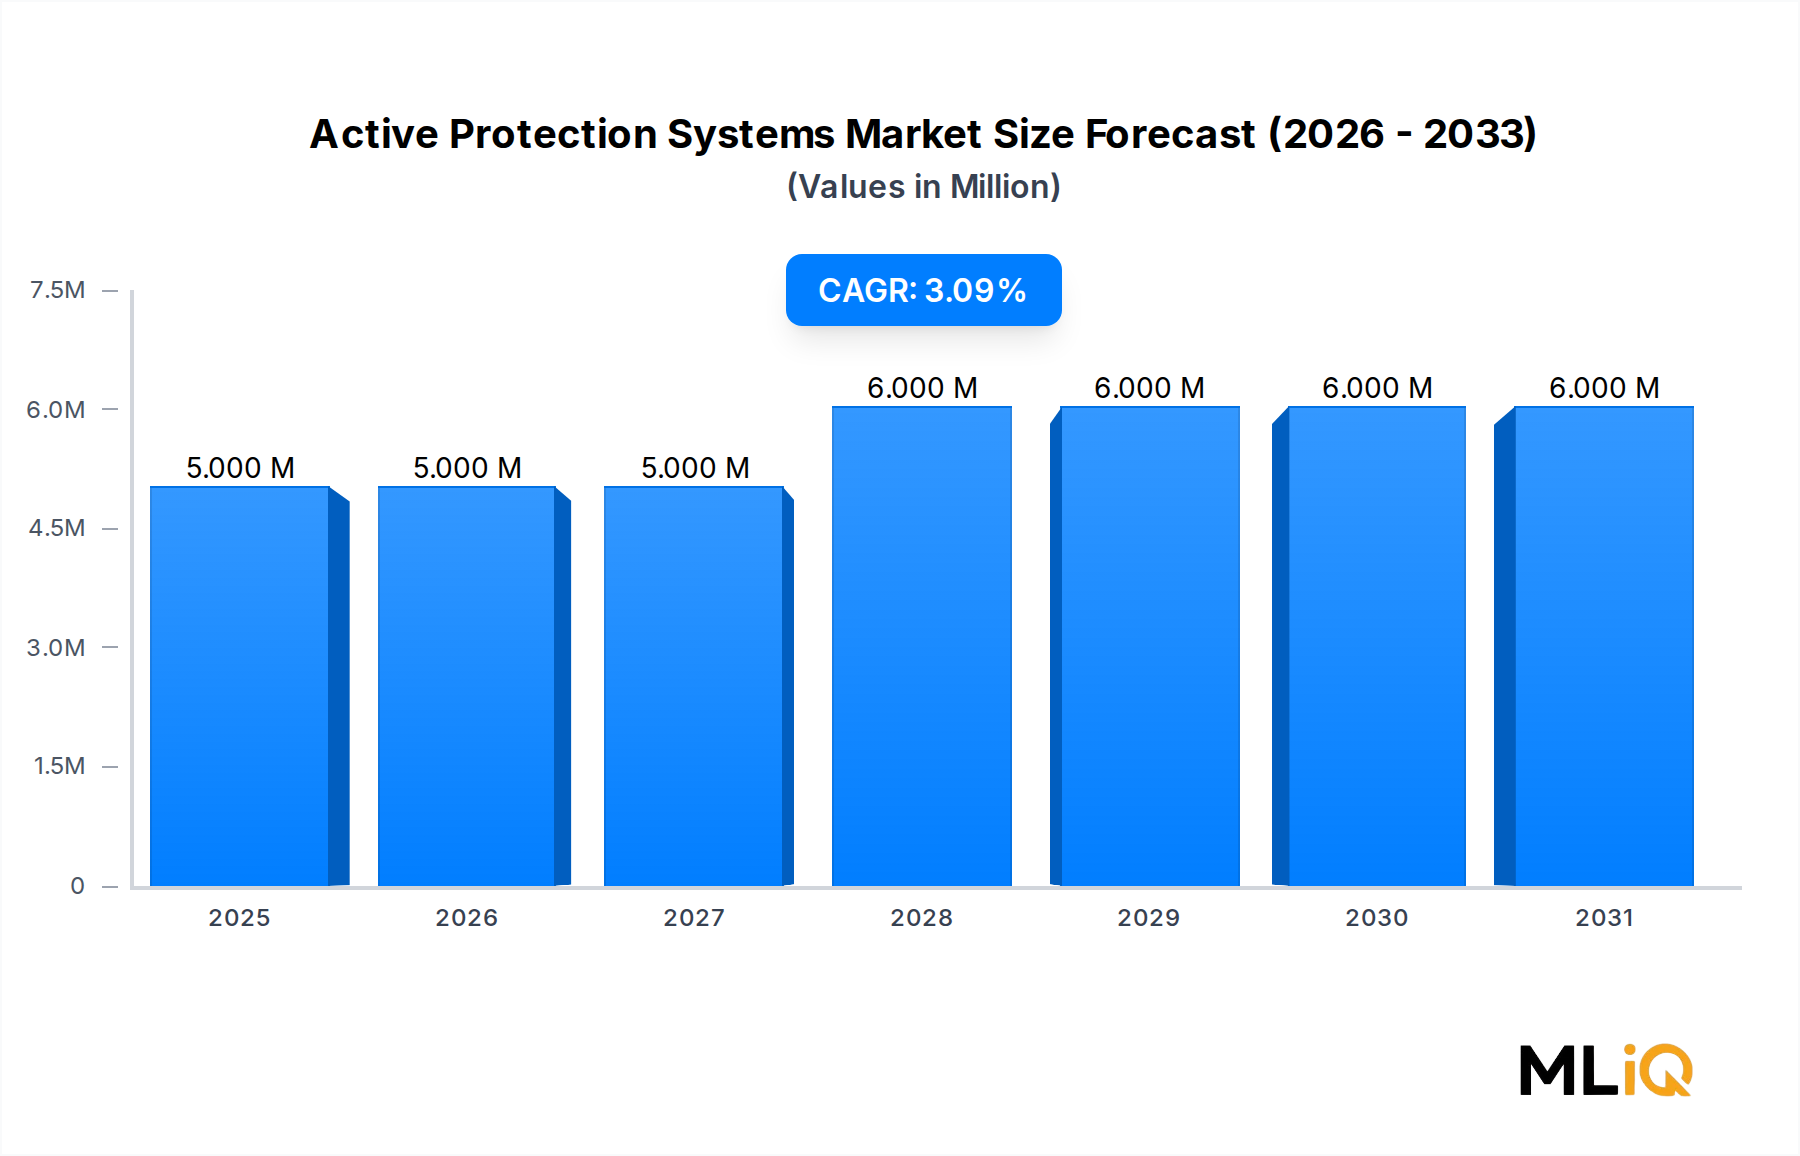
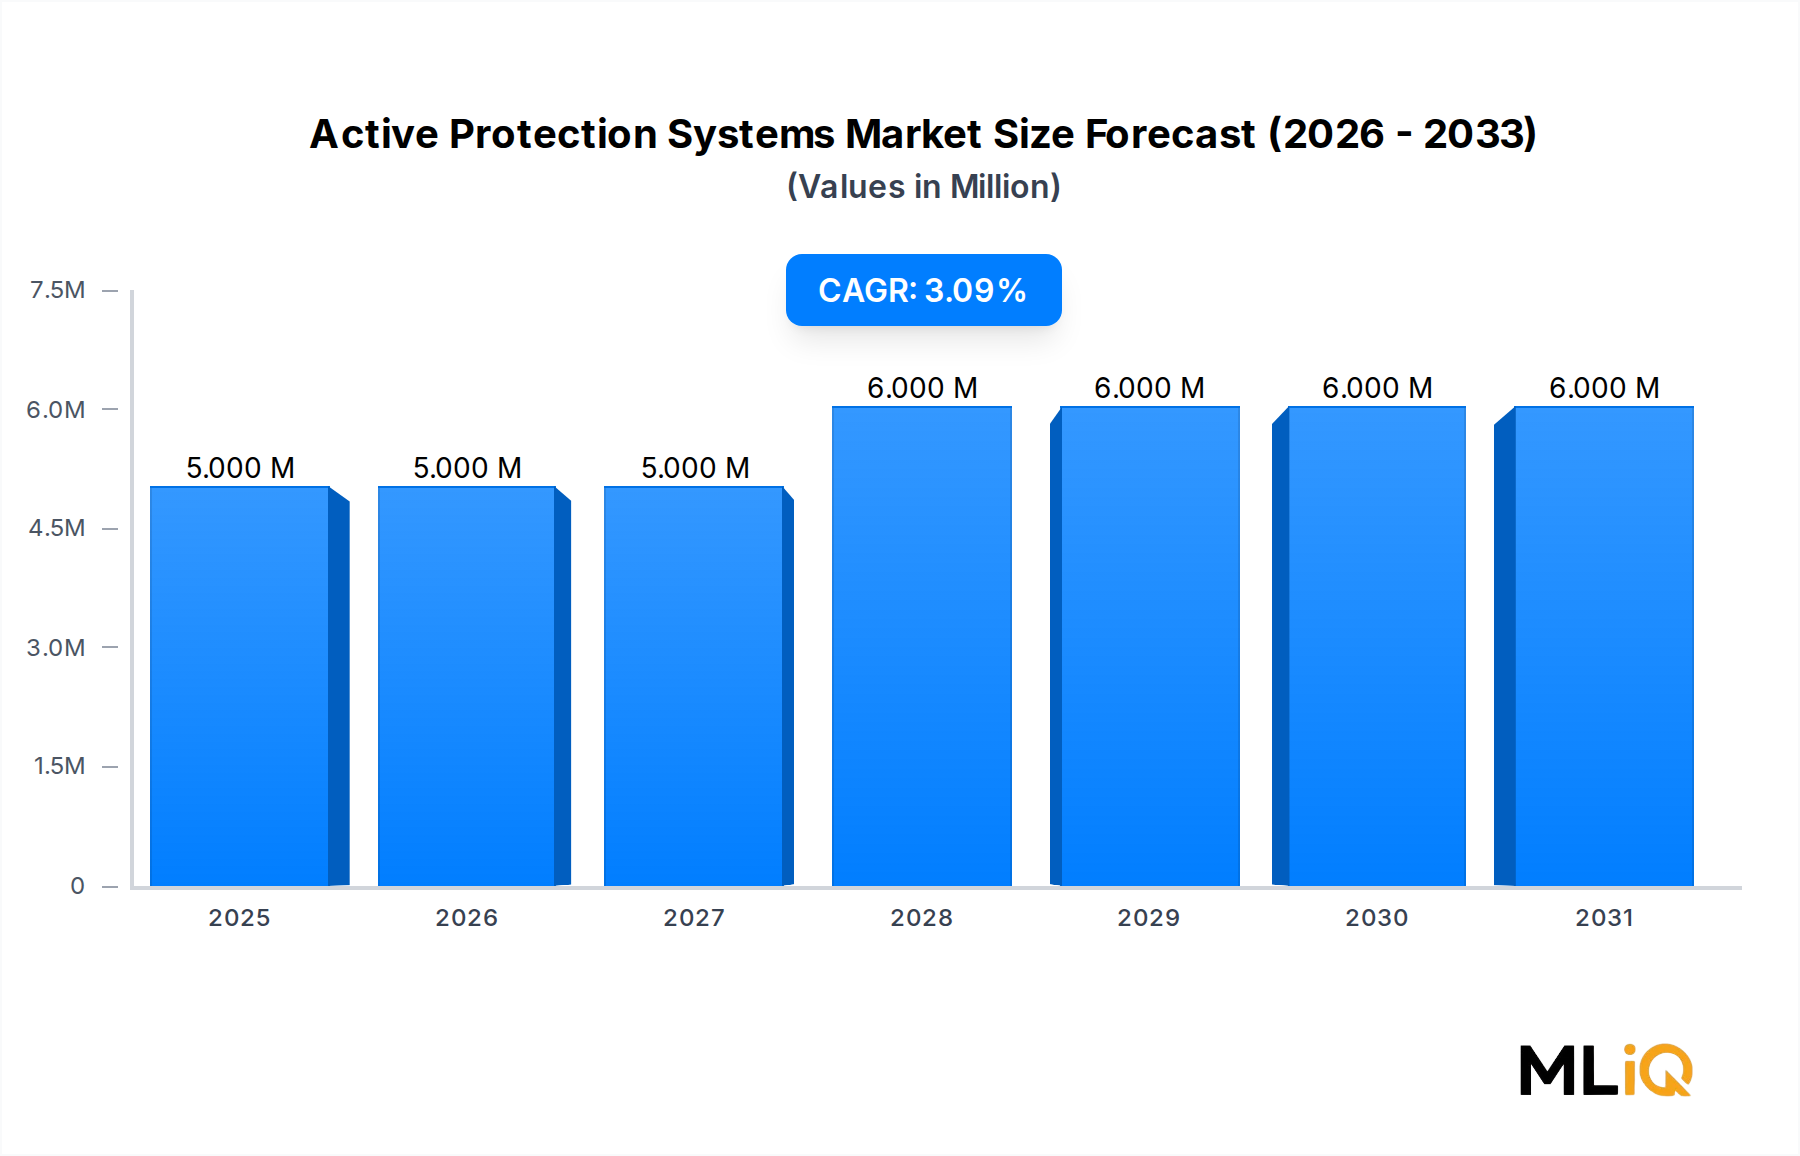
The global Active Protection Systems Market is valued at $4.67 billion as of the base assessment period and is projected to expand at a compound annual growth rate (CAGR) of 5.62% through the forecast horizon of 2025–2033. This sustained growth trajectory reflects intensifying geopolitical instability, accelerated defense modernization programs across NATO and Indo-Pacific alliance structures, and the battlefield-proven necessity of active countermeasure platforms on land and sea.
Active protection systems (APS) are designed to detect, track, and neutralize incoming threats — including rocket-propelled grenades, anti-tank guided missiles, and projectiles — before they reach the protected platform. The dual-modality architecture of hard-kill and soft-kill solutions gives defense procurement agencies significant operational flexibility, which is a core reason this market commands sustained government investment.
Key demand drivers include the sharp rise in asymmetric warfare engagements globally, the proliferation of precision-guided munitions among state and non-state actors, and the increasing budgetary allocations toward armored vehicle survivability. NATO member states collectively increased defense spending to a combined total exceeding $1.26 trillion in 2023, with a meaningful share directed toward platform protection upgrades. The United States, Germany, and Poland have each issued multi-year procurement frameworks explicitly covering active protection integration onto legacy and next-generation armored fleets.
On the technology side, sensor miniaturization, AI-driven threat classification algorithms, and lower-latency intercept mechanisms are compressing system reaction times while simultaneously reducing collateral suppression radii — a critical metric for urban combat applicability. These advances are enabling APS adoption not only on main battle tanks but also on infantry fighting vehicles, wheeled armored personnel carriers, and naval surface combatants.
The market is also benefiting from macro tailwinds in the broader Aerospace and Defense Market, where global procurement cycles are lengthening and unit contract values are escalating. The Russia-Ukraine conflict has served as a live-fire validation environment, demonstrating both the efficacy and the limitations of fielded APS solutions, driving urgent retrofit demand across European theater nations.
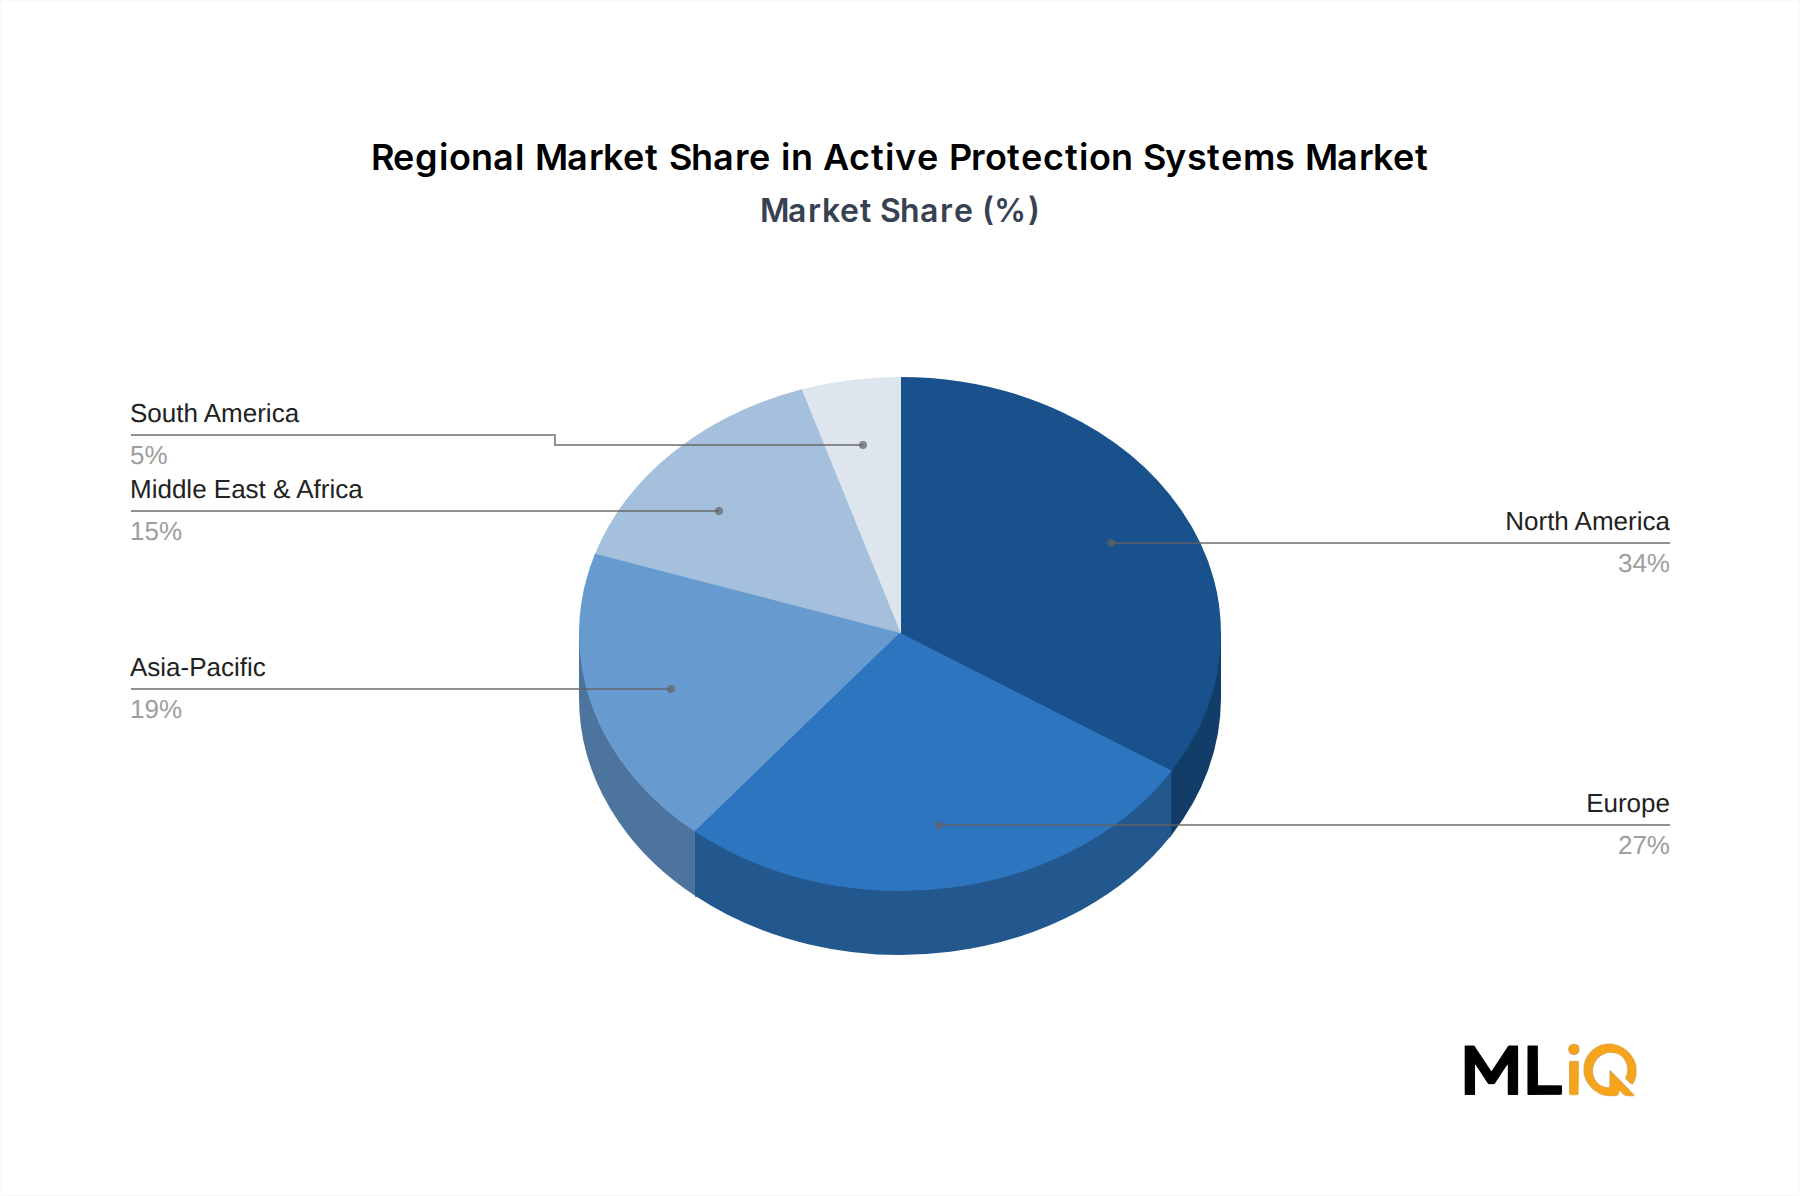
Looking forward through 2033, the market is expected to breach the $7.5 billion threshold, underpinned by expanded naval APS deployment, growing interest from Asia Pacific defense establishments, and the integration of directed energy intercept modules as complementary subsystems. Supply chain normalization post-COVID, combined with increased domestic production incentives in the United States and European Union, is expected to reduce lead times and support volume scaling. The competitive ecosystem remains moderately consolidated, with a small number of primes commanding large contract shares while a growing tier of specialized integrators contests niche platform categories.