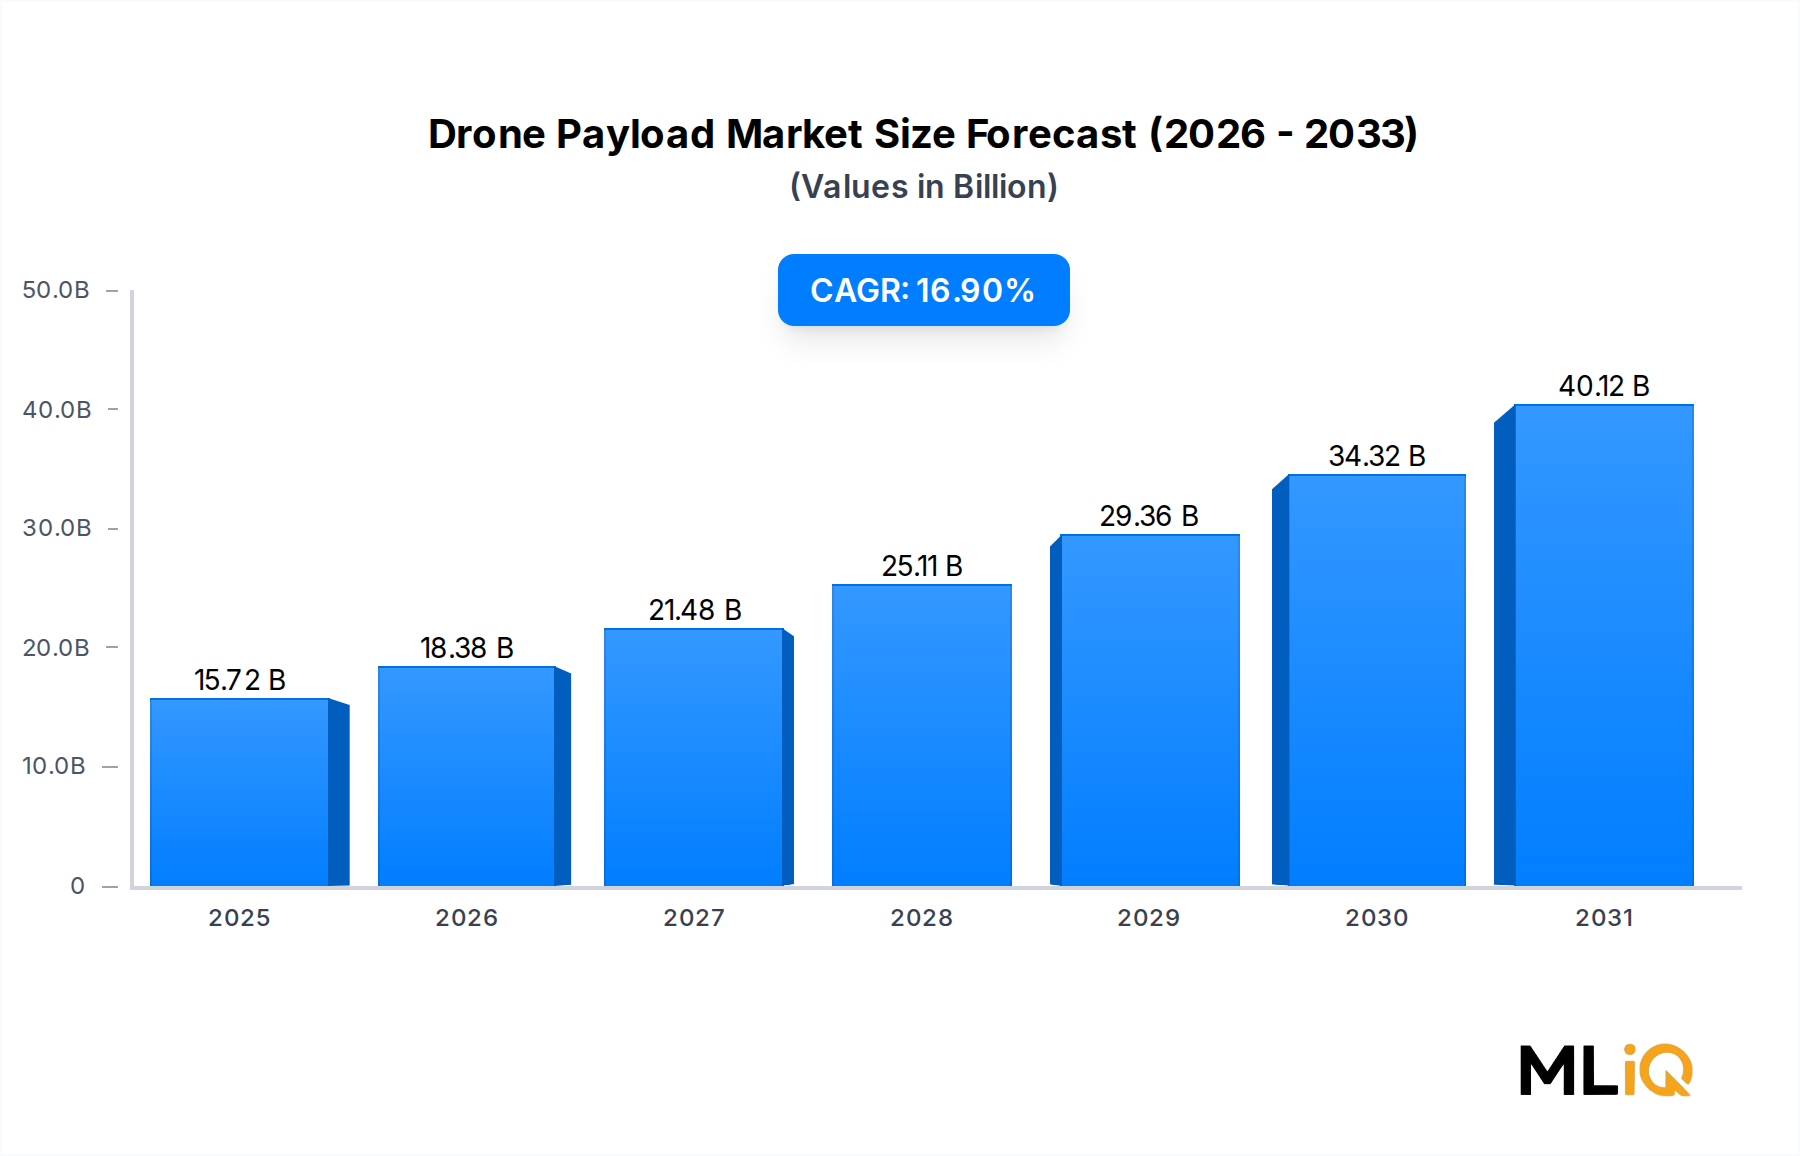
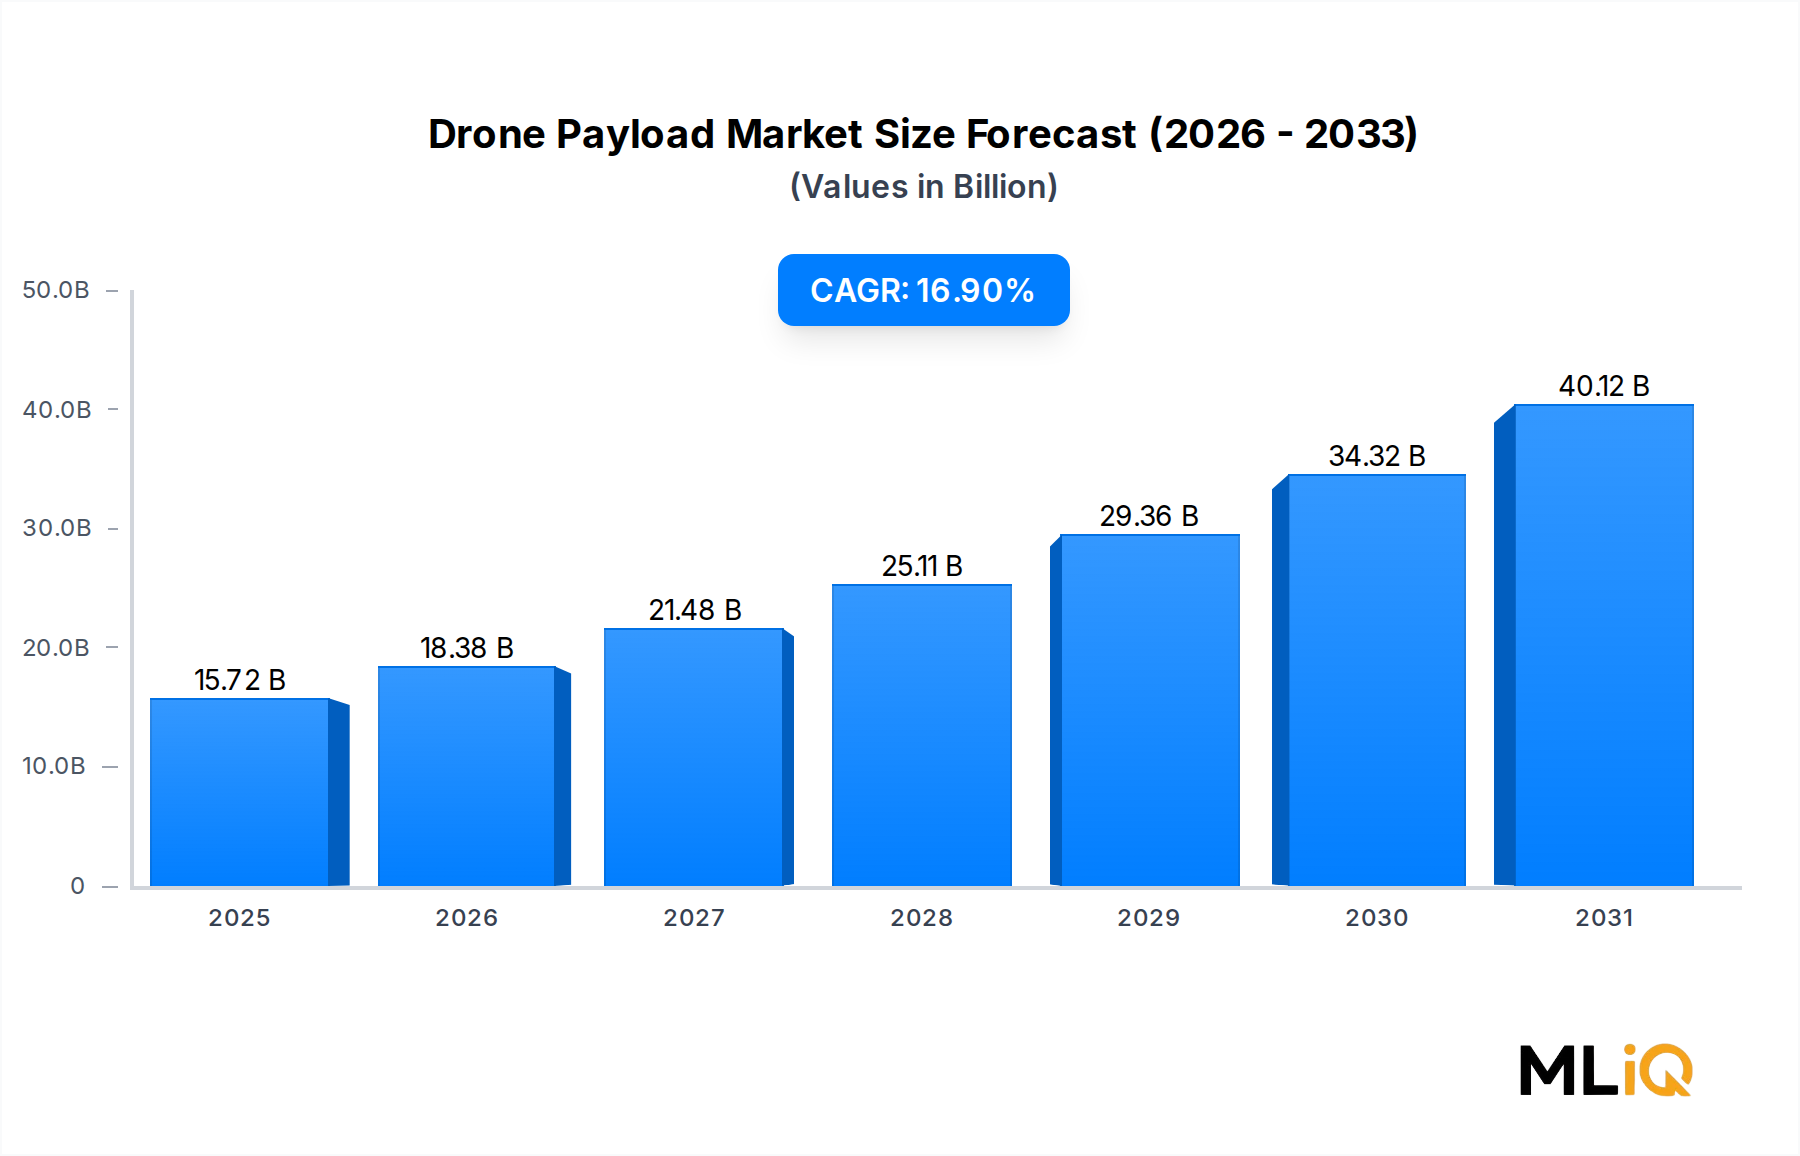
The global Drone Payload Market is positioned at the forefront of one of the most dynamic growth trajectories in the aerospace and defense industry. Valued at $15.72 billion in the base year, the market is forecast to expand at a compound annual growth rate of 16.9% through 2033, reflecting intense demand from both defense establishments and commercial operators worldwide. This growth pace significantly outstrips the broader aerospace sector average, underscoring the transformative role drone payload technologies are playing across multiple verticals.
The fundamental demand drivers coalescing behind this market are multifaceted. First, rising geopolitical tensions across Eastern Europe, the Middle East, and the Indo-Pacific region are accelerating procurement budgets for intelligence, surveillance, and reconnaissance (ISR) payloads, including electro-optical, infrared, synthetic aperture radar (SAR), and signals intelligence (SIGINT) systems. Second, the democratization of drone technology has unleashed a wave of commercial applications in agriculture, energy infrastructure inspection, construction monitoring, and media production, each requiring specialized payload configurations. Third, ongoing miniaturization of sensor technologies and advances in edge computing are enabling lighter, more capable payloads that can be integrated onto smaller unmanned platforms, lowering operational costs and broadening the addressable user base.
From a macro-level perspective, government defense budgets in NATO member states have collectively increased by meaningful margins following geopolitical realignments post-2022, directing significant capital toward drone modernization programs. Simultaneously, civilian regulatory frameworks in North America, Europe, and Asia Pacific are maturing, providing commercial operators with clearer operational parameters and encouraging greater capital deployment into payload-intensive drone fleets.
The market's competitive landscape is defined by a blend of established defense primes, agile commercial drone manufacturers, and specialized sensor technology firms. Northrop Grumman Corporation, Teledyne FLIR LLC, Elbit Systems Ltd, and Israel Aerospace Industries Ltd anchor the high-end defense payload segment, while DJI Technology, Autel Robotics, Parrot SA, and Draganfly Inc dominate the commercial and prosumer payload categories. IMSAR LLC and AeroVironment Inc occupy important mid-tier niches, particularly in SAR payload development and small tactical UAS respectively.
Looking forward through 2033, the Drone Payload Market is expected to benefit from continued integration with artificial intelligence-driven target recognition, autonomous mission management software, and multi-spectral imaging advancements. The convergence of these forces suggests the market will not only sustain its 16.9% CAGR but may experience accelerated inflection points tied to military modernization programs and next-generation civilian infrastructure initiatives. The intersection with broader trends in the Unmanned Aerial Vehicle Market and the Commercial Drone Market further amplifies the long-term growth thesis, as payload capability increasingly defines competitive differentiation across drone platforms.